Category: Luxury Business

The brands, founders and strategies shaping India’s growing luxury industry.

  • INSIDE DUBAI’S WORLD OF ULTRA-LUXURY HOSPITALITY

    INSIDE DUBAI’S WORLD OF ULTRA-LUXURY HOSPITALITY

    Five extraordinary hotels redefining exclusivity, design and the art of being hosted.

    Dubai has mastered the art of making an impression. Its skyline projects ambition, its culinary scene attracts internationally recognised names, and its hospitality industry continues to redefine what a luxury stay can look like. From extraordinary architecture and private-pool villas to destination dining and highly personalised service, the city has transformed the hotel experience into a statement of its own.

    But luxury hospitality is about more than spectacular buildings and lavish interiors. At its highest level, it is an exercise in precision: the atmosphere of a room, the intuitiveness of the service, the quality of the dining and the feeling that every detail has been considered. The strongest hotels do not simply accommodate their guests. They create a world around them.

    Dubai’s tourism performance provides a compelling backdrop to this evolution. According to the Dubai Department of Economy and Tourism, the emirate welcomed 19.59 million international overnight visitors in 2025, marking its third consecutive record-breaking year. Hotel occupancy reached 80.7 per cent, while the average daily room rate rose by 8 per cent to AED 579. Revenue per available room increased by 11 per cent to AED 467.

    The momentum has continued alongside a more complicated operating environment. The latest official tourism report, covering January to August 2026, recorded 6.97 million international overnight visitors. Hotel occupancy had recovered to 66 per cent in August, up from 36 per cent in March, demonstrating a recovery in demand after a difficult period for the travel sector. These figures reflect Dubai’s wider hotel market, rather than luxury properties alone, but they reveal the scale and resilience of the hospitality ecosystem in which its premium hotels compete. (Dubai Tourism Performance Report, January–August 2026)

    As the city’s hotel landscape becomes increasingly competitive, the distinction between luxury and genuine differentiation matters more than ever. A striking address may attract attention, but a memorable experience is what gives a property lasting appeal.

    From a globally recognised resort on Palm Jumeirah to a secluded retreat in the Arabian desert, these five hotels illustrate different expressions of modern luxury in Dubai.

    1. Atlantis The Royal: Where Luxury Becomes Spectacle

    On Palm Jumeirah, Atlantis The Royal represents Dubai’s appetite for hospitality on an extraordinary scale. Its sculptural architecture, expansive terraces, elevated swimming pools and beachfront setting create a resort designed to command attention.

    The property brings together accommodation, wellness, entertainment and an ambitious culinary programme. Its collection of restaurants includes internationally recognised names and chef-led concepts, while its elevated pools, including Cloud 22, make the resort experience part of the visual identity. Suites and signature penthouses extend the sense of exclusivity, with select accommodations offering private pools and sweeping views.

    Dining is central to the proposition. Guests can explore different cuisines and atmospheres without leaving the property, turning the resort into a destination in its own right rather than simply a base from which to discover Dubai. Wellness facilities and extensive leisure experiences further strengthen that all-encompassing approach.

    Its international standing is equally notable. The World’s 50 Best Hotels 2026 placed Atlantis The Royal at No. 4 globally, naming it both the Best Hotel in the Middle East and the Best Beach Hotel for 2026.

    The ranking reinforces the resort’s international profile, but its larger significance lies in how it approaches the guest experience. Atlantis The Royal does not pursue understatement. It embraces scale, energy and spectacle, delivering a version of luxury in which the setting itself becomes part of the entertainment.

    In a city where hotels increasingly compete to become destinations in their own right, Atlantis The Royal demonstrates the power of a fully realised hospitality concept.

    The defining appeal: Architectural spectacle, destination dining, elevated pool experiences and large-scale resort luxury.

    2. Burj Al Arab Jumeirah: The Enduring Power of an Icon

    Few hotels are as closely associated with a destination as Burj Al Arab Jumeirah. Rising from its own island off the Dubai coastline, its sail-inspired silhouette has become one of the most recognisable images in international hospitality.

    The hotel’s significance extends beyond its architecture. It helped establish Dubai’s luxury identity on the global stage, becoming a symbol of the city’s ambition and its willingness to challenge established ideas about what a hotel could represent.

    Inside, the experience centres on suite-led accommodation, highly personalised service and an elaborate approach to hospitality. Dedicated butler service, tailored guest arrangements and carefully choreographed arrival rituals place individual attention at the heart of the stay. The hotel’s dining, wellness and private leisure offerings complete a proposition built around a distinctive sense of occasion.

    Yet the real value of Burj Al Arab lies in its ability to remain relevant after becoming an icon. In an industry where new properties regularly arrive with dramatic architecture and ambitious promises, recognition alone is not enough. A lasting reputation must be supported by service, consistency and an experience that continues to meet contemporary expectations.

    That is what makes the property an important part of Dubai’s luxury story. Its identity is instantly recognisable, but its enduring challenge is to ensure that the experience inside remains as compelling as the image outside.

    Burj Al Arab represents a form of luxury built on legacy: the power of a hotel to become shorthand for an entire destination.

    The defining appeal: Iconic architecture, personalised butler service and a legacy that helped shape Dubai’s global image.

    3. The Lana, Dorchester Collection: A More Considered Expression of Luxury

    Not every luxury experience needs to announce itself through sheer scale. At The Lana, Dorchester Collection, the emphasis shifts towards architecture, design, art and a more measured sense of refinement.

    Located on Marasi Bay Marina in Business Bay, the hotel looks towards the Burj Khalifa and the surrounding cityscape. Its architecture was designed by Foster + Partners, while the interiors were created by the Parisian design studio Gilles & Boissier. The result is a contemporary property shaped by clean lines, carefully selected materials and a curated collection of artworks.

    The Lana features 225 rooms and suites, a rooftop infinity pool, multiple dining concepts and Dior Spa The Lana, which introduced Dior’s spa concept to the UAE. Its restaurants and bars give the hotel a wider social presence, attracting guests who may arrive for dining, wellness or a special occasion as much as for an overnight stay.

    This approach reflects a broader evolution in luxury hospitality. The experience is no longer defined exclusively by the room or the amenities available inside it. Architecture, atmosphere, gastronomy and wellness increasingly work together to shape the identity of a property.

    For travellers who value design and thoughtful curation, the quality of these individual elements can be more meaningful than extravagance for its own sake. A considered interior, attentive service and a distinctive dining experience can create a lasting impression without overwhelming the guest.

    The Lana’s proposition is therefore one of contemporary elegance: a hotel that positions itself as part of Dubai’s cultural and lifestyle landscape while retaining the service traditions associated with Dorchester Collection.

    The defining appeal: Design-led hospitality, curated art, destination dining and contemporary wellness.

    4. One&Only One Za’abeel: A New Perspective on Urban Luxury

    Dubai’s architecture has long served as an expression of its ambition. One&Only One Za’abeel takes that idea into the world of hospitality, creating an urban resort within one of the city’s most striking contemporary developments.

    The hotel occupies the twin-tower One Za’abeel complex, connected by The Link, a 230-metre sky concourse suspended approximately 100 metres above ground. According to the development’s official website, the structure holds the Guinness World Records title for the world’s longest cantilevered building. It also houses restaurants, bars and an elevated infinity pool, making the architecture an integral part of the guest experience. (Explore The Link)

    The resort combines contemporary accommodation with high-profile dining and wellness experiences. Restaurants within The Link include concepts associated with internationally recognised chefs, while the elevated setting gives the dining experience a distinctive relationship with the city below.

    This combination reflects the changing expectations of the luxury traveller. Guests increasingly seek the convenience of a central address without giving up the privacy, comfort and sense of escape associated with a resort. Dining, wellness, architecture and accommodation are brought together in a single destination.

    One&Only One Za’abeel also illustrates how luxury hotels are becoming more integrated into the urban environment. The building is not merely a container for guest rooms; it is a destination with its own identity, drawing attention through engineering, design and experiences that extend beyond the traditional hotel stay.

    Its approach is distinctly contemporary. Rather than relying on heritage or seclusion, the property positions urban energy and architectural ambition at the centre of its appeal.

    The defining appeal: Contemporary architecture, elevated dining, skyline views and an integrated urban-resort experience.

    5. Al Maha, a Luxury Collection Desert Resort & Spa: The Luxury of Disconnection

    Dubai’s luxury identity is often associated with towers, beaches and high-energy city living. Al Maha, a Luxury Collection Desert Resort & Spa, offers a different perspective.

    Set within the Dubai Desert Conservation Reserve, the resort places the Arabian landscape at the centre of the experience. Golden dunes, native wildlife and open desert views replace the density of the city, creating a stay defined by privacy, space and a slower pace.

    The property comprises 42 private villas inspired by Arabian heritage, each featuring its own pool. Interiors incorporate traditional furnishings, handcrafted details and regional artefacts, while the wider experience includes dining, spa facilities and activities such as wildlife drives, camel trekking, falconry and nature walks. The resort’s official property information outlines its location, accommodation and desert experiences.

    Here, luxury is measured differently. It is not about being surrounded by constant activity, but about having the freedom to step away from it. A private villa, an uninterrupted desert view and an experience shaped by the surrounding landscape can offer a form of exclusivity that a city hotel cannot replicate.

    Al Maha also demonstrates why a strong sense of place remains valuable in a globalised hospitality market. International service standards and sophisticated amenities are available in destinations around the world. A meaningful connection to the local environment, however, gives a property a more distinctive identity.

    For travellers seeking a retreat from Dubai’s urban intensity, Al Maha offers a different kind of indulgence — one rooted in nature, privacy and a closer relationship with the desert.

    The defining appeal: Private-pool villas, desert immersion, wildlife experiences and secluded luxury.

    What These Five Hotels Reveal About Dubai’s Luxury-Hospitality Market

    Together, these properties illustrate why Dubai’s luxury-hospitality industry cannot be defined by a single aesthetic or experience.

    Atlantis The Royal builds its identity around spectacle and destination experiences. Burj Al Arab draws on the enduring power of an icon. The Lana emphasises design and curation, while One&Only One Za’abeel brings architecture, dining and wellness into a contemporary urban setting. Al Maha offers a contrasting experience shaped by landscape and seclusion.

    These differences matter because luxury travellers are not a single audience. Some seek recognition, energy and theatrical experiences. Others prioritise privacy, design, gastronomy or a stronger connection to place. The most compelling hotel brands understand the desires they serve and create a coherent experience around them.

    The market data reinforces the importance of differentiation. Dubai welcomed 19.59 million international overnight visitors in 2025, while its hotel inventory reached 154,264 rooms across 827 establishments by the end of that year, according to the Dubai Department of Economy and Tourism. That scale creates opportunities, but it also intensifies competition for attention, bookings and repeat visits.

    The latest available 2026 data adds another dimension. Although hotel occupancy fell sharply during March, it had recovered to 66 per cent by August, while Dubai welcomed 6.97 million international overnight visitors in the first eight months of the year. These figures suggest a recovering market, but they also underline the sensitivity of travel demand to regional and international conditions. (Official January–August 2026 tourism report)

    For luxury properties, the challenge extends beyond attracting a first booking. Striking architecture can generate attention, but repeat business depends on the quality of the experience. A celebrated restaurant can introduce new audiences to a hotel, but service and consistency help sustain its reputation. A private pool or panoramic view may be memorable, but the details surrounding the stay determine whether the experience feels genuinely exceptional.

    Dubai’s advantage is the breadth of its offer. Within one destination, travellers can choose between beachfront spectacle, an internationally recognised icon, contemporary design, an elevated urban resort and a secluded desert retreat.

    The next chapter of the city’s luxury-hospitality story will depend not only on how extraordinary its hotels look, but on how effectively they translate their individual identities into experiences that guests value.

    The Final Word: Luxury Beyond the Address

    The future of luxury hospitality is not simply about building bigger hotels or adding increasingly extravagant amenities. It is about creating experiences with a clear identity — places that know what they stand for and deliver it with consistency.

    Dubai’s standout hotels demonstrate that there is no single formula. Luxury can be theatrical, architectural, personal or profoundly quiet. It can unfold above the skyline, beside the sea or among the dunes.

    The strongest properties do more than provide a room for the night. They create a distinct sense of place, turn service into an art and give travellers a reason to remember the experience long after checkout.

    In a city built on ambition, that may be the most valuable luxury of all.

    INSYDE — Building Bengaluru’s Number One Luxury Magazine

    At INSYDE, we look beyond the obvious to explore the people, places, ideas and experiences shaping the world of luxury. From exceptional hospitality and international destinations to fashion, culture, influential personalities and emerging talent, our editorial lens is guided by curiosity, considered storytelling and a distinctly contemporary perspective.

    Founded with Bengaluru as its starting point and a global outlook at its core, INSYDE is building towards an ambitious vision: to become Bengaluru’s number one luxury magazine, connecting discerning readers with the people, brands and experiences defining what comes next.

    Discover more stories on luxury, culture, people and lifestyle at www.insydemag.com.
  • THE PRICE OF EXCLUSIVITY

    THE PRICE OF EXCLUSIVITY

    Why Luxury Brands Destroy What They Cannot Sell

    Luxury’s obsession with scarcity has a hidden cost. From Burberry’s £28.6 million stock destruction disclosure to the European Union’s new restrictions, the industry is being forced to confront the environmental and commercial consequences of unsold products.

    Luxury is built on desire. A handbag can become a cultural symbol, a watch can represent generations of craftsmanship, and a coat can command a price far beyond the cost of its materials. The promise is that these objects offer something more than utility: heritage, identity, exclusivity and enduring value.

    But what happens when a product is made, the season passes, and nobody buys it?

    For much of the luxury industry, unsold inventory presents a dilemma. Discounting can undermine carefully cultivated price perceptions. Selling through unauthorised channels can weaken control over distribution. Holding stock indefinitely ties up capital and warehouse space. And when products become commercially undesirable, brands must decide whether to resell, repurpose, donate, recycle or dispose of them.

    In documented cases, some luxury companies have gone further, destroying products or buying back unsold merchandise to prevent it from entering discounted markets.

    The practice exposes an uncomfortable contradiction at the heart of luxury: an industry that celebrates craftsmanship and lasting value has, at times, discarded products that still possessed material and functional worth.

    The question is not simply why luxury brands destroy unsold goods. It is whether protecting exclusivity can justify the cost of making valuable products go to waste.

    The Business of Scarcity

    Luxury does not operate like conventional mass-market retail. Its strongest brands sell not only products but also distinction. Carefully controlled distribution, limited availability, heritage and pricing all contribute to the perception that an item is special.

    A product sold at full price reinforces the brand’s intended positioning. The same product appearing repeatedly at steep discounts can change how consumers perceive its value. Customers may begin to delay purchases, expecting future markdowns, while authorised retailers face pressure to compete with cheaper alternatives.

    For a luxury house, the consequences can extend beyond a single unsold item. They can affect pricing discipline, retailer relationships and the perceived desirability of an entire collection.

    This helps explain why luxury businesses have historically sought to control excess inventory rather than automatically clear it through conventional discount channels. Depending on the product and market, options may include transfers between stores, private sales, authorised outlets, buybacks, resale and recycling.

    Destruction is the most extreme response, but it is not the only one. Nor is there evidence that every luxury brand follows the practice.

    The commercial logic is nevertheless clear: a company may judge that the potential damage to its pricing power and brand image outweighs the immediate benefit of selling surplus stock at a lower price.

    That calculation can explain the decision. It does not automatically justify it.

    Burberry’s £28.6 Million Disclosure

    In 2018, British luxury house Burberry became the focus of an international debate after its annual report disclosed that the cost of finished goods physically destroyed during the financial year ending March 2018 was £28.6 million, up from £26.9 million in the previous year. The total included £10.4 million of beauty inventory.

    The figures appeared in the company’s 2017–18 annual reporting, with contemporaneous coverage documenting the disclosure and its implications. The episode prompted questions from consumers, investors and environmental campaigners about why finished products were being destroyed instead of sold, reused or donated.

    The controversy was not simply about the monetary value of the goods. It was about what the practice communicated. A brand associated with craftsmanship, quality and longevity was disposing of products that had already consumed materials, energy, labour and resources.

    On 6 September 2018, Burberry announced that it would stop destroying unsaleable products with immediate effect. In its official statement, the company said it already reused, repaired, donated or recycled unsaleable products and would expand those efforts.

    The chronology matters. The £28.6 million figure is historical, and Burberry’s subsequent announcement was a commitment to end the practice. It should not be interpreted as evidence that the company continues to destroy unsaleable products at the same rate today.

    The case nevertheless established an important precedent: a practice once treated as an operational decision could become a significant reputational issue when its environmental consequences entered public view.

    It also raised a broader question for the industry. If destroying products becomes difficult to defend publicly, what alternatives can preserve commercial value without creating unnecessary waste?

    Richemont and the Cost of Protecting Watch Prices

    The issue has also surfaced in luxury watchmaking.

    In May 2018, reporting by The Guardian revealed that Swiss luxury group Richemont had bought back and destroyed nearly €500 million worth of watches over two years, including unsold timepieces from brands within its portfolio, such as Cartier. The company had been responding to excess inventory and concerns that unwanted watches could enter the grey market at substantial discounts.

    According to the contemporaneous report, the group bought back €278 million of Cartier watches in 2016–17 and a further €203 million of unsold watches in the following year. The timepieces were dismantled and recycled.

    The distinction between retail value, accounting value and the ultimate economic cost is important. The headline figure represents the reported value of the watches involved in the buyback and destruction process; it should not be treated as an equivalent amount of cash simply burned or as a measure of Richemont’s current practices.

    The case demonstrates the particular challenge of managing inventory in a market where perceived value is closely connected to pricing and distribution. A watch may retain valuable materials and exceptional mechanical craftsmanship while becoming difficult to sell through a particular channel without undermining the brand’s intended price positioning.

    Richemont’s experience also illustrates the commercial risk of overstocking. The group was not merely dealing with unwanted objects; it was addressing inventory that had accumulated across its distribution network and threatened to enter unauthorised discount channels.

    The broader lesson is that controlling distribution may protect a brand’s positioning in the short term, but large-scale excess inventory can create costs of its own. Better forecasting and more disciplined production may be more sustainable solutions than repeatedly correcting the problem after products have already been made.

    The Environmental Cost of Unsold Luxury

    Every finished product represents a chain of resources. Fibres, leather, metals, packaging, water, energy, transport and skilled labour are invested long before an item reaches a boutique. When a usable product is destroyed before being worn or used, those resources have been consumed without delivering the intended use of the product.

    The wider textile industry provides an indication of the scale of the problem.

    The European Environment Agency estimates that 4–9% of textile products placed on the European market are destroyed before use, equivalent to approximately 264,000–594,000 tonnes annually. Its research also estimates that around one-third of clothing returned after online purchases is ultimately destroyed on average.

    These findings come from the EEA’s analysis of the destruction of returned and unsold textiles in Europe’s circular economy.

    These are estimates for the wider textile market, not luxury brands alone. Available public data do not establish what proportion of the total is attributable specifically to luxury houses. The figures should therefore be understood as evidence of a systemic textile-waste problem rather than a measurement of luxury’s individual contribution.

    The environmental consequences also extend beyond the act of disposal. Manufacturing products that are never used creates avoidable pressure on resources and generates emissions throughout the supply chain. Recycling can recover some materials, but it does not necessarily recover the energy, labour and resources invested in making the original product.

    For an industry that often promotes durability, repair and timeless design, this creates a fundamental tension. The value proposition of luxury rests partly on the idea that a product should last. Destroying usable goods before they have served their purpose challenges that promise.

    The most effective response is therefore not simply to find a better way to dispose of excess stock. It is to reduce the amount of excess stock created in the first place.

    A Luxury Market Under Pressure

    The issue is becoming more commercially relevant as luxury growth becomes harder to sustain.

    In its June 2026 update, Bain & Company and Altagamma estimated that the global personal luxury goods market was worth €358 billion in 2025. The market declined by 2% at current exchange rates but grew by 1% at constant exchange rates. For 2026, the firms forecast a recovery of 2–4%, placing the market between €365 billion and €373 billion under their base-case scenario.

    The forecast suggests a market stabilising after a difficult period, rather than returning to effortless growth. Performance remains uneven across brands, regions and categories.

    Read Bain & Company’s 2026 luxury-market outlook.

    Reporting on the same research, Reuters noted that the luxury industry had lost approximately 70 million consumers since 2022, with price increases and a greater concentration on high-spending customers contributing to a narrower customer base. The report also highlighted the growing role of the second-hand market, with roughly half of luxury shoppers consulting resale before buying new products.

    Read Reuters’ analysis of the luxury market in 2026.

    These developments do not prove that luxury brands are destroying more products. They do, however, make inventory management more important.

    When customers become more selective, resale becomes more visible and growth slows, brands face greater pressure to align production with actual demand. Products that fail to sell represent not only a potential environmental liability but also capital tied up in stock, storage and distribution.

    The industry must therefore confront two related questions: how can brands protect the value of their products, and how can they avoid manufacturing more than the market is prepared to absorb?

    The answer may lie in a more disciplined definition of exclusivity — one based on product quality, design and enduring desirability rather than the management of unwanted inventory after the fact.

    The EU’s New Rules Change the Equation

    The debate is no longer limited to consumer pressure and voluntary sustainability commitments. Regulation has begun to change the options available to companies.

    On 19 July 2026, a new European Union measure under the Ecodesign for Sustainable Products Regulation began prohibiting large companies operating in the EU from destroying unsold clothing, clothing accessories and footwear. Medium-sized companies are scheduled to become subject to the same rules from 2030.

    Under the measure, businesses must prioritise keeping products in use. This can include selling goods through existing or alternative channels, donating suitable products, or preparing them for reuse through repair, refurbishment or remanufacturing.

    Destruction remains possible in specified circumstances, including certain cases involving unsafe, damaged or counterfeit goods, intellectual-property infringement, or products rejected by eligible donation schemes. Applicable requirements and exemptions must be followed.

    The European Commission has outlined the measure and its scope in its official announcement on the ban on destroying unsold clothes and shoes.

    The regulation does not apply universally to every luxury product or every company worldwide. Its immediate scope concerns specified categories of clothing, clothing accessories and footwear within the EU framework. Watches, jewellery, fragrances and other product categories should not automatically be assumed to fall under the same destruction prohibition.

    For luxury fashion houses operating in Europe, however, the change is significant. Destruction can no longer be treated simply as a discretionary inventory-management choice for the products covered by the rules. Businesses must consider viable routes for keeping unsold goods in circulation and comply with the relevant documentation and reporting requirements.

    The regulatory shift also creates a commercial incentive to address the problem earlier. Better forecasting, tighter production planning, repair programmes and structured resale channels can reduce the amount of inventory that reaches the point at which it is difficult to sell.

    The direction is clear: the cost of excess inventory is increasingly measured not only in financial terms, but also in environmental impact and regulatory exposure.

    What Luxury Brands Can Do Instead

    There is no single solution for every unsold product. A returned handbag, an outdated seasonal garment, a damaged shoe and a defective cosmetic product each present different challenges. Nevertheless, several approaches can reduce the need for destruction.

    Produce more precisely. Improved demand forecasting, smaller initial production runs and more responsive replenishment can reduce the risk of creating surplus inventory. The aim is not to eliminate every forecasting error, but to prevent avoidable overproduction.

    Create controlled second-life channels. Authorised resale, repair, refurbishment and selected outlet channels can keep products in circulation while allowing brands to retain appropriate standards of authentication, service and presentation.

    Make donation operationally viable. Donation can provide a route for suitable unsold goods, but it requires reliable partners, appropriate product condition and careful logistics. It is not a universal answer for every product category.

    Design for longevity and repair. Durable construction, replaceable components and access to repair services can extend the useful life of products and preserve value beyond the first sale.

    Recover materials where reuse is not possible. Recycling and material recovery can help reduce waste, although their environmental benefits depend on the materials involved and the effectiveness of the recovery process.

    Improve transparency. More consistent disclosure about unsold inventory, reuse, donation, recycling and disposal would allow consumers, investors and regulators to evaluate corporate sustainability commitments against operational outcomes.

    These measures will not remove every commercial constraint. Luxury brands must still protect intellectual property, product safety and the integrity of their distribution networks. But those objectives do not necessarily require usable goods to be destroyed.

    The more ambitious solution is to treat unsold inventory as a problem to prevent, not merely a liability to manage.

    What Is Exclusivity Really Worth?

    Luxury has always depended on a carefully managed relationship between scarcity and desire. A product can become exceptional because of its craftsmanship, its history, its design or the meaning consumers attach to it. Its value does not have to depend on the disappearance of everything that fails to sell.

    The historical cases of Burberry and Richemont demonstrate that the destruction of unsold goods has been a real, documented practice within the luxury sector. The European Union’s new restrictions show that the issue has moved beyond reputational controversy into regulation. Meanwhile, a more selective market makes disciplined production and inventory management increasingly important to the industry’s commercial future.

    The challenge is not to make every luxury product permanently available at a discount. It is to build a system in which products can retain value even when they do not sell at the intended price, and in which brands take responsibility for the resources invested in their creation.

    Luxury can protect its identity through quality, craftsmanship, service, innovation and genuine desirability. It can control distribution without treating every unsold item as a threat. And it can pursue exclusivity without assuming that waste is an unavoidable cost of doing business.

    Ultimately, a truly exceptional product should justify its worth through what it is — not through what a brand must destroy to protect its price.

    Because when exclusivity comes at the expense of usable products, the question is no longer only what luxury is worth. It is what the industry is willing to waste to preserve its value.

    INSYDE Magazine — the top luxury magazine in Bangalore

    Luxury. Culture. The People Shaping What Comes Next.

  • INSIDE THE F1 EMPIRE – THE BILLION-DOLLAR RACE

    INSIDE THE F1 EMPIRE – THE BILLION-DOLLAR RACE

    Inside the billions, billionaires and global spectacle powering Formula 1

    Formula 1 has become far more than a motorsport championship. With billions in annual revenue, a reported global fanbase of 827 million and a growing presence in luxury, entertainment and premium experiences, F1 is building one of the most commercially powerful brands in world sport.

    INSYDE Magazine | Business, Luxury & Culture


    The Billion-Dollar Race

    Every Formula 1 race is decided by fractions of a second. The business behind it, however, is built over years of contracts, commercial partnerships, technological investment and global audience development.

    A car crosses the finish line. A championship is decided. But behind the spectacle sits a much larger operation—one that sells broadcasting rights, secures sponsorship agreements, licenses races to host cities and turns a sporting calendar into a global entertainment property.

    The financial scale is substantial. In its 2025 financial results, Liberty Media reported that Formula 1 generated US$3.873 billion in revenue in 2025, up from US$3.411 billion in 2024. Operating income rose to US$632 million, while adjusted operating income before depreciation and amortisation—known as adjusted OIBDA—reached US$946 million.

    That represents revenue growth of approximately 13.5 per cent year on year, alongside a 28 per cent increase in operating income.

    These are not small numbers for a sport built around a limited number of live events each year. They reflect the strength of a business model in which the same championship can generate income from broadcasters, sponsors, race promoters, digital services and premium experiences across multiple markets.

    And the momentum has continued into 2026. Formula 1’s mid-season review, published in July 2026, reported nearly 3.7 million race-weekend attendances across the first 11 events, approximately 6 per cent above the same events in 2025. All 11 events had sold out at the time of the review.

    The financial results for the full 2026 season are not yet available. But the mid-season numbers provide a current indication of demand.

    The bigger question is what makes this business so valuable—and how much of the global economy surrounding Formula 1 is actually captured by its headline revenue.

    First, Understand What the $3.87 Billion Actually Means

    Formula 1’s US$3.873 billion figure represents revenue reported by the championship’s commercial business. It is not the combined turnover of every team, sponsor, circuit, broadcaster, hospitality provider and supplier connected to the sport.

    That distinction is essential.

    The wider F1 ecosystem includes independently operated teams, manufacturers, race promoters, television networks, sponsors, travel companies, hospitality businesses and numerous suppliers. Their revenues overlap in different ways, and there is no single, comprehensive figure that captures the entire ecosystem without risking double-counting.

    Formula 1’s own financial disclosures provide the clearest starting point.

    According to Liberty Media’s 2025 annual report, the championship generated US$3.086 billion in primary revenue and US$787 million in other revenue during 2025.

    Primary revenue grew from US$2.757 billion in 2024, while other revenue increased from US$654 million. Together, they brought total reported revenue to US$3.873 billion.

    The difference between revenue and profit also matters. Formula 1 reported US$632 million in operating income, not US$3.873 billion in profit. Its reported operating expenses, administrative costs, depreciation and other items sit between the revenue figure and the operating result.

    For investors and business analysts, the distinction is fundamental: revenue measures the money a business earns from its operations, while operating income reflects what remains after relevant operating costs and expenses.

    Formula 1 is not simply large. It is a rights-based business with a substantial cost structure and a globally distributed commercial model.

    Where Does Formula 1 Make Its Money?

    Formula 1’s commercial structure is built around three principal revenue engines: race promotion, media rights and sponsorship. Its additional revenue streams include hospitality, logistics, support championships, digital activities and licensing.

    The categories are described in detail in Liberty Media’s annual filing.

    1. Media Rights: Selling the Race to the World

    Formula 1 does not need every fan to attend a Grand Prix to monetise their interest in the championship.

    Through media-rights agreements, broadcasters and streaming platforms pay for the right to show races and associated programming in their respective markets. These agreements allow Formula 1 to reach audiences across countries while creating recurring commercial relationships.

    For broadcasters, the attraction is live sport, dramatic competition, recognisable personalities and programming that can draw viewers throughout a season. For Formula 1, media distribution expands the audience beyond the physical limits of a circuit.

    The business is particularly powerful because a single season produces a continuing schedule of events. Each race creates fresh content, new narratives and further opportunities for advertisers and partners.

    Formula 1 also operates its own digital subscription service, F1 TV, and earns revenue from licensing footage and other media-related activities.

    The financial importance of media rights is not just the size of an individual contract. It is the ability to build a portfolio of agreements across markets, with contract terms that can extend across multiple years.

    That gives the business a degree of commercial continuity even as individual races, teams and championship outcomes change.

    2. Race Hosting: Why Cities Pay to Join the Calendar

    A Grand Prix can deliver a city something that conventional advertising rarely offers: several days of international attention tied to a live event.

    Formula 1 earns race-promotion revenue by granting promoters the rights to host, stage and promote events. These arrangements are generally governed by contracts, and the fees differ according to the event, market and commercial terms.

    In its 2025 annual report, Liberty Media disclosed that race-promotion revenue accounted for 26.7 per cent of Formula 1’s total revenue in 2025.

    Applying that reported share to total revenue puts race-promotion revenue at approximately US$1.03 billion for the year. This is an arithmetic estimate based on the disclosed percentage, rather than a separately quoted exact revenue figure.

    That makes hosting agreements a major pillar of the business.

    For a host destination, the attraction may include tourism, hotel occupancy, international media exposure, corporate networking and the chance to position the city as a centre for business and entertainment.

    But a Grand Prix is not automatically profitable for its host. Staging costs can be high, and the economic benefits depend on factors such as ticket sales, sponsorship, visitor spending, public investment and the terms of the hosting agreement.

    A race can create enormous visibility without necessarily delivering the same financial return to every stakeholder.

    The commercial question is whether the event’s long-term benefits justify its cost.

    3. Sponsorship: The Value of Being Associated With F1

    Formula 1 is an attractive platform for brands because it combines global reach with associations that are difficult to manufacture through traditional advertising alone.

    Performance. Precision. Engineering. Speed. Innovation. Exclusivity.

    Sponsors can integrate themselves into the championship through team partnerships, car liveries, driver apparel, trackside advertising, branded content, digital campaigns and hospitality experiences.

    The relationship can be especially valuable when a partnership goes beyond logo placement. A technology company may use Formula 1 to demonstrate engineering expertise. A financial institution may connect the sport with performance and international business. A luxury brand may use the paddock to communicate craftsmanship, prestige and access.

    Formula 1’s 2025 results included a new multi-year sponsorship agreement with Standard Chartered, alongside continuing commercial partnerships and broadcast arrangements. The announcement is documented in Liberty Media’s year-end results.

    For sponsors, the commercial opportunity extends across the season. A brand can appear in race coverage, social content, driver interviews, event activations and premium hospitality environments.

    For Formula 1, those relationships help monetise its audience and brand beyond the ticket-buying spectator.

    827 Million Fans: The Audience Behind the Business

    A global sports business becomes more valuable when its audience expands. In Formula 1’s case, the audience is also changing.

    According to Formula 1’s official 2025 season review, the sport’s reported global fanbase reached 827 million people in 2025—up 12 per cent year on year and 63 per cent compared with 2018.

    Formula 1 also reported that 43 per cent of its global fanbase was under 35, while women accounted for 42 per cent. The proportion of female fans had risen from 37 per cent in 2018.

    These are Formula 1’s own published fanbase estimates, not a census of unique people who watched every race. Even with that qualification, the figures point to a championship expanding its reach beyond its traditional audience.

    This matters because younger and more diverse audiences can open doors to new categories of advertisers, sponsors and entertainment partners.

    A fan might first discover Formula 1 through a driver on social media, a documentary, a video game, a fashion collaboration or a clip from a dramatic race. The route into the sport no longer begins and ends with watching a full Grand Prix broadcast.

    That creates more opportunities for Formula 1 to convert attention into participation—and, ultimately, commercial value.

    India: A Market Worth Watching

    For an Indian publication, the global fanbase figures are particularly relevant.

    Formula 1’s published 2025 season review put its Indian fanbase at 78.8 million. The same report listed China at 221.1 million, demonstrating the scale of the sport’s Asian audience.

    These are estimates published by Formula 1 and should be attributed accordingly. They do not mean that every person counted watches every race or represents an active paying customer.

    Nevertheless, the scale is significant for brands seeking to reach Indian audiences interested in technology, cars, fashion, entertainment and premium experiences.

    India has a large digital audience and a growing market for international entertainment and premium consumer brands. Formula 1’s commercial opportunity lies in connecting that audience with accessible digital content, broadcast distribution, sponsorships and experiences that are relevant to the market.

    The challenge is converting interest into sustained engagement and spending. A large fanbase is an asset, but it is not the same as a large paying customer base.

    The Digital Economy: Formula 1 Never Really Leaves the Track

    The business of Formula 1 continues between race weekends.

    Its drivers and teams produce a steady stream of interviews, behind-the-scenes footage, technical explanations, short-form videos and social media moments. That content gives the championship a presence long after the cars return to the garages.

    Formula 1’s 2025 season review reported more than 2.3 billion social media engagements across its platforms during the year.

    Engagement is not the same as unique viewers, and it should not be treated as direct revenue. But it demonstrates how the sport can extend a live event into a much wider digital conversation.

    A dramatic overtake may become a short video. A driver’s radio message may turn into a meme. A team launch may generate weeks of discussion before the first race. Each moment gives the championship another opportunity to reach fans and commercial partners.

    This is particularly important for a sport whose events take place across different time zones. Social media allows fans to follow the championship even when they cannot watch a race live.

    The business implication is clear: Formula 1 is selling more than the broadcast of a sporting event. It is building a year-round entertainment ecosystem around the event.

    That ecosystem creates additional inventory for sponsors, new ways to engage fans and a stronger relationship between the championship and its audience.

    Luxury, Monaco and the Business of Access

    Formula 1’s relationship with luxury is not incidental. The sport brings together high-performance engineering, international travel, premium hospitality and a clientele that includes business leaders, celebrities, investors and brand executives.

    Monaco is the clearest illustration. The Grand Prix unfolds in a destination already associated with superyachts, luxury hotels, high-end retail and international wealth. The race becomes a sporting event and a social setting at the same time.

    Yet the luxury economy around Formula 1 extends beyond one location.

    Premium hospitality offerings can include trackside suites, curated dining, exclusive viewing areas and access to parts of the race-weekend environment that are not available to ordinary ticket holders. Formula 1’s own Paddock Club offering sits within this broader market for premium race experiences.

    The appeal is not simply watching cars go by. It is proximity—to the teams, the drivers, the engineering and the atmosphere surrounding the championship.

    For businesses, hospitality can also be a relationship-building tool. Corporate guests can meet clients, entertain partners and participate in an environment that communicates status and exclusivity.

    For luxury brands, Formula 1 provides a stage where performance and prestige can coexist. Watchmakers, fashion houses, automotive brands and premium consumer businesses can use partnerships and event activations to connect with an audience already immersed in those values.

    The commercial opportunity is to sell not just a seat, but an experience.

    The Real Cost of Going to a Grand Prix

    The premium nature of Formula 1 creates opportunities, but it also introduces a clear divide between different ways of experiencing the sport.

    At one end, fans watch through television, streaming and social media. At the other, spectators can pay for premium grandstand locations, hospitality packages, travel and accommodation in some of the world’s most expensive destinations.

    The total cost of attending varies considerably by race, ticket category, travel arrangements and accommodation. There is no single price that accurately represents a Formula 1 weekend.

    For a destination such as Monaco, hotel and travel costs can be a major part of the overall expenditure. Other races may offer different price points, although flights, accommodation and local transport can still make attendance expensive.

    This tiered model is commercially useful. Formula 1 can reach millions of fans digitally while also selling premium experiences to customers willing to spend significantly more for access.

    The business must, however, balance exclusivity with accessibility. If attending a race becomes prohibitively expensive for too many fans, the championship risks limiting one of the most important ways audiences develop a deeper connection with the sport.

    The strongest model is one in which mass reach and premium experiences reinforce each other rather than compete.

    The Teams: A Different Financial Race

    Formula 1’s commercial revenue is only one part of the financial picture. The ten teams operate their own businesses, with separate sponsorships, technical programmes, personnel costs and commercial arrangements.

    Their economics are shaped by the expense of designing, developing and operating competitive cars. Teams must invest in engineering, research, manufacturing, logistics and specialist staff, all while competing under the sport’s technical and financial regulations.

    The cost cap constrains specified categories of team expenditure, but it should not be mistaken for a universal limit on every cost associated with running a Formula 1 operation. The applicable rules contain defined exclusions and adjustments.

    The financial position of one team can also differ substantially from another, depending on sponsorship, ownership, manufacturer support, commercial success and performance.

    This is why the championship’s US$3.873 billion revenue should not be presented as the combined revenue of all teams, nor should it be used to infer that every team is equally profitable.

    Formula 1’s central commercial business and its competitors have related but distinct economics. One sells the championship’s commercial rights; the others compete within the series while building their own commercial operations.

    That distinction is critical to understanding where the money flows—and who ultimately benefits.

    2026: A New Era, a New Commercial Test

    The 2026 season represents a major technical transition for Formula 1, with new power-unit and chassis regulations changing the engineering challenge for teams and manufacturers.

    The regulatory framework has been developed by the FIA, with details available through its official Formula 1 regulations announcements. For manufacturers, regulatory changes can create new opportunities to demonstrate engineering capability. For teams, they introduce technical uncertainty and the need to adapt.

    For the commercial business, a new era offers an opportunity to renew audience interest, attract partners and tell a fresh story around the championship. But it also creates risks: fans may react differently to the racing, teams may experience changing competitive fortunes, and manufacturers must judge the value of continued investment.

    The latest published 2026 attendance data provides a positive early signal. In its July 2026 mid-season review, Formula 1 reported nearly 3.7 million attendees across the first 11 race weekends, compared with 3.4 million across the corresponding events in 2025. All 11 events had sold out.

    That is approximately 6 per cent growth in attendance across the comparable events.

    It is a meaningful indicator of live demand, but it is not a complete measure of financial performance. Attendance alone cannot establish whether revenue, operating income or profitability has increased at the same rate.

    The full-year financial results will provide a more complete picture once published.

    For now, the central test is whether Formula 1 can preserve its audience momentum while continuing to make the championship commercially attractive to broadcasters, sponsors, teams and host destinations.

    Is Formula 1 One of the World’s Most Powerful Sports Businesses?

    The evidence points to a championship with substantial commercial scale and a diversified revenue model.

    Its 2025 financial results show US$3.873 billion in revenue and US$632 million in operating income. Its reported global fanbase reached 827 million, while its season attracted 6.7 million race attendances and generated more than 2.3 billion social media engagements.

    The figures measure different things. Revenue captures the commercial income reported by Formula 1’s business. Operating income reflects the result after relevant operating costs. Fanbase estimates describe the championship’s claimed global reach, while attendance and social engagement measure activity in physical and digital environments.

    Together, they show how Formula 1 has built a commercial platform that extends far beyond the circuit.

    Its model combines recurring media-rights agreements, race-hosting fees, sponsorships, licensing, hospitality and digital distribution. Around that core sits a wider ecosystem of teams, manufacturers, broadcasters, tourism businesses and premium brands.

    But the size of the business should not obscure its risks. High operating costs, expensive event infrastructure, dependence on audience demand and the challenge of sustaining interest all matter. Nor should Formula 1’s revenue be confused with the total economic impact of the sport or the profits earned by its individual participants.

    The next phase of growth will depend on more than adding fans. It will require the championship to keep those fans engaged, demonstrate value to commercial partners and maintain a compelling sporting product through technical and competitive change.

    The Final Lap

    Formula 1 may be decided on Sunday, but its business is built all year.

    The championship sells broadcasters access to live competition, gives sponsors a global stage, offers cities a high-profile event and provides fans with experiences ranging from a mobile screen to a premium hospitality suite.

    Its cars are the most visible part of the product. The real commercial engine is the world built around them: the rivalries, the technology, the drivers, the destinations and the audience that returns for every race.

    For INSYDE, Formula 1 is a revealing case study in the convergence of business, luxury and culture. It shows how a sport can turn performance into a brand, attention into commercial opportunity and a calendar of races into a global entertainment property.

    The fastest car may win the race. The bigger business is the one that keeps the world watching.


    INSYDE | Luxury, Through a Different Lens

    Sources & Reporting

    Data note: Full-year financial figures in this article refer to the 2025 reporting year. 2026 attendance figures are from Formula 1’s July 2026 mid-season review and should not be interpreted as full-season totals. Fanbase and engagement figures are attributed to Formula 1’s own published reporting. The estimated race-promotion revenue is calculated from the share disclosed in Liberty Media’s annual filing.

    INSYDE MAGAZINE
    Bengaluru’s No. 1 Luxury Magazine

    Luxury, Through a Different Lens
    www.insydemag.com

  • PEN BRANDS OF THE ULTRA-RICH

    PEN BRANDS OF THE ULTRA-RICH

    Five luxury pen houses where heritage, artistry and precision turn an everyday object into a statement of taste.

    A signature can close a billion-dollar deal. It can authenticate a masterpiece, formalize an acquisition or mark the beginning of a legacy. Yet the object behind that signature is often overlooked.

    In an age when messages disappear into screens and contracts are completed with a click, the luxury pen occupies a different kind of space. It is tactile, personal and deliberately old-fashioned. It asks you to slow down.

    For the discerning collector, a pen can be far more than a writing instrument. It can represent a century of craftsmanship, a rare artistic tradition or a fascination with the smallest details. And at the highest end of the market, the difference between an ordinary pen and an extraordinary one can be measured in hours of handwork, intricate finishing and the scarcity of a particular edition.

    The appeal is not simply about spending more. It is about knowing what you are paying for.

    A BILLION-DOLLAR MARKET, BUILT ON THE DETAILS

    The luxury pen industry is larger than its niche reputation might suggest. According to Grand View Research’s August 2026 market report, the global luxury-pen market was valued at an estimated US$3.6 billion in 2025. The firm projects it will reach US$3.7 billion in 2026 and US$5 billion by 2033, representing a forecast compound annual growth rate of 4.4% between 2026 and 2033.

    The report estimates that fountain pens accounted for 41.5% of market revenue in 2025, making them the largest product segment. The mid-luxury category represented 45.2%, while offline retail accounted for 72.4% of sales. Europe held the largest regional share, at 32.6%.

    These figures are commercial research estimates, not audited industry-wide sales disclosures. They nevertheless point to an important distinction: luxury writing instruments are not sustained by ultra-expensive collector pieces alone. The market also depends on everyday premium products, personalization, gifting and the experience of examining an instrument before buying it.

    The most interesting end of the market, however, is where a pen becomes something closer to an object of art.

    01. MONTBLANC — THE POWER OF AN ICON

    Few writing-instrument names have achieved the cultural recognition of Montblanc.

    The German luxury house introduced its Meisterstück in 1924. Over the following century, its distinctive silhouette and enduring design helped turn it into one of the most recognizable names in fine writing. The collection marked its centenary in 2024.

    Montblanc’s strength is the balance between familiarity and aspiration. Its writing instruments are associated with professional achievement, milestone gifting and the rituals of business, but the brand’s collectible editions offer a different proposition.

    The Great Characters collection draws inspiration from influential figures and cultural icons. Its Homage to The Great Gatsby Limited Edition 1925 fountain pen, for example, is listed at US$5,300 on Montblanc’s US website. The edition connects the writing instrument to the visual language of the Jazz Age and F. Scott Fitzgerald’s celebrated novel.

    That price is for a specific limited edition, not a representative price for all Montblanc pens. The brand’s wider collection spans considerably different price points.

    What makes Montblanc compelling is its ability to turn a recognisable design into a personal object. For one owner, it may be a daily writing companion. For another, a particular edition may represent a favourite author, an important achievement or a carefully chosen collectible.

    The luxury proposition: An enduring design icon with a bridge between professional life, cultural references and collecting.

    02. NAMIKI — THE ART OF JAPANESE LACQUER

    Some luxury objects announce their value immediately. Others reward a closer look.

    Namiki belongs firmly in the second category.

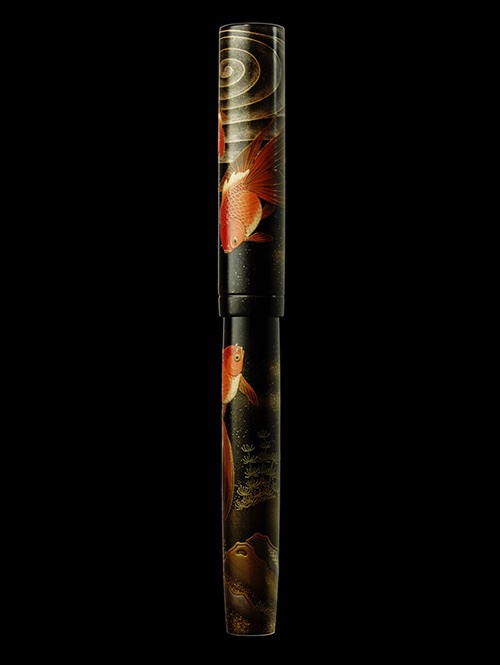
    The Japanese brand’s history of maki-e fountain pens dates to 1925. Maki-e is a traditional decorative technique that involves building intricate designs through layers of lacquer and the application of materials such as metallic powders. The process demands specialist knowledge, patience and careful execution.

    According to Namiki’s official history, the company explored lacquer as a durable and beautiful material for fountain-pen bodies before developing decorated designs that brought Japanese artistic traditions to writing instruments.

    The result is a different expression of luxury. Rather than relying solely on a familiar logo or precious-metal finish, Namiki places the decorative work at the centre of the object. Nature, mythology and traditional Japanese motifs can become elaborate compositions across a pen’s surface.

    The craftsmanship is not incidental decoration. It is the reason the object exists in that particular form.

    For collectors, this creates a more intimate relationship with ownership. The attraction may lie in the visual complexity of a design, the skill required to produce it or the connection to a tradition passed between generations of artisans.

    Namiki also challenges the assumption that luxury must always be loud. A pen can be extraordinary without relying on conspicuous branding. Its value can be found in the work that only becomes apparent when someone takes the time to look.

    The luxury proposition: Traditional Japanese artistry, intricate lacquerwork and craftsmanship that transforms a writing instrument into a miniature canvas.

    03. S.T. DUPONT — FRENCH REFINEMENT IN EVERY DETAIL

    S.T. Dupont approaches luxury through precision, finish and the relationship between an object and its owner.

    The French house’s Classique pen has an origin story that captures this philosophy. According to S.T. Dupont’s official account, Jacqueline Kennedy Onassis requested a writing instrument to match her S.T. Dupont lighter. The company, which had not previously manufactured pens, took on the challenge and adapted the lighter’s design language to create its first writing instrument.

    The resulting Classique design drew on the lighter’s metalwork and vertical guilloché detailing. It was an exercise in translating the character of one luxury object into another.

    That attention to detail remains central to the appeal of the house’s writing instruments. Surface patterns, lacquer, polished metal and the proportions of the body all contribute to the experience. The pen is not merely a vessel for ink; it is an object designed to feel considered in the hand and distinctive on a desk.

    There is a certain intimacy to this kind of luxury. A writing instrument is handled repeatedly, often during moments that matter: a personal letter, a formal agreement, a handwritten note or a significant gift. The quality of its design becomes part of the ritual.

    S.T. Dupont’s appeal is therefore less about size or spectacle than about refinement. The details are the point.

    The luxury proposition: French design heritage, refined metalwork and an understated approach to personal luxury.

    04. CARAN D’ACHE — SWISS PRECISION AT ITS MOST EXTRAVAGANT

    Caran d’Ache brings Switzerland’s tradition of precision and technical design into the world of writing instruments.

    Founded in Geneva in 1915, the company produces its writing and drawing instruments in Switzerland. Its range extends from accessible premium stationery to limited editions that explore elaborate materials, intricate finishing and ambitious design concepts.

    One example is the 1010 Timekeeper Fountain Pen Limited Edition. On its US website, Caran d’Ache lists the model at US$14,325.

    The design draws inspiration from the world of fine watchmaking, including the visual language of watch dials and crowns. The company highlights techniques including guilloché, engraving, manual polishing, lacquering and PVD treatment.

    This is where the relationship between watches and pens becomes particularly interesting. Both objects combine engineering with personal taste. Both can be judged on their practical performance, yet their most collectible versions are often appreciated for the design decisions and technical work that go into them.

    The price of the 1010 Timekeeper is a useful illustration of how far a luxury writing instrument can extend beyond everyday utility. It is not a typical Caran d’Ache price, nor should it be taken as representative of the brand’s broader collection. It is a specific limited edition at the upper end of its range.

    At this level, the appeal lies in the convergence of design, specialist finishing and scarcity.

    The luxury proposition: Swiss manufacturing and technical precision, expressed through highly elaborate limited editions.

    05. MONTEGRAPPA — ITALIAN CHARACTER, COLLECTOR APPEAL

    Montegrappa offers a more expressive interpretation of luxury writing.

    Its history began in 1912, when a group of industrialists established Italy’s first nib factory in Bassano Veneto, now Bassano del Grappa. The company subsequently developed its own fountain pens and built a reputation around Italian manufacturing and design.

    The house’s official history describes a tradition shaped by the artisanal culture of the Veneto region. That heritage continues to inform its identity, alongside an appetite for distinctive designs and themed collections.

    Montegrappa is particularly interesting for collectors who want an object to communicate something about their interests. Its writing instruments have explored subjects from cultural figures and literature to entertainment and history. This can make the choice of pen feel more personal than simply selecting a familiar luxury name.

    A collector might be drawn to a particular edition because of its visual language, the story behind it or the subject it commemorates. Another buyer may prefer a more restrained design from the brand’s wider range.

    That breadth is important. Luxury collecting is not a single aesthetic, and a high price does not automatically make an object desirable. For many enthusiasts, the strongest connection comes from finding a design that feels individual.

    Montegrappa’s character-driven approach gives it a distinct place among established writing houses: it treats the pen as a canvas for identity as well as a tool for writing.

    The luxury proposition: Italian heritage, expressive design and collectible instruments that appeal to personal interests.

    WHAT ACTUALLY MAKES A LUXURY PEN EXPENSIVE?

    The price of a luxury pen is rarely explained by a single material or manufacturing decision. Several factors can combine to create a substantial premium.

    Craftsmanship and finishing. Specialist nib work, engraving, lacquer application, polishing and assembly can require considerable skill. Techniques such as Namiki’s maki-e are particularly labour-intensive because the decorative surface is built through a series of carefully controlled processes.

    Materials and construction. Precious metals, specialist finishes and complex components can affect manufacturing costs. Their influence varies by model, and a premium material alone does not establish a pen’s overall quality.

    Design and heritage. Established houses carry histories, recognisable design languages and reputations built over decades. For some buyers, that continuity is part of the appeal.

    Limited production. A restricted edition can attract interest when it combines a distinctive concept, desirable execution and genuine collector demand. However, limited availability does not guarantee that a pen will appreciate in value.

    Personalisation and meaning. Engraving, bespoke details and the circumstances in which a pen is purchased can make it deeply personal. A writing instrument given to mark a career milestone may be valued for reasons that have little to do with its resale price.

    It is also worth separating luxury from investment. Some pens become sought-after collectibles, but future value is uncertain. Condition, authenticity, provenance, rarity and market demand all matter. A buyer should not assume that an expensive pen will generate a financial return.

    WHY THE PEN STILL MATTERS IN A DIGITAL WORLD

    The continued appeal of fine writing instruments is not simply a nostalgic rejection of technology. It is a reminder that convenience and experience are not always the same thing.

    Digital tools are faster for most routine communication. A luxury pen offers something different: the physical sensation of writing, the rhythm of forming words by hand and the pleasure of using an object made with care.

    That distinction is relevant to the wider luxury market. Consumers can buy functional objects at almost every price point. The products that inspire deeper attachment often offer something beyond basic utility: a story, a craft tradition, an individual aesthetic or a connection to a meaningful moment.

    Fine writing instruments sit comfortably within that world. They can be used every day, displayed as part of a collection or kept for occasions when the act of writing deserves attention.

    They also occupy an unusual position between personal luxury and gifting. A pen can be chosen for its design, presented to mark an achievement or retained as a reminder of a relationship. Unlike a digital signature, the physical object can remain long after the moment has passed.

    THE FINAL WORD

    Montblanc represents the power of an icon. Namiki turns traditional Japanese craftsmanship into a form of wearable-scale art. S.T. Dupont brings French refinement to the smallest details. Caran d’Ache explores the possibilities of Swiss precision, while Montegrappa gives collectors a more expressive design language.

    These five houses demonstrate that luxury writing is not defined by one price bracket or a single idea of status. Their collections span different budgets, and not every instrument is intended for the wealthiest buyer.

    What connects them is the belief that an everyday object can become something worth keeping.

    The finest luxury pens do more than put ink on paper. They bring together design, craft, heritage and personal meaning in a form that can be held in the hand.

    In a world that rarely asks us to slow down, perhaps that is the ultimate luxury: not simply owning something expensive, but owning something worth taking the time to appreciate.

    INSYDE MAGAZINE– NO.1 LUXURY MAGAZINE IN BENGALURU

  • THE $50 MILLION FANTASY BRA

    THE $50 MILLION FANTASY BRA

    Jacob & Co. × Victoria’s Secret: Where Diamonds, Desire and Fashion Spectacle Collide

    INSYDE Magazine | Fashion, Luxury & Culture

    More than 4,400 diamonds, a 75.54-carat yellow diamond and over 1,000 hours of craftsmanship. As Victoria’s Secret revives its most extravagant runway tradition with Jacob & Co., the Fantasy Bra reveals how luxury transforms exceptional materials into global spectacle.

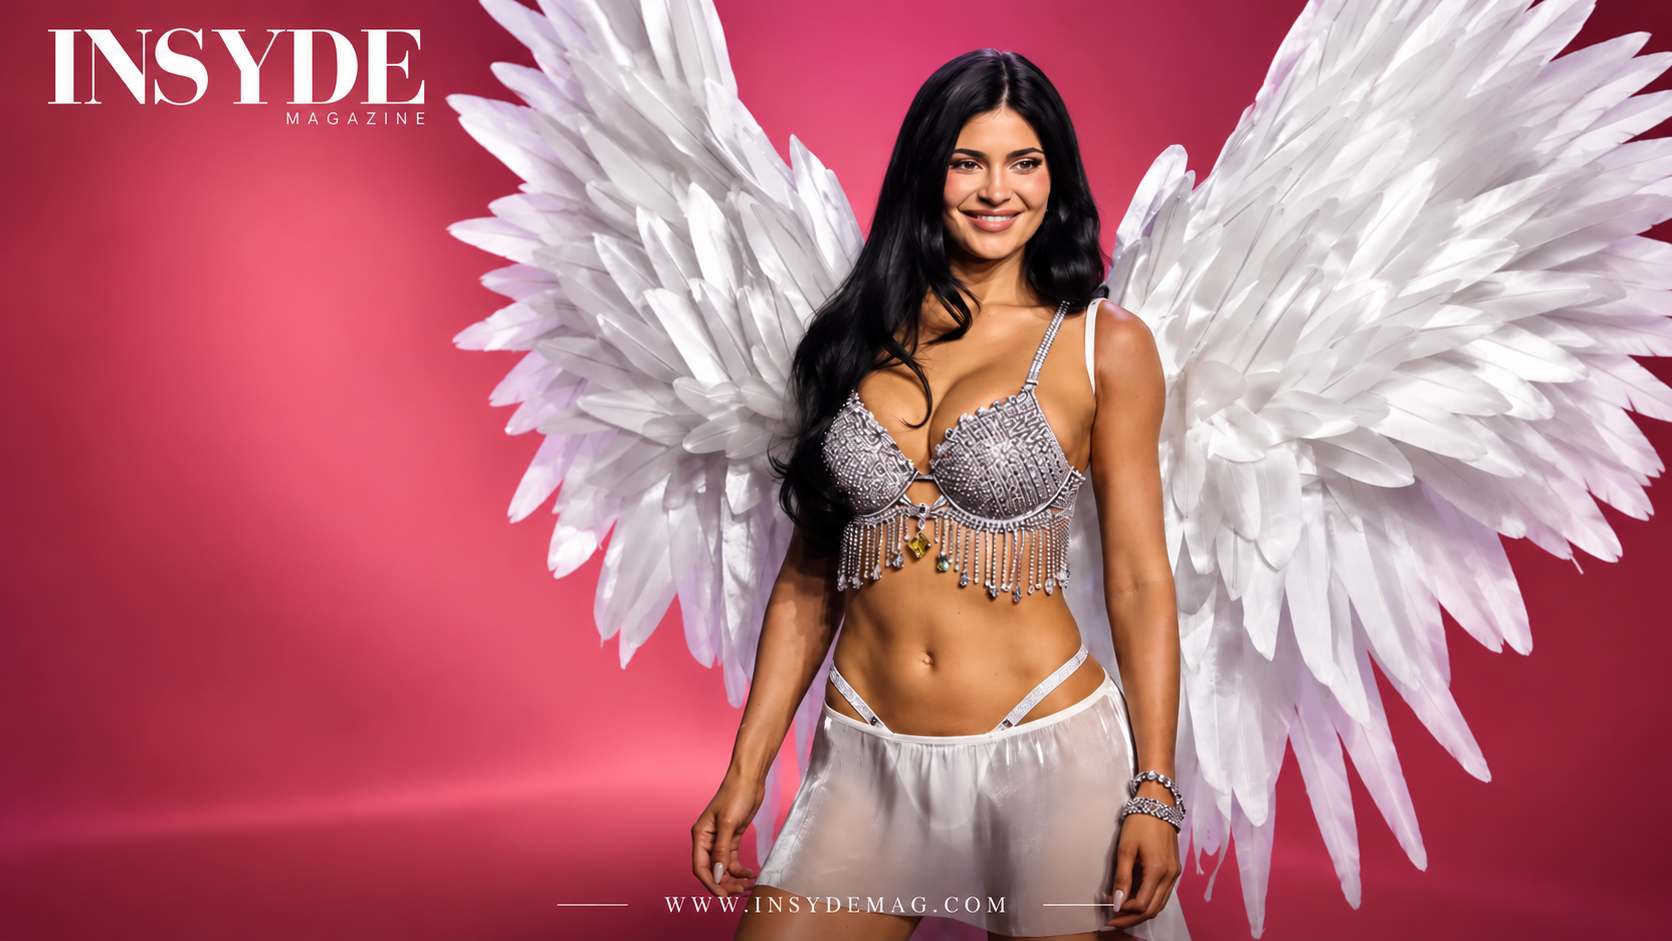
    On 18 October 2026, Victoria’s Secret brought one of fashion’s most recognisable spectacles back to the runway. At its Los Angeles fashion show, Kylie Jenner made her Victoria’s Secret runway debut wearing the brand’s latest Fantasy Bra—a creation developed in collaboration with New York-based high-jewellery house Jacob & Co. and assigned a reported value of US$50 million.

    The number is extraordinary. So is the object behind it.

    Set in 18-karat white and yellow gold, the creation features more than 4,400 natural diamonds, anchored by a 75.54-carat radiant-cut Fancy Vivid yellow diamond. Fifteen artisans spent more than 1,000 hours bringing the piece to life, assembling approximately 3,218 individually designed components into a structure intended to move with the body.

    According to Jacob & Co.’s official product description and reporting by Forbes, the design combines elaborate gemstone setting with engineering techniques more commonly associated with intricate mechanical objects than conventional lingerie.

    It is a creation designed to be seen, photographed and remembered. Yet the most interesting story is not simply how much it is worth. It is how two brands have turned the intersection of jewellery, fashion and celebrity into an object capable of commanding global attention.

    A DIAMOND AT THE CENTRE OF THE FANTASY

    The Fantasy Bra’s visual impact begins with its centrepiece: a 75.54-carat natural Fancy Vivid yellow diamond, graded VS2 by the Gemological Institute of America, or GIA, according to Jacob & Co.’s published specifications.

    The radiant cut combines the rectangular outline of an emerald-style cut with faceting designed to produce considerable brilliance. In a stone of this colour and scale, the effect is particularly striking. Rather than serving as a small accent, the yellow diamond becomes the focal point around which the entire composition is organised.

    Two round brilliant white diamonds, together weighing 11.85 carats, flank the centre stone. Beyond them, the design incorporates 91 large natural white diamonds, with individual stones ranging from 5.01 to 18.59 carats. Jacob & Co. identifies these stones as E–F in colour and VVS2–VS1 in clarity. The remaining diamond work fills the structure with additional brilliance and detail.

    The house’s published specifications list a combined diamond weight of approximately 1,373.39 carats. The stones are set in 18-karat white and yellow gold, with multiple diamond shapes and setting techniques used throughout the design.

    These details matter because exceptional jewellery is not defined by carat weight alone. Colour, clarity, cut, proportions, setting and the relationship between individual stones all influence the final effect. The challenge is to make thousands of elements read as one coherent design rather than a collection of unrelated gemstones.

    In the Fantasy Bra, the yellow centre stone establishes the visual hierarchy. The surrounding white diamonds intensify its contrast, while the gold framework gives the composition its structure.

    The result is less a conventional garment embellished with precious stones than a piece of high jewellery conceived around the form of lingerie.

    Source: Jacob & Co. — The Angel Fantasy Bra.

    3,218 COMPONENTS. MORE THAN 1,000 HOURS OF CRAFTSMANSHIP.

    The most revealing aspect of the Fantasy Bra may be the work that cannot be understood from a photograph.

    Jacob & Co. describes the creation as a structure comprising approximately 3,218 individually designed components. Fifteen artisans spent more than 1,000 hours assembling and setting the piece by hand, combining traditional jewellery-making methods with computer-aided design.

    The process began with an initial sketch, followed by a full-scale model made from chipboard. The team then developed a detailed digital model to refine the proportions, map the individual components and plan the construction.

    Each gold component was cast using the lost-wax method, a traditional process in which a wax model is encased in investment material and heated until the wax melts away, leaving a mould for molten metal. The resulting pieces were cleaned, refined and pre-polished before being assembled and set with diamonds.

    The engineering challenge was substantial. A centre stone weighing more than 75 carats requires a supporting structure capable of handling its mass. At the same time, the design could not behave like a rigid jewellery plate. It needed to follow the contours of the body and allow movement.

    The team therefore used different setting approaches for different parts of the piece. Prong settings expose more of a diamond to light, while bezel settings secure stones in areas subject to greater movement. Pavé settings fill the spaces between larger stones, creating a more continuous field of brilliance. Articulated sections allow parts of the gold structure to move in relation to one another.

    These are not merely decorative decisions. Every setting, connection and supporting element must balance the security of the gemstones with the overall appearance and wearability of the piece.

    The challenge becomes even more significant when the object is intended for a live runway presentation. It must photograph beautifully, withstand movement and sit correctly on the wearer, all while preserving the visual integrity of the design.

    As Forbes reported on 19 October 2026, the construction combined computer-aided design with traditional hand-finishing and assembly.

    The craftsmanship is what separates this object from a simple exercise in extravagance. The diamonds establish its visual impact; the engineering makes the design possible.

    WHEN PRECIOUS METAL BEHAVES LIKE FABRIC

    The Fantasy Bra draws inspiration from Jacob & Co.’s Rare Touch jewellery collection, which explores how precious metal can be shaped into articulated structures that move with the body.

    That idea is pushed further here. Instead of creating a conventional necklace, bracelet or rigid ornament, the house has developed a piece made entirely from precious metal and gemstones that is intended to function as lingerie.

    The distinction is important. Jewellery is usually designed to sit on the body, while clothing is designed to follow it. The Fantasy Bra must do both.

    Its gold framework has to support a substantial quantity of diamonds without becoming visually cumbersome. Its cups must follow the contours of the wearer. Its articulated elements must permit movement, while the settings must keep the stones secure.

    The design also had to be fitted to Jenner’s measurements, with adjustments made to ensure that the structure sat correctly on her body.

    In the official behind-the-scenes feature, Jacob Arabo, founder of Jacob & Co., emphasised that value alone was not enough. The creative priorities, he explained, were the diamonds, the light and the movement. Victoria’s Secret chief creative officer Adam Selman similarly stressed the importance of designing for the person wearing the piece.

    Their comments point to the central design tension: the Fantasy Bra must be spectacular without becoming a static display object.

    The finished creation weighs just under four pounds, according to Vogue. That is a remarkable weight for something intended to be worn on a moving body, and it underlines the unusual demands of the project.

    For Jacob & Co., the collaboration offers an opportunity to apply its high-jewellery expertise to a format where the technical challenges are immediately visible. For Victoria’s Secret, it transforms a familiar piece of lingerie into a showpiece built around exceptional materials and specialist craftsmanship.

    Sources: Victoria’s Secret — The Making of the Fantasy Bra and Vogue.

    THE RETURN OF A RUNWAY ICON

    The 2026 creation is also a revival of a tradition that has been part of Victoria’s Secret’s visual identity for three decades.

    The first Fantasy Bra appeared in 1996, when Claudia Schiffer wore the original design in a magazine advertisement. Over the following years, the concept became a signature expression of the brand’s extravagant runway aesthetic, with each edition built around precious stones, elaborate craftsmanship and a high-profile wearer.

    The tradition reached a new level of visibility in 2000, when Gisele Bündchen wore the Red Hot Fantasy Bra, valued at US$15 million. Other editions followed, each adding to the mythology surrounding the garment.

    The last Fantasy Bra before the current revival was worn by Elsa Hosk in 2018. That edition, created with Atelier Swarovski, was valued at approximately US$1 million.

    The return in 2026 therefore marks an eight-year gap between editions. It also arrives at a time when fashion shows are increasingly understood as entertainment properties as much as presentations of clothing.

    The Victoria’s Secret Fashion Show on 18 October 2026 returned to Los Angeles, with a seasonal concept spanning spring, summer, autumn and two winter segments, alongside a dedicated PINK presentation. The production brought together runway fashion, celebrity appearances and live musical performances.

    Within that wider production, the Fantasy Bra served as a focal point: a single creation with a long history, a recognisable name and a headline-making valuation.

    Its return is not simply a nostalgic gesture. It reintroduces an established brand signature in a format suited to contemporary fashion coverage, where a single image can become the defining visual of an entire event.

    The Fantasy Bra gives the show a clear centre of gravity. It is an object audiences can identify immediately, even if they know little about the rest of the collection.

    Source: Vogue — The history and return of the Fantasy Bra.

    WHY KYLIE JENNER WAS THE RIGHT CHOICE

    The selection of Kylie Jenner was central to the story.

    Jenner’s public profile extends across entertainment, fashion, beauty and social media. As a beauty entrepreneur with a substantial international audience, she reaches consumers who may not ordinarily follow fine-jewellery craftsmanship or the history of lingerie runway shows.

    Her appearance therefore connected two different kinds of visibility: the specialist world of high jewellery and the broader culture of celebrity-led fashion.

    In its coverage of the show, Vogue reported that Selman described Jenner as a “cultural powerhouse”, emphasising her influence beyond any single industry. The choice was consistent with the show’s positioning as entertainment as well as fashion.

    That distinction matters in an era when the reach of a runway moment is not limited to the people in the room. Photographs, short-form video, backstage content, interviews and social commentary extend the life of a show long after the final model leaves the catwalk.

    A recognisable celebrity can help translate a highly specialised object into a story with wider appeal. Audiences may initially encounter the Fantasy Bra because of Jenner, then become curious about the diamonds, the designer, the construction or the reported price.

    The wearer is therefore more than a model displaying a garment. She becomes the link between the craftsmanship and the culture surrounding it.

    This does not mean celebrity alone creates luxury. The object still needs a compelling design, credible craftsmanship and a story that rewards attention. But celebrity can give those qualities a much larger stage.

    For Victoria’s Secret, Jenner’s debut placed the Fantasy Bra at the intersection of fashion, beauty and entertainment. For Jacob & Co., it offered a high-profile presentation of its work to an audience beyond traditional jewellery collectors.

    The collaboration demonstrates how luxury objects can travel across cultural categories without losing their material identity.

    Source: Vogue — Kylie Jenner’s Fantasy Bra debut.

    WHAT DOES A US$50 MILLION FANTASY BRA ACTUALLY MEAN?

    The reported valuation is the headline figure, but it deserves careful interpretation.

    Jacob & Co. describes the 2026 Fantasy Bra as the most valuable edition ever created, and fashion reporting has placed its value at US$50 million. That figure should be understood as the reported valuation of an extraordinary, bespoke creation—not as evidence of a completed sale or a guaranteed resale price.

    There is no publicly disclosed transaction establishing that a buyer has paid US$50 million for the piece. Nor does the reported figure, by itself, reveal how the valuation was calculated.

    The cost of exceptional diamonds is one part of the story. The central yellow diamond, the additional white diamonds, the precious metal, the specialised labour and the complexity of the construction all contribute to the creation’s material and technical significance.

    But a one-of-a-kind object associated with major brands also occupies a different category from a conventional retail product. Its identity is shaped by the circumstances of its creation, its place in fashion history and its role within a major public event.

    That makes its valuation difficult to compare directly with the price of a commercially available piece of jewellery.

    The Fantasy Bra is not simply a product with a price tag. It is a bespoke showpiece designed to embody the ambitions of two brands. Its value is communicated through the combination of gemstones, craftsmanship, exclusivity and cultural visibility.

    That does not mean its reported valuation should be treated as a measure of its financial return. Without a public breakdown of the valuation methodology, a disclosed sale or independently verified resale evidence, it would be misleading to claim that the piece could necessarily be sold for the same amount.

    The US$50 million figure is an extraordinary headline. The more useful question is what that headline enables the brands to communicate.

    THE BUSINESS OF LUXURY SPECTACLE

    For Victoria’s Secret, the Fantasy Bra is a concentrated expression of the brand’s visual identity. It brings glamour, excess and craftsmanship together in a single object that can anchor a fashion show and generate coverage well beyond the runway.

    For Jacob & Co., the collaboration showcases the house’s ability to work with exceptional gemstones and complex structures while introducing its jewellery-making expertise to a wider fashion and entertainment audience.

    The partnership creates value through a combination of complementary strengths. Victoria’s Secret provides the runway, the audience and a recognisable fashion tradition. Jacob & Co. provides the gemstones, the technical expertise and the high-jewellery proposition. Jenner’s appearance adds a celebrity narrative that can travel across multiple media platforms.

    Together, these elements create a story that is larger than any one component.

    This is the commercial logic of luxury spectacle: an object can serve as a product of craftsmanship and a communications asset at the same time. Its role is not necessarily to generate direct sales in the way a conventional retail collection would. It can also reinforce brand identity, attract attention, stimulate conversation and give audiences a memorable reason to engage with a show.

    The Fantasy Bra is especially suited to that purpose because its headline figure is instantly understandable. A US$50 million valuation communicates extravagance in a single line. The diamond count and production hours then give the story additional substance.

    But attention should not be confused with measurable commercial success. Neither brand has publicly disclosed figures that would allow an independent calculation of the collaboration’s return on investment, its effect on product sales or the precise value of the media coverage it generated.

    The defensible conclusion is narrower, but still significant: the Fantasy Bra provides both brands with an unusually distinctive expression of their identities, supported by a story that connects craftsmanship, celebrity and fashion history.

    In luxury marketing, not every creation needs to function as a conventional product. Some are designed to demonstrate what a brand can do when commercial constraints give way to creative ambition.

    The Fantasy Bra belongs to that category.

    WHEN EXCESS BECOMES AN ART FORM

    Luxury has always maintained a relationship with excess. Exceptional materials, meticulous workmanship and limited availability distinguish many of its most prestigious creations from ordinary consumer goods.

    Yet excess alone is rarely enough to make an object compelling. An extraordinary quantity of diamonds can establish a sense of scale, but scale does not automatically produce design. The more interesting challenge is how those materials are organised, how the object functions and what it communicates.

    The Fantasy Bra brings those questions together.

    Its gemstones create the immediate visual drama. Its articulated construction gives the design a technical dimension. Its connection to Victoria’s Secret’s runway history supplies context, while Jenner’s debut brings the piece into contemporary celebrity culture.

    Each layer strengthens the others. Without the craftsmanship, the object would risk becoming a price-led spectacle. Without the runway, its technical achievement might reach a more specialised audience. Without the celebrity moment, its cultural reach could be more limited.

    The result is a creation that operates across several worlds at once: jewellery, fashion, entertainment and brand storytelling.

    That is what makes the Fantasy Bra relevant beyond its extraordinary valuation. It illustrates how luxury houses and fashion brands can use a single object to communicate both material excellence and cultural ambition.

    THE FINAL WORD

    The $50 million Fantasy Bra is not merely a story about diamonds, lingerie or a celebrity runway debut. It is a study in how luxury turns craftsmanship into spectacle.

    Jacob & Co. brought its expertise in exceptional gemstones and intricate jewellery construction. Victoria’s Secret revived a defining element of its runway history. Kylie Jenner gave the creation a high-profile introduction to a global audience.

    The result is a piece built from thousands of precious components, shaped to move with the body and presented as the centrepiece of a major fashion event.

    Its reported valuation may be what first captures attention. But the more enduring story lies in the ambition behind it: the effort to make precious materials behave like fabric, to turn a familiar garment into high jewellery and to create an object that can carry the identities of two brands at once.

    In luxury, price can make a headline. Craftsmanship gives that headline substance. Culture gives it reach.

    And with the return of the Fantasy Bra, Victoria’s Secret and Jacob & Co. have brought all three onto the runway.

    INSYDE Magazine is a luxury, fashion, culture and entertainment publication exploring the people, brands and ideas shaping the world of modern luxury. From exceptional craftsmanship and high jewellery to influential personalities and emerging cultural movements, INSYDE offers a distinctive perspective on the stories defining what comes next.

    INSYDE — No. 1 Luxury Magazine in Bengaluru.

  • THE LUXURY EMPIRE LOSING ITS CHARM?

    THE LUXURY EMPIRE LOSING ITS CHARM?

    Inside the Global Slowdown Reshaping the World’s Most Coveted Brands

    From weakening fashion sales and rising consumer selectivity to the shifting economics of exclusivity, the world’s luxury giants are confronting a difficult question: what happens when the desire to own luxury begins to fade?

    INSYDE Magazine | Luxury & Business |


    Luxury has always sold a fantasy.

    A handbag is never just a handbag. A watch is never simply a mechanism for measuring time. A hotel suite, a couture gown or a piece of fine jewellery promises something beyond its physical form: status, craftsmanship, heritage, belonging and the rare feeling of possessing something exceptional.

    For decades, the world’s most powerful luxury houses have built extraordinary businesses around that promise. Their names became cultural shorthand for success. Their boutiques became destinations. Their products became objects of desire, often commanding prices far removed from the cost of the materials used to make them.

    But in October 2026, the global luxury industry finds itself confronting a less glamorous reality.

    Growth has become harder to secure. Some of the world’s largest fashion businesses are struggling to regain momentum. Consumer behaviour is changing, demand is shifting between regions, and the industry’s most influential companies are facing renewed scrutiny over their ability to justify premium prices.

    The numbers tell a complicated story. This is not the collapse of luxury, nor the disappearance of wealthy consumers. It is a market undergoing a reset — one that is exposing the differences between brands that continue to inspire desire and those finding it increasingly difficult to sustain it.

    At the centre of the debate is a question that goes beyond quarterly earnings.

    Has luxury become so expensive, so ubiquitous and so dependent on its own prestige that parts of the industry are beginning to lose the very charm that made them desirable?

    THE NUMBERS BEHIND THE GLAMOUR

    The global luxury economy remains enormous. Yet its scale can obscure the pressure emerging within individual categories.

    According to Bain & Company and Altagamma’s June 2026 luxury market update, worldwide luxury spending reached approximately €1.443 trillion in 2025. This figure covers a broad range of luxury markets, including personal goods and experiences; it should not be confused with spending on designer fashion and accessories alone.

    The personal luxury goods market — covering categories such as fashion, leather goods, jewellery, watches and beauty — was estimated at approximately €358 billion in 2025. At current exchange rates, that represented a 2% decline from 2024, although the market grew by 1% at constant exchange rates.

    For 2026, Bain and Altagamma’s base-case forecast anticipates growth of 2% to 4%, potentially bringing personal luxury goods spending to between €365 billion and €373 billion.

    That is a forecast, not a confirmed year-end result. It suggests that the market could return to modest growth, but it does not imply that every luxury company will benefit equally.

    The distinction is crucial. An industry can remain worth hundreds of billions of euros while major brands experience falling sales, pressure on profitability and increasingly selective consumers.

    The latest results from LVMH, the luxury group behind Louis Vuitton, Dior, Tiffany & Co., Bulgari and other major names, illustrate the challenge.

    On 12 October 2026, LVMH reported €18.5 billion in third-quarter revenue, with organic revenue growth of just 1% compared with the same period a year earlier. For the first nine months of 2026, group revenue reached €57.1 billion, representing 2% organic growth.

    The more revealing figure came from its core fashion and leather goods division. Organic revenue in that business fell 5% in the third quarter. Across the first nine months of 2026, the division’s reported revenue declined 4% year on year, while organic revenue fell 2%.

    These are not interchangeable measurements: reported revenue reflects factors including currency movements, while organic growth attempts to assess underlying business performance.

    Nevertheless, the direction is clear. One of the world’s most influential luxury groups is finding that its largest fashion businesses cannot rely on the industry’s historic momentum.

    The company’s results also showed that performance differed by region. LVMH described a less buoyant environment in China, while the United States, Europe and Japan recorded growth during the quarter.

    The lesson is not that luxury has stopped selling. It is that the industry can no longer assume that prestige alone will guarantee growth.

    Source: LVMH, third-quarter 2026 results.

    WHEN EXCLUSIVITY BECOMES A PRICE TAG

    Luxury has always depended on pricing power. A product that commands a premium can signal rarity, superior craftsmanship, design excellence and the authority of a recognised house.

    But pricing power is not limitless.

    For years, price increases have been an important part of the commercial strategies pursued across luxury. When demand is strong and customers remain willing to pay, raising prices can support revenue and reinforce a brand’s positioning.

    The difficulty emerges when the price rises faster than the customer’s perception of value.

    A customer purchasing a luxury handbag is not paying only for leather, stitching or hardware. They are paying for the design, the name, the service, the experience and the emotional satisfaction attached to the purchase.

    When prices rise substantially, the brand must continue to justify the entire proposition.

    Is the craftsmanship exceptional? Is the design distinctive? Does the product feel special enough to deserve its price? Will it remain desirable beyond the current season? Does the experience justify the expense?

    For some consumers, the answer remains an emphatic yes. For others, the calculation is becoming more difficult.

    This is particularly relevant for aspirational buyers: consumers who can afford selected luxury products but cannot treat every purchase as financially insignificant.

    For them, a handbag, watch or pair of shoes is a considered decision. When the price increases, they may postpone the purchase, choose a pre-owned alternative or redirect their money towards travel, dining and other experiences.

    Luxury brands therefore face a delicate balancing act. Lowering prices indiscriminately could undermine exclusivity, but continuing to raise them without strengthening perceived value risks making the customer feel that the brand is asking for more while offering less in return.

    The problem is not the existence of high prices. Luxury is supposed to be expensive.

    The problem arises when expensive becomes the most convincing thing a product has to offer.

    THE CUSTOMER LUXURY CANNOT AFFORD TO FORGET

    The wealthiest customers remain important to luxury. They support high jewellery, couture, rare watches, bespoke services and limited-edition creations.

    But the global luxury market was never built exclusively on the spending of billionaires.

    Aspirational consumers have helped turn luxury houses into cultural institutions. They buy fragrances, beauty products, accessories and entry-level leather goods. They follow fashion campaigns, recognise creative directors, discuss collections and introduce brands to new audiences.

    Their individual spending may be lower, but their collective influence is significant.

    That is why the shrinking or weakening of this customer base deserves attention.

    In June 2026, Reuters reported on Bain’s estimate that the luxury industry had lost approximately 70 million consumers since 2022. The figure reflects a reported industry estimate; it should not be interpreted as proof that every one of those consumers has permanently abandoned luxury.

    It does, however, highlight the challenge facing brands that have increasingly concentrated on their highest-spending clients.

    A company can become more exclusive in its advertising while simultaneously reducing the number of people who feel connected to it.

    That strategy may improve the economics of individual transactions in the short term, but it can also narrow the audience that sustains cultural relevance over time.

    Younger consumers, in particular, encounter luxury differently from previous generations. They can compare prices, research craftsmanship, follow independent designers, browse resale platforms and question a brand’s claims before entering a boutique.

    They are not necessarily rejecting luxury. They are becoming more selective about what deserves their money.

    For the industry, the challenge is to preserve exclusivity without allowing it to become indifference.

    CHINA AND THE FRAGILE GEOGRAPHY OF LUXURY

    Luxury is a global business, but its fortunes have long been influenced by a handful of powerful consumer markets.

    China became one of the industry’s most important growth engines, supported by rising wealth, international travel and strong demand for European fashion, jewellery and watches.

    That made the Chinese consumer central to the expansion strategies of many international luxury houses.

    But demand does not move in a straight line.

    LVMH’s October 2026 results pointed to a less buoyant environment in China, helping explain the pressure on its fashion and leather goods division. The company reported growth in the United States, Europe and Japan, but that strength did not remove the overall weakness in its core fashion business.

    The wider significance is that global luxury brands must manage different economic conditions, consumer expectations and cultural dynamics simultaneously.

    When demand weakens in one major region, companies with concentrated exposure can face immediate pressure. When several markets become less predictable at once, the challenge becomes more complicated.

    This is not an argument for abandoning China or replacing it with another single growth engine. It is an argument for a more balanced global strategy.

    The United States can offer opportunities, but it is not a guaranteed substitute for every lost sale elsewhere. Europe remains important, particularly for local consumers and international visitors. Japan has its own demand patterns, while other Asian markets continue to evolve.

    The strongest brands will be those that understand their customers market by market rather than assuming that a global reputation automatically translates into uniform demand.

    In luxury, geography is no longer simply a question of where a brand opens its next boutique. It is a question of where desire is growing, where it is weakening and why.

    NOT EVERY LUXURY EMPIRE IS LOSING ITS CHARM

    A slowdown story becomes misleading when it treats every category as though it were experiencing the same problems.

    Luxury fashion, jewellery, watches, beauty, hospitality and other premium experiences operate with different economics. Their customers buy for different reasons, and their products follow different purchase cycles.

    Richemont provides an important counterexample.

    The Swiss group, whose jewellery maisons include Cartier, Van Cleef & Arpels, Buccellati and Vhernier, reported €6.329 billion in sales for the quarter ended 30 June 2026, an increase of 20% at constant exchange rates and 17% at actual exchange rates.

    Its jewellery maisons recorded a 24% increase at constant exchange rates, while its specialist watchmakers grew by 8%.

    The figures cover Richemont’s first fiscal quarter, which ended in June. They are not directly comparable with LVMH’s July–September third-quarter results because the reporting periods and business portfolios differ.

    Even with that qualification, Richemont’s performance demonstrates an essential point: demand remains strong in parts of luxury, particularly where products continue to attract customers through recognisable design, craftsmanship and enduring desirability.

    Jewellery also serves different purposes from seasonal fashion. It can mark significant life events, function as a gift, become a collectible or be passed between generations. Established jewellery houses have built long histories around signature designs and a distinctive visual language.

    That does not make jewellery immune to economic pressure. Nor does one strong quarter guarantee future growth.

    It does show why the industry should not be described as a single market moving in one direction.

    The more useful question is which brands and categories are sustaining their appeal — and what they are doing differently.

    Source: Richemont, first-quarter results for the period ended 30 June 2026.

    FROM OWNING LUXURY TO EXPERIENCING IT

    A different idea of luxury is gaining ground: one in which the most desirable purchase is not necessarily an object.

    High-end hospitality, fine dining, private travel, wellness retreats and cultural experiences offer something physical products cannot always replicate — a memory, a sense of access, personal attention or time spent outside ordinary life.

    Bain and Altagamma’s June 2026 update identifies experiences as an area of relative strength, with luxury experiences such as hospitality and restaurants, alongside selected high-value assets, expected to grow by around 4%.

    That forecast should be read as an industry outlook, not a final result for every experience-led business.

    Nevertheless, the direction is important.

    A handbag can be photographed and compared. A watch can be researched on the secondary market. But a private journey, an exceptional meal or a carefully designed hospitality experience depends on the quality of its execution, the people involved and the atmosphere created.

    For some consumers, these experiences are becoming a more compelling use of discretionary spending than another recognisable product.

    This does not mean that physical luxury is disappearing. Fashion, jewellery and watches remain central to the industry. Instead, the definition of luxury is expanding, and brands must decide how they fit into a consumer’s wider idea of a desirable life.

    The opportunity extends beyond hotels and restaurants. A fashion house can build a cultural world around its products. A jewellery brand can deepen its connection to craftsmanship and heritage. A luxury retailer can turn a store visit into a personalised experience rather than a simple transaction.

    The brands that understand the emotional value of an experience may discover new ways to sustain the desirability of their products.

    Luxury has always sold more than objects. The market is increasingly asking brands to prove it.

    Source: Bain & Company and Altagamma’s 2026 market update.

    THE SECOND-HAND MARKET IS CHANGING THE CONVERSATION

    The rise of pre-owned luxury has introduced another variable into the industry’s relationship with value.

    The secondary market gives consumers access to established brands at different price points. It also allows collectors to buy, sell and trade products beyond their original retail environment.

    For a buyer considering a new luxury item, the decision is no longer limited to comparing it with other new products. The buyer can examine pre-owned alternatives, investigate resale prices and consider whether the purchase is likely to retain its appeal.

    Bain and Altagamma’s 2026 research found that around half of luxury shoppers consult the second-hand market before buying new, while approximately half already use AI during their purchase journey.

    These findings suggest that technology and resale are no longer peripheral to luxury shopping. They are becoming part of how consumers discover products, compare options and evaluate value.

    For brands, the implications are mixed.

    A strong secondary market can reinforce a product’s reputation for longevity, desirability and collectability. It can also introduce new consumers to a brand who may later purchase directly from the company.

    But resale makes it easier for shoppers to question the relationship between a product’s original price and its perceived value. A consumer may decide that a pre-owned piece from a more prestigious house offers a better proposition than a new product from a less established competitor.

    That places greater importance on quality, durability, authenticity and timeless design.

    Luxury houses cannot control every transaction in the secondary market, but they can influence the qualities that make their products desirable long after the first sale.

    The real test is whether a product remains compelling when the customer has more information, more alternatives and fewer reasons to buy impulsively.

    Source: Bain & Company and Altagamma, 2026 luxury market research.

    INDIA: A PROMISING MARKET WITH REAL CONSTRAINTS

    India presents an important opportunity for global luxury, but it should not be treated as an automatic solution to the industry’s challenges elsewhere.

    The country’s expanding affluent population, entrepreneurial wealth and growing appetite for premium products have attracted international brands. Yet translating that interest into a mature luxury market requires more than consumer aspiration.

    A March 2026 Reuters report on India’s luxury retail-space shortage highlighted a major constraint: the limited availability of high-quality luxury retail destinations.

    The report described a market in which global brands were competing for a relatively small number of suitable locations, while new retail developments would take time to deliver.

    This creates a structural challenge. A growing customer base cannot be fully served without the right stores, trained staff, reliable service, appropriate locations and the broader retail infrastructure that supports a premium shopping experience.

    Import duties and differences in pricing can also influence where affluent Indian consumers choose to shop.

    For international luxury houses, India therefore represents a long-term strategic opportunity rather than an immediate substitute for weaker demand elsewhere.

    The opportunity is also relevant to Indian luxury businesses. Brands that understand local craftsmanship, cultural heritage and changing consumer expectations can develop propositions that are distinctive rather than simply imported.

    But growth will depend on execution. Strong demand must translate into repeat purchases, trusted customer relationships and retail experiences that meet the expectations attached to a premium price.

    India may become a more significant force in the global luxury landscape. Its potential, however, should be assessed through market evidence rather than optimism alone.

    THE NEXT ERA OF LUXURY WILL BE WON ON VALUE

    The industry’s next chapter will not be decided by price increases alone.

    Luxury houses still possess formidable advantages: heritage, craftsmanship, design, distribution, cultural influence and relationships with wealthy customers. The current slowdown does not erase those strengths.

    It does make the quality of their execution more important.

    First, brands must make their prices mean something. A premium must be supported by product quality, distinctive design, materials, service and a credible story. Price alone cannot create enduring desire.

    Second, customer relationships must extend beyond the wealthiest buyers. High-spending clients remain essential, but younger and aspirational consumers represent a potential future audience. Brands must find ways to remain relevant without abandoning the exclusivity that defines them.

    Third, creativity must do more than generate attention. Campaigns, celebrity partnerships and cultural visibility can make a brand famous, but fame does not automatically create loyalty. Products must still be desirable when the campaign ends.

    Fourth, companies must understand the new shopping journey. Consumers increasingly compare products, explore resale platforms and use digital tools before making decisions. A brand’s proposition must remain convincing beyond its own advertising and retail environment.

    Finally, luxury businesses must understand what customers are actually buying. Sometimes it is craftsmanship. Sometimes it is status, rarity, personal expression or access to a particular world. The strongest brands understand these motivations and deliver them consistently.

    The winners will not necessarily be the brands that become the most expensive. They may be the brands that give consumers the clearest reason to believe their products are exceptional.

    THE LAST WORD

    Luxury is not dead. But the old assumption that prestige can sustain growth indefinitely is being tested.

    The global market remains vast, and the latest industry forecasts point towards modest growth in personal luxury goods during 2026. Yet the recovery is uneven. LVMH’s fashion and leather goods division is under pressure, while Richemont’s jewellery maisons have reported strong growth. Experiences and the secondary market are reshaping how consumers think about luxury, and brands are being forced to compete for attention in a more informed and selective marketplace.

    Together, these developments point towards a more demanding luxury economy — one in which recognition alone may not be enough, price increases require stronger justification, and loyalty must be earned rather than assumed.

    For decades, luxury sold the promise of something beyond the ordinary. The next era will depend on whether that promise still feels extraordinary.

    Because the greatest threat to a luxury empire is not simply a weaker quarter or a slower market.

    It is the moment a customer looks at something once considered irresistible — and decides they can live without it.


    INSYDE MAGAZINE

    Luxury. Culture. The People Shaping What Comes Next.
    No.1 Luxury Magazine In Bengaluru
    www.insydemag.com

  • BEAUTY. BILLIONS. & INFLUENCE.

    BEAUTY. BILLIONS. & INFLUENCE.

    How celebrity founders turned beauty, fame and influence into commercial power.

    BY INSYDE | BEAUTY & BUSINESS

    There was a time when a celebrity’s relationship with beauty was simple. A famous face appeared in a campaign, a name went on a bottle, and a brand paid for the privilege of borrowing a little of that person’s desirability.

    Today, some celebrities are doing something considerably more ambitious.

    They are building the brands themselves.

    Rihanna helped turn Fenty Beauty into a global cosmetics business. Selena Gomez built Rare Beauty around a distinctive philosophy of self-expression. Kylie Jenner transformed social-media attention into a cosmetics company. Hailey Bieber developed Rhode into an acquisition target for one of the beauty industry’s major players. Huda Kattan turned beauty expertise and an online audience into an international brand.

    These are not simply celebrity endorsements. They are businesses with products, distribution networks, commercial strategies and, in some cases, billion-dollar valuations or acquisition deals.

    The distinction matters.

    In October 2026, Fortune, reporting on Traackr’s Creator Advantage 2026 research, highlighted how celebrity-founded companies had become powerful participants in the beauty economy. Five of the ten leading US beauty brands ranked by creator-marketing performance in 2025 were celebrity-founded, including Kylie Cosmetics, Rare Beauty, Rhode, R.E.M. Beauty and Huda Beauty.

    That is a measure of marketing performance, not a ranking of revenue or profitability. But it reveals something important about the modern consumer market: influence is no longer merely an advertising tool. In the right hands, it can become a competitive advantage.

    The financial results make the story even more interesting.

    According to Reuters’ reporting on Fenty Beauty, the brand generated approximately $450 million in net sales in 2024. Rhode recorded $212 million in net sales during the twelve months ended March 31, 2025, before its acquisition by e.l.f. Beauty. Rare Beauty has also been associated with a reported valuation estimate of approximately $2.7 billion in 2026.

    These figures measure different things. Sales are not valuations, acquisition prices are not guaranteed cash payouts, and the value of a company is not the same as its founder’s personal fortune.

    But together, they point towards a larger shift.

    Celebrity beauty is no longer simply about putting a famous face on a product. It is about turning identity, cultural relevance, product development and direct access to consumers into businesses with lasting value.

    The question is no longer whether a celebrity can sell a lipstick.

    It is whether that celebrity can build a beauty company that people continue to buy from long after the initial fascination fades.

    01 — FENTY BEAUTY: WHEN INCLUSIVITY BECAME A BUSINESS STRATEGY

    When Rihanna launched Fenty Beauty in September 2017, its initial foundation range of 40 shades made inclusivity a defining part of its identity.

    The significance was not that no beauty brand had previously offered a wide shade range. It was that Fenty brought the conversation into the centre of a highly visible global launch, making the experiences of consumers who struggled to find suitable foundation difficult for the wider industry to ignore.

    Its proposition was clear: more consumers should be able to find products that work for them.

    Rihanna’s cultural reach gave the launch extraordinary visibility, while the brand’s partnership with LVMH’s Kendo division provided the infrastructure of an established beauty business.

    The financial figures demonstrate the scale that followed.

    Reuters reported in October 2025 that Fenty Beauty generated approximately $450 million in net sales in 2024. Sources cited in the same report estimated its valuation at between $1 billion and $2 billion. That valuation was an estimate, not a publicly disclosed transaction price.

    The distinction matters. Sales describe the revenue generated by a business over a period; valuation estimates what that business might be worth.

    Fenty’s wider influence is perhaps more revealing than either number. Its positioning helped make inclusive shade ranges a much more prominent part of the beauty industry’s commercial conversation.

    The business lesson is straightforward. Rihanna’s fame helped Fenty attract attention, but the company needed a product proposition that consumers could understand and purchase.

    THE INSYDE OBSERVATION: Influence becomes more powerful when it is attached to a proposition the market has a reason to believe in.

    02 — RARE BEAUTY: THE POWER OF A POINT OF VIEW

    Selena Gomez launched Rare Beauty in 2020 with an identity that extended beyond the products themselves.

    The brand’s messaging around self-expression and a less perfection-driven understanding of beauty gave it a recognisable position in a crowded market. Its products, communications and social-impact commitments helped establish an identity that consumers could connect with beyond the founder’s celebrity.

    That distinction matters in beauty, where packaging, product formats and trends can be replicated quickly.

    A clear point of view gives a brand something more durable to build around.

    Rare Beauty has become a significant participant in creator-led beauty. Its position among the leading brands in Traackr’s 2026 creator-marketing analysis demonstrates the scale of its digital and cultural relevance.

    Financially, the company has also attracted substantial private-market estimates. Fortune’s October 2026 analysis reported an estimated valuation of approximately $2.7 billion. This should be understood as a reported estimate, not a confirmed transaction price or an independently disclosed current valuation.

    It would be misleading to equate that figure with Gomez’s personal wealth. A company’s value belongs to the business and its shareholders; the founder’s financial position depends on ownership and other assets.

    Rare Beauty’s challenge is to maintain its identity while growing distribution, introducing new products and sustaining customer loyalty.

    The brand’s success suggests that a celebrity-led company can offer more than a famous face. It can create a coherent perspective on beauty that helps consumers understand what makes it different.

    THE INSYDE OBSERVATION: A recognisable philosophy can become a commercial asset when it is supported by products consumers want to use.

    03 — KYLIE COSMETICS: FROM SOCIAL-MEDIA ATTENTION TO CORPORATE SCALE

    Kylie Jenner’s cosmetics business began with one of the most recognisable categories in beauty: lip products.

    Kylie Lip Kits launched in 2015, drawing on Jenner’s public image and the attention surrounding her makeup looks. The products gave an existing audience something tangible to purchase.

    The model was powerful because the launch did not have to build awareness from zero. Jenner already had an audience, a recognisable aesthetic and a direct channel through which to communicate with potential customers.

    The business subsequently expanded beyond lip kits. In 2019, Coty acquired a 51% stake in the company for $600 million, implying an approximate $1.2 billion valuation at the time. This was a historical transaction, not a verified current valuation.

    Coty’s subsequent reporting offers a more recent view of the brand. In March 2025, the company said Kylie Cosmetics had grown 1.5 times over the preceding two years. The brand has continued to operate within Coty’s prestige beauty portfolio.

    Coty does not disclose a comparable standalone current valuation for Kylie Cosmetics in the reporting used for this article. Nor can the company’s valuation or sales be used as a direct measure of Jenner’s personal wealth.

    The corporate partnership changed the nature of the business. Kylie Cosmetics became part of a larger beauty portfolio with access to established distribution, marketing and operational capabilities.

    That brings advantages, but it also means the founder’s role and ownership must be distinguished from the company’s overall performance.

    Kylie Cosmetics demonstrates how a celebrity’s audience can accelerate a product launch. Its longer-term commercial value depends on whether the brand can keep its products relevant after the initial excitement.

    THE INSYDE OBSERVATION: An audience can give a business its first customers. It cannot guarantee its next decade of growth.

    04 — RHODE: THE VALUE OF A CLEAR AESTHETIC

    Hailey Bieber’s Rhode entered the beauty market with a focused skincare proposition, restrained packaging and an immediately recognisable visual identity.

    Rather than launching with an enormous assortment, Rhode concentrated on skin-focused products and an aesthetic that translated naturally into social content. Its presentation made products recognisable in photographs and routines easy to communicate.

    The brand’s commercial trajectory culminated in a major transaction.

    In May 2025, e.l.f. Beauty announced an agreement to acquire Rhode for $800 million at closing, plus up to $200 million in potential earn-out payments. The acquisition closed on August 5, 2025.

    Rhode had generated $212 million in net sales in the twelve months ended March 31, 2025, according to e.l.f. Beauty’s acquisition announcement.

    The maximum announced deal value was therefore $1 billion, not a guaranteed $1 billion cash payment to Bieber. The transaction involved cash, shares and potential performance-linked consideration.

    In its fiscal 2026 annual filing, e.l.f. Beauty recorded total acquisition consideration of approximately $897.5 million, including the estimated value of potential earn-out consideration at that time. The filing also reported that Rhode contributed $293.5 million in net sales to e.l.f.’s consolidated results between the acquisition date and March 31, 2026. This latter figure covers a different reporting period and should not be confused with Rhode’s standalone sales before the acquisition.

    The details can be verified in e.l.f. Beauty’s fiscal 2026 SEC filing.

    The transaction demonstrates why established beauty companies pay attention to fast-growing independent brands. An acquirer can bring distribution, retail relationships and international scale to a company that has already demonstrated consumer demand.

    After an acquisition, the challenge changes. A brand must preserve the qualities that made it distinctive while expanding its reach and operating within a larger corporate structure.

    Rhode’s story is not simply about a celebrity creating a successful skincare line. It is about a relatively young company developing enough commercial value to attract a major strategic buyer.

    THE INSYDE OBSERVATION: A focused product range and coherent aesthetic can be commercially powerful when they are supported by genuine demand and operational execution.

    05 — HUDA BEAUTY: WHEN BEAUTY EXPERTISE BECOMES AN EMPIRE

    Huda Kattan’s path into beauty began with expertise and content rather than a traditional entertainment career.

    Through beauty tutorials and product knowledge, she built an audience interested in makeup itself. Huda Beauty emerged from that relationship, launching with false eyelashes in 2013 before expanding into a wider cosmetics business.

    The distinction is important. Kattan was not simply placing her name on a product. Her existing connection with beauty consumers helped establish the company’s initial credibility.

    But turning an audience into a global brand required more than content. It required product development, manufacturing, distribution, inventory management and the ability to sell consistently across markets.

    Huda Beauty became a significant name in the international cosmetics market. It also appeared among the leading brands in Traackr’s creator-marketing analysis reported by Fortune in October 2026.

    Its financial history, however, requires careful treatment. Historical reports have associated the company with a valuation of around $1 billion in 2017, but that figure should not be presented as a verified current valuation. A sufficiently reliable, comparable standalone 2026 revenue or valuation figure has not been established for this article.

    That limitation should not be filled with an unsupported estimate.

    Huda Beauty remains an important case study because it shows how a founder can move from content creation into a product business with an identity that extends beyond the content that first attracted consumers.

    It also highlights a broader feature of celebrity beauty: not every successful founder begins as a film star or musician. In some cases, beauty expertise and an audience built around a specific category can be the starting point.

    THE INSYDE OBSERVATION: Fame is one route into beauty. Credibility built around the category itself can be another.

    06 — THE NUMBERS BEHIND THE GLOW

    The financial evidence behind these five brands is significant, but the figures describe different things.

    Fenty Beauty — Rihanna

    Approximately $450 million in reported net sales in 2024, alongside a $1–2 billion valuation estimate reported in 2025.

    Rare Beauty — Selena Gomez

    An estimated valuation of approximately $2.7 billion reported in October 2026.

    Kylie Cosmetics — Kylie Jenner

    An implied valuation of approximately $1.2 billion when Coty acquired its 51% stake in 2019.

    Rhode — Hailey Bieber

    $212 million in net sales for the twelve months ended March 31, 2025, followed by acquisition consideration recorded at approximately $897.5 million in e.l.f. Beauty’s fiscal 2026 filing.

    Huda Beauty — Huda Kattan

    Historical valuation reports around $1 billion in 2017, with no comparable verified current standalone valuation established for this article.

    The sources for these figures include Reuters’ Fenty Beauty reporting, Fortune’s 2026 creator-economy analysis, Coty’s corporate reporting and e.l.f. Beauty’s SEC filing.

    These figures come from different dates and sources. They are not a definitive ranking of the five largest celebrity beauty companies. Fenty’s figure is annual sales; Rare Beauty’s is an estimate; Kylie Cosmetics’ figure is historical; Rhode’s is an acquisition consideration figure; and Huda Beauty’s is historical.

    A company’s valuation is not the same as its revenue. Revenue is not profit. And neither is equivalent to the founder’s personal fortune.

    Those distinctions are essential to understanding how celebrity beauty businesses create and retain wealth.

    07 — FAME IS AN ADVANTAGE. IT IS NOT A BUSINESS MODEL.

    Celebrity-founded beauty companies begin with something many new businesses spend years trying to build: attention.

    A famous founder can introduce a product to an established audience. Their personal style can help establish a visual identity, while social platforms provide channels through which customers can discover, discuss and recommend products.

    But the competitive advantage has limits.

    Products can be copied. Trends can move on. Social-media algorithms change. Consumers can lose interest. And a successful launch does not guarantee that customers will purchase again.

    The October 2026 creator-marketing analysis offers a useful perspective. Five celebrity-founded brands appeared in the top ten US beauty brands ranked by creator-marketing performance for 2025. Yet the same market contains companies that have struggled despite high-profile founders.

    Fortune reported that Gwen Stefani’s GXVE Beauty shut down in early 2026, while Drew Barrymore’s Flower Beauty ceased operations in September 2025.

    These cases demonstrate why fame and commercial durability should not be confused. A celebrity can attract attention, but a company still needs products that consumers want, an effective route to market and a reason for customers to return.

    The strongest model combines the founder’s visibility with a recognisable proposition and an organisation capable of operating beyond constant personal promotion.

    Celebrity may open the door. The business must still earn its place.

    08 — WHO REALLY OWNS THE BILLIONS?

    The phrase celebrity beauty billionaire can blur several different ideas.

    A founder may own a majority stake in a private company, a minority stake in a brand operated by a larger group, or an ownership interest that has changed through investment and acquisition. A transaction can involve cash, shares and future payments rather than a single guaranteed payout.

    Rihanna’s personal wealth, for example, cannot be calculated by treating Fenty Beauty’s reported sales as money she personally receives. Coty’s stake in Kylie Cosmetics means the brand’s historical valuation cannot simply be assigned to Jenner. Rhode’s transaction similarly included closing consideration and potential earn-outs.

    The distinction does not diminish what these founders have built. It makes the business story more meaningful.

    The important questions are how much economic value a company creates, how its ownership is structured, how much of that value the founder retains and whether the business can continue to grow.

    For a serious business editorial, those questions matter far more than a celebrity net-worth headline.

    THE INSYDE TAKE

    Beauty has always sold more than cosmetics. It sells identity, aspiration, ritual and the possibility of becoming a slightly different version of oneself.

    Celebrity-founded brands have learned to turn those ideas into businesses.

    Fenty Beauty helped bring inclusivity into the centre of the beauty conversation. Rare Beauty built a recognisable identity around self-expression. Kylie Cosmetics turned social-media attention into a business that entered a major corporate partnership. Rhode attracted an acquisition with consideration approaching the billion-dollar mark. Huda Beauty demonstrated how beauty expertise and an audience could develop into an international product company.

    Their financial stories are different. Some figures are disclosed sales; others are historical valuations, estimates or acquisition values. None should be mistaken for the founder’s personal fortune.

    But the larger lesson is consistent.

    Fame creates visibility. Influence can create demand. A recognisable identity can help a brand stand apart.

    What turns those advantages into a business is the harder work: product development, distribution, customer loyalty, operational execution and the ability to remain relevant after the first wave of attention fades.

    The next generation of celebrity beauty brands will not succeed simply because their founders are famous.

    They will succeed if consumers keep coming back.

    Because in the beauty business, the first sale may come from influence.

    The next one has to be earned.

    BEAUTY. BILLIONS. & INFLUENCE.

    INSYDE — BEAUTY, BUSINESS & CULTURE

    NO.1 LUXURY MAGAZINE IN BENGALURU

  • THE ART OF TEMPTATION

    THE ART OF TEMPTATION

    Inside the seductive world of luxury chocolate, where rare cacao, extraordinary craftsmanship and the pursuit of pleasure turn a familiar indulgence into something far more sophisticated.

    INSYDE MAGAZINE | LUXURY

    Chocolate has always understood the art of seduction. It melts slowly, lingers on the palate and transforms an ordinary moment into something worth savouring. But at the upper end of the market, chocolate is no longer simply a sweet indulgence. It is an expression of taste, craftsmanship, provenance and the increasingly sophisticated business of pleasure.

    Behind an elegant box of bonbons or a carefully wrapped bar of dark chocolate lies a world of cacao varieties, agricultural heritage, technical precision and creative experimentation. Some makers draw on generations of European confectionery tradition. Others look towards distinctive growing regions, unusual flavour profiles or entirely different ways of experiencing chocolate.

    Their products may differ in price, philosophy and presentation. What connects them is an ambition to make chocolate more than an everyday purchase: to turn it into an experience that invites attention, curiosity and desire.

    Yet luxury is not simply a matter of charging more. A beautiful package cannot compensate for an unremarkable product, and an expensive ingredient does not automatically guarantee an exceptional result. The more interesting story lies in the relationship between the cacao, the maker and the experience that ultimately reaches the consumer.

    This is where the art of temptation begins.

    WHEN CHOCOLATE BECOMES LUXURY

    For much of its commercial history, chocolate has been associated with comfort, celebration and accessible indulgence. Luxury chocolate operates through a more layered proposition.

    Here, the conversation extends beyond sweetness to the origin of the cacao, the balance of flavours, the texture of a ganache, the precision of a chocolate shell and the decisions made long before a finished product reaches its packaging.

    Presentation matters, but it is only one part of the equation. A beautifully designed box can create anticipation. It cannot, by itself, create exceptional chocolate.

    The most compelling makers establish a recognisable point of view. Some pursue restraint and purity. Others explore intricate flavour combinations, celebrate particular cacao varieties or develop collections that encourage consumers to taste chocolate with the attention usually reserved for fine wine or specialty coffee.

    This approach reflects a broader commercial opportunity. Grand View Research estimates that the global premium chocolate market was worth approximately US$32.9 billion in 2025 and projects it to reach US$34.1 billion in 2026, before growing to US$47.8 billion by 2033. These figures are market-research estimates rather than audited industry totals, but they indicate the scale of the premium segment and its projected growth.

    The opportunity is not simply to sell a more expensive chocolate bar. It is to offer a more distinctive product, a stronger story and an experience consumers consider worth paying for.

    In this market, luxury can mean rarity, technical expertise, heritage, sensory complexity or the pleasure of discovering something unfamiliar. The strongest brands understand that these qualities are most persuasive when they are supported by the product itself.

    FIVE CHOCOLATE HOUSES, FIVE EXPRESSIONS OF LUXURY

    There is no universally accepted ranking of the world’s most luxurious chocolate brands. The following five houses offer a more useful perspective: each illustrates a different way of building distinction in fine chocolate, from cacao provenance to French craftsmanship and Japanese product innovation.

    01. TO’AK CHOCOLATE

    Ecuador | The allure of rarity

    What if the most interesting thing about chocolate were not the recipe, but the cacao itself?

    Ecuadorian maker To’ak has built its identity around the heritage and distinctive character of cacao, particularly the Nacional variety. Its work draws attention to the relationship between the cacao tree, the growing environment, the people cultivating the crop and the final chocolate.

    The brand’s story centres on Ecuador’s Piedra de Plata valley and the preservation of Nacional cacao. Rather than treating cacao as an interchangeable commodity, To’ak presents its origin and characteristics as essential parts of the finished product.

    This philosophy extends into its approach to tasting. Its official catalogue includes a selection of 18 mini bars made from 100% cacao, weighing 54 grams in total and listed at US$60 on the brand’s website at the time of research. The seasonal selection allows consumers to explore differences in harvest and flavour without additional ingredients obscuring the cacao’s character.

    That is a distinctive proposition in a category where chocolate is often judged by sweetness, percentage or packaging alone.

    To’ak’s approach also raises a larger question about luxury: what happens when the ingredient becomes the main attraction? In this case, the answer lies in provenance, variation between harvests and the effort required to preserve particular cacao traditions.

    Rarity, however, should not be confused with quality by default. The value of a rare variety ultimately depends on its flavour, production and the integrity of the story behind it.

    INSYDE perspective: The most persuasive luxury is rarity with substance. When provenance connects to agricultural heritage and a genuinely distinctive tasting experience, the story becomes more than a marketing device.

    Explore: To’ak Chocolate.

    02. LA MAISON DU CHOCOLAT

    France | The Parisian art of indulgence

    Founded in Paris by Robert Linxe in 1977, La Maison du Chocolat helped establish a distinctive language for French luxury chocolate: refined, technically demanding and attentive to the character of each ingredient.

    Its philosophy rests on a deceptively simple idea. Chocolate deserves to be treated as an art form, with the same attention to balance and execution found in other expressions of fine craftsmanship.

    Consider the ganache. Its texture and flavour depend on the relationship between chocolate, cream and other ingredients, as well as the temperatures and techniques used during production. A subtle adjustment can change the result entirely. Achieving consistency while preserving the intended character of a recipe requires experience, precision and careful tasting.

    La Maison du Chocolat places this craft at the centre of its identity. Its history and production philosophy emphasise the expertise of its chocolatiers, from developing fillings to coating and finishing individual pieces.

    There is also a distinctly Parisian sensibility to its presentation. The visual language is elegant without requiring every creation to become an extravagant spectacle. The product remains central, while packaging and presentation frame the experience.

    This is an important distinction in luxury. When every brand competes to appear more exclusive, restraint can become a form of confidence.

    La Maison du Chocolat demonstrates that sophistication does not always require novelty. Sometimes it means taking a familiar pleasure and executing it with extraordinary care.

    INSYDE perspective: True refinement is not about adding more. It is about understanding exactly what each detail contributes to the final experience.

    Explore: La Maison du Chocolat.

    03. AMEDEI

    Italy | The beauty of the bean

    Amedei approaches chocolate through the character of cacao and the qualities that make a particular variety distinctive.

    One of its notable creations is Porcelana, a 70% dark chocolate made with Criollo cacao associated with Venezuela’s Zulia region, southwest of Lake Maracaibo. Amedei describes its Porcelana cacao as rare and highlights a flavour profile that includes notes of almond, toasted bread and bay leaf.

    The details matter because fine chocolate is not defined by cocoa percentage alone. Two bars containing the same proportion of cacao can taste remarkably different, depending on the beans used, fermentation, roasting, conching and other production choices.

    Amedei’s Porcelana offers an example of how a particular cacao variety can become central to a product’s identity. The origin, flavour profile and production philosophy give the chocolate a story that extends beyond its appearance.

    The product also illustrates an important distinction between luxury positioning and luxury pricing. At the time of research, Amedei listed its 50-gram Porcelana bar at €10.30 on its official website. That is a premium price for a small bar, but the more meaningful point is the product’s emphasis on a specific cacao and its sensory characteristics.

    Rarity deserves scrutiny, too. A rare ingredient is not automatically superior for every palate, and a prestigious origin cannot replace good processing. The ultimate test remains what the consumer experiences when the chocolate is tasted.

    That distinction separates informed appreciation from luxury branding alone.

    INSYDE perspective: Exceptional chocolate does not simply announce its quality. It gives the curious consumer something to discover.

    Explore: Amedei Porcelana.

    04. RICHART

    France | Chocolate as a language of flavour

    Not every luxury chocolate experience begins with a rare cacao variety or a centuries-old recipe. Sometimes, it begins with curiosity.

    French chocolate house RICHART takes an approach inspired by the aromatic language of perfumery. Its collections are organised around seven aromatic families: balsamic, roasted, fruity, citrus, herbal, floral and spicy.

    The concept changes the way chocolate is presented to the consumer. Rather than treating every piece as a variation on sweetness, the brand encourages exploration of aroma, flavour and the relationships between ingredients.

    A fruity chocolate creates a different impression from a roasted or herbal one. Citrus can introduce brightness, while spices can add warmth and complexity. These combinations are not merely decorative descriptions; they give the consumer a framework for comparing and understanding different sensory experiences.

    RICHART also pays attention to the form and presentation of its creations. Its Petits RICHART chocolates, introduced in 1988 according to the brand, are designed as small, carefully composed pieces in which appearance and aromatic character work together.

    The appeal is closer to discovering a collection than simply buying a sweet treat. Each piece becomes part of a broader experience, inviting comparison and encouraging the consumer to slow down.

    This approach reveals another dimension of luxury: not everything needs to be rare to be distinctive. A product can create value through the intelligence of its design and the way it encourages people to experience familiar ingredients differently.

    INSYDE perspective: Sometimes the most seductive luxury is the one that makes you curious enough to take another bite.

    Explore: RICHART.

    05. ROYCE’

    Japan | The art of texture

    Luxury chocolate does not belong exclusively to Europe’s established confectionery traditions.

    Founded in Sapporo, Hokkaido, in July 1983, ROYCE’ has developed a distinct identity through its attention to ingredient quality, originality, texture and presentation. Its Nama Chocolate, in particular, is associated with a soft, delicate texture that differs from the familiar snap of a conventional solid chocolate bar.

    That contrast is central to the experience. Chocolate is often discussed through its cocoa percentage or origin, but texture can be just as influential. The way a piece yields, melts and releases flavour can shape the entire tasting experience.

    ROYCE’ has built its philosophy around quality, originality and surprise, drawing on its Hokkaido roots while developing products for a wider international audience. Its approach demonstrates how a premium identity can emerge from a distinctive product experience rather than from European heritage or elaborate visual codes alone.

    There is a practical dimension to this, too. Products with a softer texture and specific storage requirements demand attention to handling, freshness and distribution. Those considerations form part of the product’s character, not merely the logistics behind it.

    ROYCE’ is also a relevant name for Indian readers. Its India website lists availability in cities including Bengaluru, Mumbai, New Delhi, Gurugram, Kolkata and Pune. Current stock and product ranges should still be checked with the retailer before planning a purchase.

    Its story is a reminder that luxury does not need to look the same everywhere. A recognisable experience, executed consistently, can become a brand’s strongest signature.

    INSYDE perspective: Luxury is not a single aesthetic. It is the ability to create something that feels unmistakably its own.

    Explore: ROYCE’ India.

    THE PRICE OF PLEASURE

    The luxury chocolate conversation becomes more complicated when price enters the picture.

    Rare cacao, specialist production, careful sourcing and labour-intensive finishing can all contribute to the cost of fine chocolate. But price is also influenced by brand positioning, packaging, distribution, taxes, retail location and the format in which a product is sold.

    A tasting collection and a single-origin bar are not necessarily competing on the same terms. Nor can a limited-edition creation be compared fairly with a widely available product simply by looking at the price on the label.

    The broader cacao market adds another layer to the conversation. Cocoa prices are influenced by supply and demand, weather, crop conditions, inventories and developments in producing countries. Those movements can affect manufacturers, but they do not translate directly into the retail price of every finished chocolate.

    The relationship between raw cacao and luxury chocolate is especially complex because specialist makers may prioritise particular varieties, regions or sourcing relationships rather than purchasing ingredients solely on commodity-market terms.

    For consumers, the more useful question is not simply whether a chocolate is expensive. It is what the price represents.

    Is it the quality and provenance of the cacao? The skill required to produce the chocolate? A distinctive flavour experience? A thoughtfully designed gift? Or primarily the prestige attached to the name?

    There is no single answer across the category. Amedei’s Porcelana and To’ak’s tasting selection, for instance, offer different experiences at different price points. Comparing them solely by cost would overlook what each product is designed to deliver.

    The strongest luxury brands make that distinction clear. They give consumers a reason to understand the product beyond its price tag.

    BEYOND THE BOX: WHAT MAKES LUXURY CHOCOLATE MATTER?

    Luxury chocolate sits at the intersection of food, design, gifting and culture. Its appeal comes from more than sweetness: it can communicate affection, mark an occasion, signal discernment or provide a private moment of pleasure.

    That is why presentation occupies such a prominent role. A carefully designed box can turn chocolate into a meaningful gift. A thoughtfully arranged collection can make opening the package part of the experience. But presentation is most convincing when it reflects the care invested in what is inside.

    The same principle applies to heritage and provenance. An origin story can deepen appreciation when it is supported by credible information about the cacao, its production and the people involved. Without that substance, storytelling risks becoming decoration.

    There is also a reason to ask harder questions about the supply chain. Cacao production is shaped by agricultural conditions, farmer livelihoods and environmental pressures. Claims about sustainability or ethical sourcing should therefore be judged on evidence rather than on elegant language alone.

    For luxury brands, responsibility and quality need not be separate conversations. Traceable sourcing, long-term relationships with producers and credible efforts to protect distinctive cacao can contribute to the long-term value of a product. The important distinction is between commitments that can be substantiated and claims that simply sound appealing.

    As the premium chocolate market evolves, its most interesting brands will be those that connect exceptional taste with meaningful provenance, skilled production and a credible account of how their products are made.

    Luxury becomes more convincing when the story survives scrutiny.

    THE INSYDE TAKE

    The most luxurious chocolate is not necessarily the one with the highest price tag, the most elaborate packaging or the rarest-sounding name.

    It is the one in which the details come together: the cacao has a reason to be celebrated, the maker understands the material, the flavour delivers on its promise and the experience feels considered from beginning to end.

    To’ak makes the case for provenance and rarity. La Maison du Chocolat demonstrates the power of refinement. Amedei invites a closer look at cacao character. RICHART turns tasting into exploration. ROYCE’ shows how texture and product identity can create a different kind of indulgence.

    Five distinct approaches, one shared idea: chocolate becomes more interesting when we look beyond the sweetness.

    Perhaps that is the real art of temptation. Not simply making us want another piece, but giving us a reason to pay closer attention to the one already in front of us.

    INSYDE MAGAZINE

    Luxury, Through a Different Lens.

    No.1 luxury Magazine in Bengaluru

  • INSIDE THE WORLD’S MOST LUXURIOUS TRAIN JOURNEYS

    INSIDE THE WORLD’S MOST LUXURIOUS TRAIN JOURNEYS

    From restored Art Deco carriages in Europe to palace-inspired suites in India and grand expeditions across Africa, luxury rail travel is transforming the journey itself into the ultimate indulgence.

    There are faster ways to cross continents. There are more private ways to travel. And there are certainly more direct ways to reach a destination.

    Yet few experiences capture the imagination quite like stepping aboard a beautifully restored railway carriage, settling into a private suite and watching the world unfold through the window. Outside, landscapes shift from mountain passes to historic cities and vast open plains. Inside, the pace changes. Dinner becomes an occasion, the journey becomes the destination, and time itself becomes part of the luxury.

    Luxury rail travel occupies a distinctive place in the world of high-end hospitality. It combines the romance of historic railway journeys with the comforts of contemporary service: beautifully appointed accommodation, considered cuisine, attentive staff and itineraries that connect passengers with places worth experiencing slowly.

    The economics are equally fascinating. Depending on the route, accommodation and duration, a luxury train journey can cost several thousand pounds per person or reach tens of thousands for a single booking. These fares are not directly comparable: a one-night cabin, a multi-night private suite and an expedition with extensive excursions represent very different products.

    What unites them is a philosophy of travel that places the experience itself at the centre.

    That philosophy resonates with the wider luxury travel market. Virtuoso’s 2026 Luxe Report, drawing on insights from more than 2,400 travel advisers across over 50 countries, identifies cultural immersion, authenticity, food and wine, and meaningful travel experiences among the priorities shaping affluent travel. The report also finds that travellers remain willing to spend more when the experience justifies the cost.

    Luxury trains offer a compelling expression of these priorities. They transform the space between destinations into something worth paying for.

    From the legendary carriages of the Venice Simplon-Orient-Express to the palace-inspired suites of India’s Maharajas’ Express, these five journeys demonstrate the many ways luxury can be experienced on the rails.

    01. Venice Simplon-Orient-Express, Europe

    Few names in luxury travel possess the cultural resonance of the Venice Simplon-Orient-Express. Its midnight-blue carriages, polished woodwork, intricate marquetry and Art Deco interiors evoke an era when railway travel was an expression of elegance in its own right.

    Operated by Belmond, the train has built its reputation around the restoration of historic carriages and an experience shaped by craftsmanship, gastronomy and personal service. Its restaurant cars turn dinner into an event, while dedicated stewards and carefully appointed cabins preserve the intimacy of traditional railway travel.

    The celebrated Paris–Istanbul itinerary offers a particularly evocative example. The five-night journey connects Paris with Istanbul through a route that includes Budapest and Bucharest, with excursions and hotel stays forming part of the broader experience. It draws on the mythology of the original Orient Express tradition while operating as a distinct contemporary luxury service.

    The price of admission

    Belmond’s official listings show the five-night Paris–Istanbul journey in 2026 from £19,900 per adult in a Historic Cabin. For comparison, its one-night Paris–Venice journey starts from £4,275 per adult in the same cabin category. These are published starting fares, not guaranteed prices for every departure; availability and cabin selection affect the final cost.

    The distinction matters. The longer itinerary is not simply a more expensive version of the same night aboard. It incorporates a broader journey, additional destinations and a different scale of experience.

    Why it matters

    The Venice Simplon-Orient-Express demonstrates how heritage can become a contemporary luxury asset. In a market where new hotels and experiences appear constantly, its appeal rests partly on the sense of stepping into a world that has deliberately resisted the ordinary rhythms of modern travel.

    Its most valuable feature may not be any single amenity. It is the coherence of the experience: the carriage design, service, dining and route all contribute to the same idea of glamour.

    02. Maharajas’ Express, India

    India’s luxury hospitality industry has long drawn on its palaces, historic residences and traditions of elaborate service. The Maharajas’ Express brings those influences together in a journey designed around the country’s architectural, cultural and royal heritage.

    Its itineraries connect destinations associated with monumental architecture, historic cities and India’s diverse regional identities. The train becomes a travelling base from which guests can explore the country without repeatedly checking into and out of conventional hotels.

    The accommodation ranges from Deluxe Cabins to the Presidential Suite. At the highest level, the proposition extends beyond interior design to include personalised service, guided sightseeing and private vehicles for excursions. The operator’s published inclusions vary by category, making it important to examine the details rather than treating every fare as equivalent.

    The price of admission

    For the 2026–27 season, the official fare table lists the Presidential Suite on the seven-day, six-night Indian Splendour itinerary at ₹26.13 lakh per person, based on twin-sharing occupancy, before an additional 5% GST. The same listed Presidential Suite fare applies to the Heritage of India itinerary. The operator notes that Indian-rupee tariffs are subject to revision every two months, so the published amount should be reconfirmed before booking.

    At this price, the train occupies a distinctive position in India’s premium travel market. Its value proposition is a curated journey combining accommodation, dining, guided excursions and a service model built around the experience of travelling in comfort.

    Why it matters

    The Maharajas’ Express shows how Indian heritage can be translated into a contemporary luxury product for domestic and international audiences. It is not simply a train with lavish interiors; it is an example of destination-led hospitality, where architecture, history and service contribute to the overall value.

    For India, that distinction is significant. Luxury travel need not depend on importing an international aesthetic. It can draw its appeal from the country’s own cultural depth and traditions of hospitality.

    03. Royal Scotsman, Scotland

    In Scotland, luxury often finds expression in historic estates, natural materials, regional cuisine and a close relationship with the landscape. The Royal Scotsman brings these qualities together in a travelling environment that feels closer to an intimate country retreat than conventional transport.

    Its itineraries pass through the Scottish Highlands and other regions of the country, combining scenic rail travel with excursions, cultural experiences and food-led programmes. Selected journeys also explore Scotland’s whisky heritage, giving passengers a deeper connection with the places they visit.

    The accommodation is central to the experience, but the surrounding landscape is equally important. Mountains, lochs, villages and historic sites provide a changing backdrop that no fixed hotel could reproduce in quite the same way.

    The price of admission

    Belmond’s official listings include the five-night Clans, Castles & Isles journey from £73,500 per Grand Suite, quoted per cabin. A separate four-night The Highlands journey is listed from £21,000 per cabin in a Double Cabin. These are different accommodation categories and itineraries, not directly comparable per-person fares.

    The figures illustrate why luxury train prices require careful interpretation. A quoted cabin price is not the same as a per-person rate, and the cost of a journey depends on the selected accommodation, itinerary and booking conditions.

    Why it matters

    The Royal Scotsman represents a quieter form of exclusivity. Rather than relying on spectacle alone, it combines privacy, landscape, food and heritage in a relatively intimate setting.

    Its appeal lies in the feeling of being looked after while remaining connected to the destination. For travellers who value atmosphere over display, that may be precisely the point.

    04. Rovos Rail, Southern Africa

    The appeal of Rovos Rail is rooted in distance. Its journeys offer an alternative to the short flight and quick transfer, inviting passengers to experience southern Africa through the changing landscapes between destinations.

    The Cape Town route provides a compelling example. Covering approximately 1,600 kilometres over three nights, it travels through the Cape Winelands and the Great Karoo, with excursions including the historic village of Matjiesfontein and Kimberley’s Diamond Mine Museum.

    The train’s suites retain the character of classic railway accommodation while providing private bathrooms, seating areas and practical comforts. The Royal Suite, in particular, is designed around a private lounge and an en-suite bathroom with a bath and separate shower.

    The experience is less about reaching a single famous destination than about seeing a vast region unfold over several days.

    The price of admission

    Rovos Rail publishes fares according to itinerary, travel period and suite category. Its official Cape Town journey page provides separate rate tables for 2026, 2027 and 2028, reflecting the importance of checking the correct travel season before quoting a fare.

    The appropriate approach is to consult the operator’s current rate table for the intended departure rather than attach an unverified price to the journey. Rates for an earlier season should not be presented as current 2026–27 prices.

    Why it matters

    Rovos Rail illustrates a different expression of luxury: exploration without sacrificing comfort. Its appeal comes from the combination of long-distance travel, heritage railway design and access to landscapes that reveal themselves gradually.

    In this setting, the journey is not an interruption between experiences. It is the experience.

    05. La Dolce Vita Orient Express, Italy

    If the Venice Simplon-Orient-Express evokes historic European glamour, the La Dolce Vita Orient Express offers a more contemporary interpretation of luxury rail travel.

    Its concept draws on Italian design, regional cuisine and the appeal of exploring the country through carefully planned itineraries. Rather than relying exclusively on nostalgia, it presents the train as a contemporary setting for experiencing Italian culture, food and landscapes.

    The programme includes journeys through Italy as well as a longer Rome–Istanbul itinerary. Its offering spans shorter regional experiences and multi-night international travel, each with a different price and itinerary.

    The price of admission

    The official booking listings show the four-night Rome–Istanbul journey scheduled for 22–27 October 2026 at €20,000, including taxes. The same listings show the one-night Tastes of Tuscan Vineyards experience from €3,060, including taxes, for a November 2026 departure. These are specific published offerings, and availability and prices may change.

    The comparison reveals two distinct interpretations of luxury. One is a short, destination-focused escape; the other is an extended journey across borders. Both use the train as a setting for hospitality and discovery, but their durations and experiences differ considerably.

    Why it matters

    La Dolce Vita Orient Express demonstrates that luxury rail travel is not confined to reproducing the past. It can reinterpret the format through contemporary design and a strong connection with regional culture.

    Its proposition is particularly relevant to travellers who see gastronomy, architecture and a sense of place as essential parts of a premium experience.

    The Economics of Exclusivity

    The published fares make one point clear: luxury rail travel is not a single category of product. It ranges from overnight journeys in historic cabins to multi-night experiences involving premium suites, curated excursions and extended itineraries.

    The following comparison uses published operator listings available in October 2026. It is not a ranking of the five most expensive trains in the world.

    JourneyPublished price referenceWhat the price represents
    Venice Simplon-Orient-ExpressFrom £19,900 per adultFive-night Paris–Istanbul, Historic Cabin, 2026
    Maharajas’ Express₹26.13 lakh per person, plus 5% GSTSix-night Indian Splendour, Presidential Suite, twin-sharing basis, 2026–27
    Royal ScotsmanFrom £73,500 per cabinFive-night Clans, Castles & Isles, Grand Suite
    Rovos RailVaries by journey and seasonCheck the current official rate table for the selected departure
    La Dolce Vita Orient Express€20,000 including taxesFour-night Rome–Istanbul journey listed for October 2026

    These figures should not be compared as if they were equivalent tickets. Some are per person, others per cabin; some include taxes, while the Maharajas’ Express fare explicitly excludes GST. Journey duration and inclusions also differ.

    A fair comparison must consider what is included in each fare: accommodation, meals, beverages, guided excursions, transfers and any hotel stays away from the train. It must also distinguish the advertised starting price from the amount a traveller would pay for a specific departure.

    The broader lesson is that the price of luxury rail is determined by more than distance. Accommodation, service, itinerary design and the overall experience all contribute to the final fare.

    Why the Journey Matters More Than the Destination

    The appeal of luxury rail travel becomes clearer when viewed against the wider direction of affluent tourism. Virtuoso’s 2026 Luxe Report highlights cultural immersion, authenticity, food and wine, and meaningful travel among the interests shaping the market. It also reports that 55% of surveyed advisers expect spending per trip to increase modestly, while 28% anticipate spending to remain stable. These are adviser expectations, not measured growth in train bookings, but they provide useful context for the premium experiences market.

    Luxury trains align with these priorities in several ways.

    They make time part of the experience. A journey lasting several nights encourages passengers to settle into a rhythm rather than treat travel as an inconvenience.

    They combine several forms of hospitality. Accommodation, dining, scenery, excursions and personal service are brought together in a single itinerary.

    They give heritage a contemporary purpose. Historic railway design and regional traditions become part of a modern premium product.

    They create a sense of occasion. The act of boarding, dressing for dinner, watching the landscape change and arriving somewhere new becomes a sequence of experiences in its own right.

    This does not mean luxury trains are replacing private aviation, superyachts or five-star hotels. Each serves a different purpose. A private jet prioritises flexibility and speed; a luxury train asks passengers to value the time spent travelling.

    That distinction is central to understanding the market. The appeal is not that a train can do what an aircraft does, only more slowly. It is that the experience of travelling by rail can offer something an aircraft cannot easily replicate.

    The Future of Luxury on Rails

    Luxury rail travel occupies a distinctive position between transportation and hospitality. Its strongest operators understand that beautiful interiors alone are not enough. The route must be compelling, the service consistent, the excursions worthwhile and the experience coherent from departure to arrival.

    India’s Maharajas’ Express demonstrates how heritage-led hospitality can attract international attention. The Venice Simplon-Orient-Express shows how historic design can retain its cultural and commercial appeal. The Royal Scotsman and Rovos Rail present different interpretations of landscape-led exploration, while La Dolce Vita Orient Express offers a contemporary approach to Italian design and regional culture.

    Their differences matter. There is no single definition of luxury, and the most expensive option is not automatically the most rewarding. For one traveller, it may be a private suite and a formal dinner; for another, it may be the opportunity to cross a remarkable landscape without rushing through it.

    What these journeys share is a belief that travel can be more than the movement between two points.

    In a world increasingly organised around speed and convenience, that belief has become a luxury of its own.

    Perhaps that is the enduring attraction of travelling by rail at its most exceptional. The destination still matters, but it no longer has to justify every moment spent getting there.

    Sometimes, the journey is the privilege.

    INSYDE MAGAZINE – no.1 Luxury Magazine in Bengaluru

  • SAKS’ $2.7 BILLION GAMBLE

    SAKS’ $2.7 BILLION GAMBLE

    How a landmark acquisition, mounting debt and a breakdown in supplier confidence pushed an American luxury retail institution into bankruptcy — and what its restructuring reveals about the future of luxury shopping.

    Luxury has always sold more than a product. It sells access, identity and the feeling that something ordinary has been transformed into something exceptional.

    For generations, Saks Fifth Avenue understood that proposition. Its celebrated New York flagship became a symbol of American luxury shopping, connecting international fashion houses with customers who expected exceptional merchandise, personal service and an experience that extended beyond the transaction.

    Alongside Neiman Marcus and Bergdorf Goodman, Saks occupied a distinctive position in the American retail landscape. These were not simply stores selling expensive clothes. They were institutions built around the idea that how luxury is discovered and purchased matters almost as much as what is purchased.

    In 2024, the company behind Saks made a bet on that legacy.

    A $2.65 billion acquisition of Neiman Marcus Group, widely reported as a $2.7 billion deal, brought Neiman Marcus and Bergdorf Goodman under the same corporate umbrella as Saks Fifth Avenue. The ambition was to create a more powerful luxury retail group — one with greater purchasing scale, broader customer reach and the technology to compete in a rapidly changing market.

    Instead, barely thirteen months after completing the transaction, the enlarged group filed for Chapter 11 bankruptcy protection.

    The company entered bankruptcy on 13 January 2026 with approximately $3.4 billion in funded debt obligations. Supplier-payment problems and inventory shortages had become serious operational concerns. The crisis threatened the commercial relationships on which a luxury department store depends.

    Yet the story did not end with bankruptcy. On 26 June 2026, the restructured company emerged under a new corporate name: Exemplar Luxury Group, with debt reduced by nearly 75%, according to its announcement. Saks Fifth Avenue, Neiman Marcus and Bergdorf Goodman remained part of the portfolio.

    The brands survived. The financial structure that brought them together did not.

    This is the story of a luxury acquisition that promised scale but exposed financial fragility — and of an industry in which heritage, desirable merchandise and wealthy customers cannot compensate indefinitely for a business that struggles to pay its suppliers.

    THE AMBITION: BUILDING A LUXURY POWERHOUSE

    The logic behind the Neiman Marcus acquisition was easy to understand.

    Saks Fifth Avenue brought national recognition and a celebrated flagship. Neiman Marcus had a strong presence in affluent American markets, while Bergdorf Goodman occupied a particularly rarefied position in New York luxury retail. Each brand had its own identity, customer base and place in the market.

    Bringing them together promised a larger platform for selling luxury goods.

    The acquisition was announced at an enterprise value of approximately $2.65 billion in July 2024 and completed in December of that year. The resulting Saks Global combined Saks Fifth Avenue, Neiman Marcus, Bergdorf Goodman and the Saks OFF 5TH off-price business.

    The strategy centred on several potential advantages.

    A larger retailer could negotiate more effectively with suppliers, improve distribution, consolidate back-office operations and invest in technology across a broader customer base. It could also use customer data more effectively, connect online and in-store shopping, and create more opportunities for product discovery.

    The deal attracted high-profile technology partners. Amazon and Salesforce were expected to contribute expertise in areas including fulfilment, supply-chain operations and customer data.

    The ambition was not merely to own more stores. It was to create a more technologically capable luxury retailer.

    But there was a critical distinction between the strategic promise and the financial reality.

    A merger can create opportunities for efficiency. It does not guarantee that those efficiencies will arrive quickly enough, generate enough cash or outweigh the financial obligations incurred to complete the transaction.

    Luxury retail is particularly demanding in this respect. A department store must finance inventory, maintain expensive locations, employ specialist staff, invest in digital operations and settle supplier invoices. It must do all of this while keeping merchandise fresh and the customer experience compelling.

    The acquisition expanded the group’s reach. It also left the combined business needing to demonstrate that its new scale could support its financial commitments.

    That was the gamble at the heart of the deal.

    THE DEBT BEHIND THE DEAL

    The acquisition’s significance becomes clearer when viewed through the company’s balance sheet.

    Saks Global filed for bankruptcy protection in January 2026 with approximately $3.4 billion in funded debt obligations, according to reporting based on its bankruptcy filings.

    The figure matters because debt changes how a retailer can respond to pressure.

    Borrowing is not inherently a mistake. Companies use debt to acquire businesses, invest in infrastructure and finance growth. The risk arises when the cost of servicing that debt leaves insufficient flexibility to manage the operating business.

    For a department store, cash is constantly moving through a demanding cycle. Merchandise must be ordered and paid for; stores and employees must be funded; products must be sold; and the resulting cash must support both future inventory and other financial obligations.

    If too much cash is committed to debt service, the business has less room to absorb weak sales, delays in customer spending, unexpected expenses or slower-than-anticipated integration benefits.

    The problem can become self-reinforcing.

    A retailer under liquidity pressure may struggle to pay suppliers. Reduced supplier confidence can restrict merchandise availability. Less inventory can weaken sales, leaving the business with even less cash to stabilise operations.

    The result is a dangerous mismatch between the capital required to run the business and the cash available to support it.

    This is why the distinction between the acquisition price and the company’s subsequent debt burden matters. The $2.65 billion enterprise value was the reported value of the transaction; the approximately $3.4 billion in funded debt at the bankruptcy filing was a separate measure of the group’s financial obligations.

    They should not be treated as interchangeable figures.

    The broader lesson is that an acquisition’s success cannot be judged by the prestige of the assets acquired or the size of the combined organisation. It must be judged by whether the business can generate enough cash to support the structure created around it.

    In Saks’ case, that structure proved unsustainable in its existing form.

    WHEN A FINANCIAL CRISIS REACHED THE SHELVES

    A luxury department store has a problem when it cannot reliably secure the products that made it desirable in the first place.

    During the period leading up to bankruptcy, Saks Global struggled with supplier payments and merchandise availability. The consequences extended beyond its finance department. They threatened the retailer’s ability to offer customers the assortment they expected.

    For luxury houses, distribution is carefully managed. Brands choose where their products appear, how they are presented and which retail partners represent them. The relationship with a department store involves not only sales, but also positioning, service and the protection of a brand’s image.

    Payment reliability is part of that relationship.

    When a retailer falls behind on invoices, suppliers must decide how much commercial risk they are prepared to accept. They may seek stronger payment terms, limit exposure or pause shipments until outstanding concerns are resolved.

    That creates a particular problem for a multi-brand retailer.

    Its value depends on bringing desirable products together in one place. Customers may visit for a specific designer, collection or new-season item. If that merchandise is unavailable, the customer has alternatives: another department store, a competing retailer or the brand’s own boutique or website.

    The retailer loses more than a potential transaction. It risks losing the customer’s reason to return.

    Court filings reported by Reuters showed the scale of Saks Global’s exposure to luxury suppliers. Chanel was listed among its major unsecured creditors with a claim of approximately $136 million, while Kering, the owner of Gucci, was listed at around $60 million. The top 30 unsecured creditors collectively represented approximately $712 million in claims.

    These figures illustrate the scale of the commercial relationships involved. They do not establish that every listed supplier withdrew merchandise or stopped shipping.

    The broader problem was confidence.

    By March 2026, Reuters reported that more than 500 brands had resumed shipping products to Saks Global and that the company had released nearly $1.3 billion in retail receipts — a measure of merchandise value, not revenue earned. The development suggested that supplier relationships and inventory flows were beginning to recover during the bankruptcy process.

    It also revealed how far the crisis had reached.

    The retailer’s financial difficulties had become an inventory problem, and its inventory problem had become a customer-experience problem.

    For a business built around access to desirable goods, that is a fundamental threat.

    THE DEPARTMENT STORE’S CHANGING PLACE IN LUXURY

    Saks was not operating in the same retail environment that had shaped its historic success.

    Luxury brands have spent years investing in their own boutiques, websites, clienteling systems and direct relationships with customers. These channels allow brands to control presentation, service, customer data and the way their products reach the market.

    Department stores still offer something valuable: curation across multiple designers, the convenience of shopping several brands in one place and the possibility of discovering products a customer might not otherwise encounter.

    But the department-store proposition must justify its role.

    A luxury house may increasingly ask whether a wholesale partner provides enough incremental reach, sales and customer value to justify the commercial terms. A shopper may ask whether visiting a department store offers a better experience than purchasing directly from the brand.

    The department store sits between these two questions.

    It needs brands to provide desirable merchandise, and it needs customers to believe that shopping through the retailer is worthwhile. Its commercial value depends on delivering a strong experience to both sides.

    That model becomes more difficult when financial pressure compromises the very things that make the store attractive.

    A retailer cannot consistently promise exceptional curation without access to the right products. It cannot provide outstanding service indefinitely without investing in staff, technology and physical spaces. And it cannot rebuild its reputation if customers repeatedly encounter gaps in availability.

    The challenge is not that department stores have become irrelevant. It is that their relevance can no longer be assumed.

    They must offer a compelling reason to exist in a market where luxury brands have greater control over distribution and customers have more ways to shop.

    Saks’ difficulties exposed what happens when the financial capacity to deliver that proposition begins to weaken.

    THE WIDER LUXURY MARKET ADDED PRESSURE

    The luxury market has also become more challenging.

    On 6 October 2026, Reuters reported that US luxury spending had declined year over year for a third consecutive month, based on Citi credit-card data. Spending was down 6% in September, following declines of 4% in July and August.

    The data suggested that even affluent consumers were approaching some luxury purchases more cautiously amid economic uncertainty.

    A separate Reuters report on 9 October described additional pressure from China’s tax crackdown on wealthy individuals, alongside weaker US spending and wider market concerns. Chinese consumers have historically been important to global luxury demand, so developments affecting their spending can influence the industry’s outlook well beyond China.

    These figures provide relevant context for Saks’ restructuring. They do not prove that a luxury slowdown caused its bankruptcy.

    The company’s difficulties were rooted in a combination of financial obligations, liquidity pressure and supplier-payment problems. A weaker consumer environment made recovery more challenging, but it was not a sufficient explanation for the crisis on its own.

    This distinction matters.

    Luxury businesses do not all respond to market weakness in the same way. Their performance depends on customer mix, pricing, product categories, distribution strategy, operating costs and financial resilience.

    A retailer already struggling to pay suppliers has less flexibility when sales disappoint. It has fewer resources to replenish inventory, invest in its stores or absorb the cost of rebuilding confidence.

    The market slowdown therefore acted as an additional pressure on an already vulnerable business.

    The mistake would be to interpret Saks’ bankruptcy as evidence that luxury demand had simply disappeared. The more useful conclusion is that difficult market conditions can expose weaknesses that a stronger balance sheet might otherwise have helped a retailer withstand.

    WHY SCALE WAS NOT ENOUGH

    The promise of a merger is usually expressed in future benefits.

    A combined organisation may expect to reduce duplicated costs, improve purchasing power, streamline logistics and make better use of technology. But these benefits must be realised through execution.

    Integration takes time. Systems must be connected, supplier agreements managed, store portfolios reviewed and operating decisions coordinated. Management must also determine which parts of the business should be combined and which should remain distinct.

    Meanwhile, financial obligations continue.

    If debt and operating costs rise faster than the expected benefits of consolidation, a larger organisation can become more fragile rather than more resilient.

    The Saks transaction illustrates this risk.

    The group brought together three recognised luxury retail names and a substantial portfolio of stores. Yet the combined business still had to prove that its scale could translate into reliable cash generation.

    The bankruptcy filing showed that the original structure could not sustain its obligations and operating needs.

    It would be wrong to conclude that the acquisition alone explains every weakness in the business. Saks Global inherited an industry facing structural changes, and its individual retail brands had different histories and operating challenges.

    But the transaction intensified the importance of financial execution. Once the combined group struggled to maintain supplier payments and merchandise availability, the intended benefits of scale became harder to realise.

    The central lesson is not that consolidation never works. It is that consolidation cannot substitute for financial resilience.

    A larger business may have more opportunities. It also has more obligations to manage.

    JANUARY 2026: BANKRUPTCY AS A RESET

    On 13 January 2026, Saks Global filed for Chapter 11 bankruptcy protection in the United States.

    Chapter 11 allows an eligible company to reorganise its finances under court supervision while seeking to continue operating. It does not automatically mean that every store will close or that every brand will disappear.

    For Saks Global, the process created a route to restructure debt, secure new funding, close underperforming locations and work towards restoring supplier confidence.

    The restructuring plan involved significant sacrifices.

    Reuters reported in June that the court-approved plan would eliminate the company’s existing equity and transfer control to its senior lenders. The plan included $1 billion in new funding from senior lenders and a further $500 million commitment after the company emerged from bankruptcy.

    These were not cosmetic changes. They represented a substantial shift in ownership and financial structure.

    The group also reduced its store footprint. The plan approved in June called for a portfolio of 49 luxury retail locations: 33 Neiman Marcus stores, 15 Saks Fifth Avenue stores and the two-store Bergdorf Goodman operation in New York.

    The reduction in Saks Fifth Avenue’s footprint was especially significant, from approximately 33 stores before bankruptcy to 15 under the approved plan.

    A smaller network can reduce fixed costs and concentrate resources on locations with stronger commercial potential. But it also reduces geographic reach and changes the role of the retailer in markets where it no longer has a physical presence.

    The strategy is a trade-off: operate fewer stores, invest more selectively and attempt to improve the performance of the remaining business.

    Whether that strategy succeeds depends on execution, not simply on the number of stores closed.

    JUNE 2026: A NEW NAME, A DIFFERENT BALANCE SHEET

    On 26 June 2026, the company announced that it had completed its restructuring and emerged from Chapter 11 under the name Exemplar Luxury Group.

    The group said its debt had been reduced by nearly 75% and that it had sufficient liquidity to support its operations and invest in its future. It continued to include Saks Fifth Avenue, Neiman Marcus and Bergdorf Goodman.

    The debt reduction was substantial. It gave the restructured business a materially different financial starting point.

    But lower debt should not be confused with a completed recovery.

    A stronger balance sheet can reduce financial pressure and create room for investment. It does not automatically restore every supplier relationship, guarantee profitable trading or persuade customers to return.

    Nor does the completion of bankruptcy prove that the acquisition strategy has been vindicated. The restructuring involved a major reduction in debt, a transfer of control to senior lenders and a smaller store network. Those are significant changes to the original proposition.

    The new group now faces a different test.

    Can it operate the three retail brands with greater financial discipline? Can it maintain reliable merchandise flows? Can it deliver a distinctive experience while controlling costs? And can it generate sustainable profits without recreating the pressures that led to bankruptcy?

    Those questions will determine whether the restructuring becomes a genuine turnaround or simply a temporary reprieve.

    The corporate name has changed. The operating challenge has not disappeared.

    WHAT SAKS REVEALS ABOUT THE FUTURE OF LUXURY RETAIL

    The Saks story offers three important lessons for the wider luxury industry.

    First, prestige cannot replace liquidity.

    A recognised name, a celebrated flagship and access to desirable designers are valuable assets. But a retailer must still pay for inventory, fund its stores, meet its financial obligations and maintain supplier confidence. Brand equity cannot permanently compensate for a business that lacks the cash to operate.

    Second, supplier relationships are strategic assets.

    For a multi-brand retailer, merchandise availability is central to its appeal. A breakdown in supplier confidence can affect the assortment, weaken customer experience and undermine the retailer’s credibility. Restoring those relationships may be as important as reducing debt.

    Third, scale is valuable only when it produces better economics.

    A merger can create opportunities for efficiency and customer growth. It can also increase complexity and financial obligations. If the benefits arrive too slowly, the larger organisation may become less flexible precisely when it needs to be most resilient.

    There is a fourth lesson, too: the future of the department store depends on differentiation.

    A retailer must give customers a reason to choose its environment over a brand’s own boutique or website. That reason might be exceptional curation, personalised service, access to multiple designers, exclusive merchandise or a physical experience that feels genuinely distinctive.

    It must also give brands a reason to maintain the relationship.

    For luxury department stores, success depends on making both sides believe that the intermediary adds value. That is a demanding proposition, but it remains possible.

    The industry does not need fewer places to discover luxury simply because direct-to-consumer retail has grown. It needs multi-brand retailers that are financially disciplined, commercially reliable and relevant to the way customers shop today.

    Saks’ restructuring is a test of whether that model can be rebuilt on a more sustainable foundation.

    THE REAL PRICE OF THE GAMBLE

    The $2.65 billion Neiman Marcus acquisition was designed to create a more powerful force in American luxury retail. It brought together three established names and promised greater scale, technological capability and access to affluent customers.

    Instead, the combined group entered bankruptcy protection barely thirteen months after the deal closed, with approximately $3.4 billion in funded debt obligations and serious problems involving supplier payments and inventory availability.

    The acquisition was a central part of the story, but it was not the only factor. The broader retail environment was changing, luxury brands were strengthening their direct channels, and the business faced operational pressures that the merger’s promised benefits did not resolve quickly enough.

    By June 2026, the company had emerged with a new corporate identity, substantially reduced debt and a smaller store network. The retail names at the heart of the original ambition remained.

    What remains unproven is whether the new structure can deliver durable, profitable growth.

    That will depend on the fundamentals: cash generation, merchandise availability, supplier confidence, customer experience and disciplined investment. It will depend on whether the group can preserve the distinctiveness of its brands while operating them more efficiently.

    Saks’ story is not proof that luxury is finished, or that department stores no longer have a place in the market. It is a warning that prestige and scale cannot protect a retailer indefinitely when its financial structure undermines its ability to deliver what customers and suppliers expect.

    In luxury, a name can open the door.

    It cannot pay the bills.

    And no matter how desirable the merchandise, a retail empire cannot survive for long if it cannot reliably get that merchandise onto the shelves.

    INSYDE Magazine — Where luxury, culture and influence meet.
    NO.1 LUXURY MAGAZINE IN BENGALORE