Category: Fashion

The people, ideas and movements shaping Indian and global fashion, from couture and bridalwear to contemporary style and the business of fashion.

  • THE PRICE OF EXCLUSIVITY

    THE PRICE OF EXCLUSIVITY

    Why Luxury Brands Destroy What They Cannot Sell

    Luxury’s obsession with scarcity has a hidden cost. From Burberry’s £28.6 million stock destruction disclosure to the European Union’s new restrictions, the industry is being forced to confront the environmental and commercial consequences of unsold products.

    Luxury is built on desire. A handbag can become a cultural symbol, a watch can represent generations of craftsmanship, and a coat can command a price far beyond the cost of its materials. The promise is that these objects offer something more than utility: heritage, identity, exclusivity and enduring value.

    But what happens when a product is made, the season passes, and nobody buys it?

    For much of the luxury industry, unsold inventory presents a dilemma. Discounting can undermine carefully cultivated price perceptions. Selling through unauthorised channels can weaken control over distribution. Holding stock indefinitely ties up capital and warehouse space. And when products become commercially undesirable, brands must decide whether to resell, repurpose, donate, recycle or dispose of them.

    In documented cases, some luxury companies have gone further, destroying products or buying back unsold merchandise to prevent it from entering discounted markets.

    The practice exposes an uncomfortable contradiction at the heart of luxury: an industry that celebrates craftsmanship and lasting value has, at times, discarded products that still possessed material and functional worth.

    The question is not simply why luxury brands destroy unsold goods. It is whether protecting exclusivity can justify the cost of making valuable products go to waste.

    The Business of Scarcity

    Luxury does not operate like conventional mass-market retail. Its strongest brands sell not only products but also distinction. Carefully controlled distribution, limited availability, heritage and pricing all contribute to the perception that an item is special.

    A product sold at full price reinforces the brand’s intended positioning. The same product appearing repeatedly at steep discounts can change how consumers perceive its value. Customers may begin to delay purchases, expecting future markdowns, while authorised retailers face pressure to compete with cheaper alternatives.

    For a luxury house, the consequences can extend beyond a single unsold item. They can affect pricing discipline, retailer relationships and the perceived desirability of an entire collection.

    This helps explain why luxury businesses have historically sought to control excess inventory rather than automatically clear it through conventional discount channels. Depending on the product and market, options may include transfers between stores, private sales, authorised outlets, buybacks, resale and recycling.

    Destruction is the most extreme response, but it is not the only one. Nor is there evidence that every luxury brand follows the practice.

    The commercial logic is nevertheless clear: a company may judge that the potential damage to its pricing power and brand image outweighs the immediate benefit of selling surplus stock at a lower price.

    That calculation can explain the decision. It does not automatically justify it.
    Burberry’s £28.6 Million Disclosure

    In 2018, British luxury house Burberry became the focus of an international debate after its annual report disclosed that the cost of finished goods physically destroyed during the financial year ending March 2018 was £28.6 million, up from £26.9 million in the previous year. The total included £10.4 million of beauty inventory.

    The figures appeared in the company’s 2017–18 annual reporting, with contemporaneous coverage documenting the disclosure and its implications. The episode prompted questions from consumers, investors and environmental campaigners about why finished products were being destroyed instead of sold, reused or donated.

    The controversy was not simply about the monetary value of the goods. It was about what the practice communicated. A brand associated with craftsmanship, quality and longevity was disposing of products that had already consumed materials, energy, labour and resources.

    On 6 September 2018, Burberry announced that it would stop destroying unsaleable products with immediate effect. In its official statement, the company said it already reused, repaired, donated or recycled unsaleable products and would expand those efforts.

    The chronology matters. The £28.6 million figure is historical, and Burberry’s subsequent announcement was a commitment to end the practice. It should not be interpreted as evidence that the company continues to destroy unsaleable products at the same rate today.

    The case nevertheless established an important precedent: a practice once treated as an operational decision could become a significant reputational issue when its environmental consequences entered public view.

    It also raised a broader question for the industry. If destroying products becomes difficult to defend publicly, what alternatives can preserve commercial value without creating unnecessary waste?

    Richemont and the Cost of Protecting Watch Prices

    The issue has also surfaced in luxury watchmaking.

    In May 2018, reporting by The Guardian revealed that Swiss luxury group Richemont had bought back and destroyed nearly €500 million worth of watches over two years, including unsold timepieces from brands within its portfolio, such as Cartier. The company had been responding to excess inventory and concerns that unwanted watches could enter the grey market at substantial discounts.

    According to the contemporaneous report, the group bought back €278 million of Cartier watches in 2016–17 and a further €203 million of unsold watches in the following year. The timepieces were dismantled and recycled.

    The distinction between retail value, accounting value and the ultimate economic cost is important. The headline figure represents the reported value of the watches involved in the buyback and destruction process; it should not be treated as an equivalent amount of cash simply burned or as a measure of Richemont’s current practices.

    The case demonstrates the particular challenge of managing inventory in a market where perceived value is closely connected to pricing and distribution. A watch may retain valuable materials and exceptional mechanical craftsmanship while becoming difficult to sell through a particular channel without undermining the brand’s intended price positioning.

    Richemont’s experience also illustrates the commercial risk of overstocking. The group was not merely dealing with unwanted objects; it was addressing inventory that had accumulated across its distribution network and threatened to enter unauthorised discount channels.

    The broader lesson is that controlling distribution may protect a brand’s positioning in the short term, but large-scale excess inventory can create costs of its own. Better forecasting and more disciplined production may be more sustainable solutions than repeatedly correcting the problem after products have already been made.
    The Environmental Cost of Unsold Luxury

    Every finished product represents a chain of resources. Fibres, leather, metals, packaging, water, energy, transport and skilled labour are invested long before an item reaches a boutique. When a usable product is destroyed before being worn or used, those resources have been consumed without delivering the intended use of the product.

    The wider textile industry provides an indication of the scale of the problem.

    The European Environment Agency estimates that 4–9% of textile products placed on the European market are destroyed before use, equivalent to approximately 264,000–594,000 tonnes annually. Its research also estimates that around one-third of clothing returned after online purchases is ultimately destroyed on average.

    These findings come from the EEA’s analysis of the destruction of returned and unsold textiles in Europe’s circular economy.

    These are estimates for the wider textile market, not luxury brands alone. Available public data do not establish what proportion of the total is attributable specifically to luxury houses. The figures should therefore be understood as evidence of a systemic textile-waste problem rather than a measurement of luxury’s individual contribution.

    The environmental consequences also extend beyond the act of disposal. Manufacturing products that are never used creates avoidable pressure on resources and generates emissions throughout the supply chain. Recycling can recover some materials, but it does not necessarily recover the energy, labour and resources invested in making the original product.

    For an industry that often promotes durability, repair and timeless design, this creates a fundamental tension. The value proposition of luxury rests partly on the idea that a product should last. Destroying usable goods before they have served their purpose challenges that promise.

    The most effective response is therefore not simply to find a better way to dispose of excess stock. It is to reduce the amount of excess stock created in the first place.

    A Luxury Market Under Pressure

    The issue is becoming more commercially relevant as luxury growth becomes harder to sustain.

    In its June 2026 update, Bain & Company and Altagamma estimated that the global personal luxury goods market was worth €358 billion in 2025. The market declined by 2% at current exchange rates but grew by 1% at constant exchange rates. For 2026, the firms forecast a recovery of 2–4%, placing the market between €365 billion and €373 billion under their base-case scenario.

    The forecast suggests a market stabilising after a difficult period, rather than returning to effortless growth. Performance remains uneven across brands, regions and categories.

    Read Bain & Company’s 2026 luxury-market outlook.

    Reporting on the same research, Reuters noted that the luxury industry had lost approximately 70 million consumers since 2022, with price increases and a greater concentration on high-spending customers contributing to a narrower customer base. The report also highlighted the growing role of the second-hand market, with roughly half of luxury shoppers consulting resale before buying new products.

    Read Reuters’ analysis of the luxury market in 2026.

    These developments do not prove that luxury brands are destroying more products. They do, however, make inventory management more important.

    When customers become more selective, resale becomes more visible and growth slows, brands face greater pressure to align production with actual demand. Products that fail to sell represent not only a potential environmental liability but also capital tied up in stock, storage and distribution.

    The industry must therefore confront two related questions: how can brands protect the value of their products, and how can they avoid manufacturing more than the market is prepared to absorb?

    The answer may lie in a more disciplined definition of exclusivity — one based on product quality, design and enduring desirability rather than the management of unwanted inventory after the fact.
    The EU’s New Rules Change the Equation

    The debate is no longer limited to consumer pressure and voluntary sustainability commitments. Regulation has begun to change the options available to companies.

    On 19 July 2026, a new European Union measure under the Ecodesign for Sustainable Products Regulation began prohibiting large companies operating in the EU from destroying unsold clothing, clothing accessories and footwear. Medium-sized companies are scheduled to become subject to the same rules from 2030.

    Under the measure, businesses must prioritise keeping products in use. This can include selling goods through existing or alternative channels, donating suitable products, or preparing them for reuse through repair, refurbishment or remanufacturing.

    Destruction remains possible in specified circumstances, including certain cases involving unsafe, damaged or counterfeit goods, intellectual-property infringement, or products rejected by eligible donation schemes. Applicable requirements and exemptions must be followed.

    The European Commission has outlined the measure and its scope in its official announcement on the ban on destroying unsold clothes and shoes.

    The regulation does not apply universally to every luxury product or every company worldwide. Its immediate scope concerns specified categories of clothing, clothing accessories and footwear within the EU framework. Watches, jewellery, fragrances and other product categories should not automatically be assumed to fall under the same destruction prohibition.

    For luxury fashion houses operating in Europe, however, the change is significant. Destruction can no longer be treated simply as a discretionary inventory-management choice for the products covered by the rules. Businesses must consider viable routes for keeping unsold goods in circulation and comply with the relevant documentation and reporting requirements.

    The regulatory shift also creates a commercial incentive to address the problem earlier. Better forecasting, tighter production planning, repair programmes and structured resale channels can reduce the amount of inventory that reaches the point at which it is difficult to sell.

    The direction is clear: the cost of excess inventory is increasingly measured not only in financial terms, but also in environmental impact and regulatory exposure.

    What Luxury Brands Can Do Instead

    There is no single solution for every unsold product. A returned handbag, an outdated seasonal garment, a damaged shoe and a defective cosmetic product each present different challenges. Nevertheless, several approaches can reduce the need for destruction.

    Produce more precisely. Improved demand forecasting, smaller initial production runs and more responsive replenishment can reduce the risk of creating surplus inventory. The aim is not to eliminate every forecasting error, but to prevent avoidable overproduction.

    Create controlled second-life channels. Authorised resale, repair, refurbishment and selected outlet channels can keep products in circulation while allowing brands to retain appropriate standards of authentication, service and presentation.

    Make donation operationally viable. Donation can provide a route for suitable unsold goods, but it requires reliable partners, appropriate product condition and careful logistics. It is not a universal answer for every product category.

    Design for longevity and repair. Durable construction, replaceable components and access to repair services can extend the useful life of products and preserve value beyond the first sale.

    Recover materials where reuse is not possible. Recycling and material recovery can help reduce waste, although their environmental benefits depend on the materials involved and the effectiveness of the recovery process.

    Improve transparency. More consistent disclosure about unsold inventory, reuse, donation, recycling and disposal would allow consumers, investors and regulators to evaluate corporate sustainability commitments against operational outcomes.

    These measures will not remove every commercial constraint. Luxury brands must still protect intellectual property, product safety and the integrity of their distribution networks. But those objectives do not necessarily require usable goods to be destroyed.

    The more ambitious solution is to treat unsold inventory as a problem to prevent, not merely a liability to manage.
    What Is Exclusivity Really Worth?

    Luxury has always depended on a carefully managed relationship between scarcity and desire. A product can become exceptional because of its craftsmanship, its history, its design or the meaning consumers attach to it. Its value does not have to depend on the disappearance of everything that fails to sell.

    The historical cases of Burberry and Richemont demonstrate that the destruction of unsold goods has been a real, documented practice within the luxury sector. The European Union’s new restrictions show that the issue has moved beyond reputational controversy into regulation. Meanwhile, a more selective market makes disciplined production and inventory management increasingly important to the industry’s commercial future.

    The challenge is not to make every luxury product permanently available at a discount. It is to build a system in which products can retain value even when they do not sell at the intended price, and in which brands take responsibility for the resources invested in their creation.

    Luxury can protect its identity through quality, craftsmanship, service, innovation and genuine desirability. It can control distribution without treating every unsold item as a threat. And it can pursue exclusivity without assuming that waste is an unavoidable cost of doing business.

    Ultimately, a truly exceptional product should justify its worth through what it is — not through what a brand must destroy to protect its price.

    Because when exclusivity comes at the expense of usable products, the question is no longer only what luxury is worth. It is what the industry is willing to waste to preserve its value.

    INSYDE Magazine — the top luxury magazine in Bangalore

    Luxury. Culture. The People Shaping What Comes Next.
  • THE LUXURY EMPIRE LOSING ITS CHARM?

    THE LUXURY EMPIRE LOSING ITS CHARM?

    Inside the Global Slowdown Reshaping the World’s Most Coveted Brands

    From weakening fashion sales and rising consumer selectivity to the shifting economics of exclusivity, the world’s luxury giants are confronting a difficult question: what happens when the desire to own luxury begins to fade?

    INSYDE Magazine | Luxury & Business |


    Luxury has always sold a fantasy.

    A handbag is never just a handbag. A watch is never simply a mechanism for measuring time. A hotel suite, a couture gown or a piece of fine jewellery promises something beyond its physical form: status, craftsmanship, heritage, belonging and the rare feeling of possessing something exceptional.

    For decades, the world’s most powerful luxury houses have built extraordinary businesses around that promise. Their names became cultural shorthand for success. Their boutiques became destinations. Their products became objects of desire, often commanding prices far removed from the cost of the materials used to make them.

    But in October 2026, the global luxury industry finds itself confronting a less glamorous reality.

    Growth has become harder to secure. Some of the world’s largest fashion businesses are struggling to regain momentum. Consumer behaviour is changing, demand is shifting between regions, and the industry’s most influential companies are facing renewed scrutiny over their ability to justify premium prices.

    The numbers tell a complicated story. This is not the collapse of luxury, nor the disappearance of wealthy consumers. It is a market undergoing a reset — one that is exposing the differences between brands that continue to inspire desire and those finding it increasingly difficult to sustain it.

    At the centre of the debate is a question that goes beyond quarterly earnings.

    Has luxury become so expensive, so ubiquitous and so dependent on its own prestige that parts of the industry are beginning to lose the very charm that made them desirable?

    THE NUMBERS BEHIND THE GLAMOUR

    The global luxury economy remains enormous. Yet its scale can obscure the pressure emerging within individual categories.

    According to Bain & Company and Altagamma’s June 2026 luxury market update, worldwide luxury spending reached approximately €1.443 trillion in 2025. This figure covers a broad range of luxury markets, including personal goods and experiences; it should not be confused with spending on designer fashion and accessories alone.

    The personal luxury goods market — covering categories such as fashion, leather goods, jewellery, watches and beauty — was estimated at approximately €358 billion in 2025. At current exchange rates, that represented a 2% decline from 2024, although the market grew by 1% at constant exchange rates.

    For 2026, Bain and Altagamma’s base-case forecast anticipates growth of 2% to 4%, potentially bringing personal luxury goods spending to between €365 billion and €373 billion.

    That is a forecast, not a confirmed year-end result. It suggests that the market could return to modest growth, but it does not imply that every luxury company will benefit equally.

    The distinction is crucial. An industry can remain worth hundreds of billions of euros while major brands experience falling sales, pressure on profitability and increasingly selective consumers.

    The latest results from LVMH, the luxury group behind Louis Vuitton, Dior, Tiffany & Co., Bulgari and other major names, illustrate the challenge.

    On 12 October 2026, LVMH reported €18.5 billion in third-quarter revenue, with organic revenue growth of just 1% compared with the same period a year earlier. For the first nine months of 2026, group revenue reached €57.1 billion, representing 2% organic growth.

    The more revealing figure came from its core fashion and leather goods division. Organic revenue in that business fell 5% in the third quarter. Across the first nine months of 2026, the division’s reported revenue declined 4% year on year, while organic revenue fell 2%.

    These are not interchangeable measurements: reported revenue reflects factors including currency movements, while organic growth attempts to assess underlying business performance.

    Nevertheless, the direction is clear. One of the world’s most influential luxury groups is finding that its largest fashion businesses cannot rely on the industry’s historic momentum.

    The company’s results also showed that performance differed by region. LVMH described a less buoyant environment in China, while the United States, Europe and Japan recorded growth during the quarter.

    The lesson is not that luxury has stopped selling. It is that the industry can no longer assume that prestige alone will guarantee growth.

    Source: LVMH, third-quarter 2026 results.

    WHEN EXCLUSIVITY BECOMES A PRICE TAG

    Luxury has always depended on pricing power. A product that commands a premium can signal rarity, superior craftsmanship, design excellence and the authority of a recognised house.

    But pricing power is not limitless.

    For years, price increases have been an important part of the commercial strategies pursued across luxury. When demand is strong and customers remain willing to pay, raising prices can support revenue and reinforce a brand’s positioning.

    The difficulty emerges when the price rises faster than the customer’s perception of value.

    A customer purchasing a luxury handbag is not paying only for leather, stitching or hardware. They are paying for the design, the name, the service, the experience and the emotional satisfaction attached to the purchase.

    When prices rise substantially, the brand must continue to justify the entire proposition.

    Is the craftsmanship exceptional? Is the design distinctive? Does the product feel special enough to deserve its price? Will it remain desirable beyond the current season? Does the experience justify the expense?

    For some consumers, the answer remains an emphatic yes. For others, the calculation is becoming more difficult.

    This is particularly relevant for aspirational buyers: consumers who can afford selected luxury products but cannot treat every purchase as financially insignificant.

    For them, a handbag, watch or pair of shoes is a considered decision. When the price increases, they may postpone the purchase, choose a pre-owned alternative or redirect their money towards travel, dining and other experiences.

    Luxury brands therefore face a delicate balancing act. Lowering prices indiscriminately could undermine exclusivity, but continuing to raise them without strengthening perceived value risks making the customer feel that the brand is asking for more while offering less in return.

    The problem is not the existence of high prices. Luxury is supposed to be expensive.

    The problem arises when expensive becomes the most convincing thing a product has to offer.

    THE CUSTOMER LUXURY CANNOT AFFORD TO FORGET

    The wealthiest customers remain important to luxury. They support high jewellery, couture, rare watches, bespoke services and limited-edition creations.

    But the global luxury market was never built exclusively on the spending of billionaires.

    Aspirational consumers have helped turn luxury houses into cultural institutions. They buy fragrances, beauty products, accessories and entry-level leather goods. They follow fashion campaigns, recognise creative directors, discuss collections and introduce brands to new audiences.

    Their individual spending may be lower, but their collective influence is significant.

    That is why the shrinking or weakening of this customer base deserves attention.

    In June 2026, Reuters reported on Bain’s estimate that the luxury industry had lost approximately 70 million consumers since 2022. The figure reflects a reported industry estimate; it should not be interpreted as proof that every one of those consumers has permanently abandoned luxury.

    It does, however, highlight the challenge facing brands that have increasingly concentrated on their highest-spending clients.

    A company can become more exclusive in its advertising while simultaneously reducing the number of people who feel connected to it.

    That strategy may improve the economics of individual transactions in the short term, but it can also narrow the audience that sustains cultural relevance over time.

    Younger consumers, in particular, encounter luxury differently from previous generations. They can compare prices, research craftsmanship, follow independent designers, browse resale platforms and question a brand’s claims before entering a boutique.

    They are not necessarily rejecting luxury. They are becoming more selective about what deserves their money.

    For the industry, the challenge is to preserve exclusivity without allowing it to become indifference.

    CHINA AND THE FRAGILE GEOGRAPHY OF LUXURY

    Luxury is a global business, but its fortunes have long been influenced by a handful of powerful consumer markets.

    China became one of the industry’s most important growth engines, supported by rising wealth, international travel and strong demand for European fashion, jewellery and watches.

    That made the Chinese consumer central to the expansion strategies of many international luxury houses.

    But demand does not move in a straight line.

    LVMH’s October 2026 results pointed to a less buoyant environment in China, helping explain the pressure on its fashion and leather goods division. The company reported growth in the United States, Europe and Japan, but that strength did not remove the overall weakness in its core fashion business.

    The wider significance is that global luxury brands must manage different economic conditions, consumer expectations and cultural dynamics simultaneously.

    When demand weakens in one major region, companies with concentrated exposure can face immediate pressure. When several markets become less predictable at once, the challenge becomes more complicated.

    This is not an argument for abandoning China or replacing it with another single growth engine. It is an argument for a more balanced global strategy.

    The United States can offer opportunities, but it is not a guaranteed substitute for every lost sale elsewhere. Europe remains important, particularly for local consumers and international visitors. Japan has its own demand patterns, while other Asian markets continue to evolve.

    The strongest brands will be those that understand their customers market by market rather than assuming that a global reputation automatically translates into uniform demand.

    In luxury, geography is no longer simply a question of where a brand opens its next boutique. It is a question of where desire is growing, where it is weakening and why.

    NOT EVERY LUXURY EMPIRE IS LOSING ITS CHARM

    A slowdown story becomes misleading when it treats every category as though it were experiencing the same problems.

    Luxury fashion, jewellery, watches, beauty, hospitality and other premium experiences operate with different economics. Their customers buy for different reasons, and their products follow different purchase cycles.

    Richemont provides an important counterexample.

    The Swiss group, whose jewellery maisons include Cartier, Van Cleef & Arpels, Buccellati and Vhernier, reported €6.329 billion in sales for the quarter ended 30 June 2026, an increase of 20% at constant exchange rates and 17% at actual exchange rates.

    Its jewellery maisons recorded a 24% increase at constant exchange rates, while its specialist watchmakers grew by 8%.

    The figures cover Richemont’s first fiscal quarter, which ended in June. They are not directly comparable with LVMH’s July–September third-quarter results because the reporting periods and business portfolios differ.

    Even with that qualification, Richemont’s performance demonstrates an essential point: demand remains strong in parts of luxury, particularly where products continue to attract customers through recognisable design, craftsmanship and enduring desirability.

    Jewellery also serves different purposes from seasonal fashion. It can mark significant life events, function as a gift, become a collectible or be passed between generations. Established jewellery houses have built long histories around signature designs and a distinctive visual language.

    That does not make jewellery immune to economic pressure. Nor does one strong quarter guarantee future growth.

    It does show why the industry should not be described as a single market moving in one direction.

    The more useful question is which brands and categories are sustaining their appeal — and what they are doing differently.

    Source: Richemont, first-quarter results for the period ended 30 June 2026.

    FROM OWNING LUXURY TO EXPERIENCING IT

    A different idea of luxury is gaining ground: one in which the most desirable purchase is not necessarily an object.

    High-end hospitality, fine dining, private travel, wellness retreats and cultural experiences offer something physical products cannot always replicate — a memory, a sense of access, personal attention or time spent outside ordinary life.

    Bain and Altagamma’s June 2026 update identifies experiences as an area of relative strength, with luxury experiences such as hospitality and restaurants, alongside selected high-value assets, expected to grow by around 4%.

    That forecast should be read as an industry outlook, not a final result for every experience-led business.

    Nevertheless, the direction is important.

    A handbag can be photographed and compared. A watch can be researched on the secondary market. But a private journey, an exceptional meal or a carefully designed hospitality experience depends on the quality of its execution, the people involved and the atmosphere created.

    For some consumers, these experiences are becoming a more compelling use of discretionary spending than another recognisable product.

    This does not mean that physical luxury is disappearing. Fashion, jewellery and watches remain central to the industry. Instead, the definition of luxury is expanding, and brands must decide how they fit into a consumer’s wider idea of a desirable life.

    The opportunity extends beyond hotels and restaurants. A fashion house can build a cultural world around its products. A jewellery brand can deepen its connection to craftsmanship and heritage. A luxury retailer can turn a store visit into a personalised experience rather than a simple transaction.

    The brands that understand the emotional value of an experience may discover new ways to sustain the desirability of their products.

    Luxury has always sold more than objects. The market is increasingly asking brands to prove it.

    Source: Bain & Company and Altagamma’s 2026 market update.

    THE SECOND-HAND MARKET IS CHANGING THE CONVERSATION

    The rise of pre-owned luxury has introduced another variable into the industry’s relationship with value.

    The secondary market gives consumers access to established brands at different price points. It also allows collectors to buy, sell and trade products beyond their original retail environment.

    For a buyer considering a new luxury item, the decision is no longer limited to comparing it with other new products. The buyer can examine pre-owned alternatives, investigate resale prices and consider whether the purchase is likely to retain its appeal.

    Bain and Altagamma’s 2026 research found that around half of luxury shoppers consult the second-hand market before buying new, while approximately half already use AI during their purchase journey.

    These findings suggest that technology and resale are no longer peripheral to luxury shopping. They are becoming part of how consumers discover products, compare options and evaluate value.

    For brands, the implications are mixed.

    A strong secondary market can reinforce a product’s reputation for longevity, desirability and collectability. It can also introduce new consumers to a brand who may later purchase directly from the company.

    But resale makes it easier for shoppers to question the relationship between a product’s original price and its perceived value. A consumer may decide that a pre-owned piece from a more prestigious house offers a better proposition than a new product from a less established competitor.

    That places greater importance on quality, durability, authenticity and timeless design.

    Luxury houses cannot control every transaction in the secondary market, but they can influence the qualities that make their products desirable long after the first sale.

    The real test is whether a product remains compelling when the customer has more information, more alternatives and fewer reasons to buy impulsively.

    Source: Bain & Company and Altagamma, 2026 luxury market research.

    INDIA: A PROMISING MARKET WITH REAL CONSTRAINTS

    India presents an important opportunity for global luxury, but it should not be treated as an automatic solution to the industry’s challenges elsewhere.

    The country’s expanding affluent population, entrepreneurial wealth and growing appetite for premium products have attracted international brands. Yet translating that interest into a mature luxury market requires more than consumer aspiration.

    A March 2026 Reuters report on India’s luxury retail-space shortage highlighted a major constraint: the limited availability of high-quality luxury retail destinations.

    The report described a market in which global brands were competing for a relatively small number of suitable locations, while new retail developments would take time to deliver.

    This creates a structural challenge. A growing customer base cannot be fully served without the right stores, trained staff, reliable service, appropriate locations and the broader retail infrastructure that supports a premium shopping experience.

    Import duties and differences in pricing can also influence where affluent Indian consumers choose to shop.

    For international luxury houses, India therefore represents a long-term strategic opportunity rather than an immediate substitute for weaker demand elsewhere.

    The opportunity is also relevant to Indian luxury businesses. Brands that understand local craftsmanship, cultural heritage and changing consumer expectations can develop propositions that are distinctive rather than simply imported.

    But growth will depend on execution. Strong demand must translate into repeat purchases, trusted customer relationships and retail experiences that meet the expectations attached to a premium price.

    India may become a more significant force in the global luxury landscape. Its potential, however, should be assessed through market evidence rather than optimism alone.

    THE NEXT ERA OF LUXURY WILL BE WON ON VALUE

    The industry’s next chapter will not be decided by price increases alone.

    Luxury houses still possess formidable advantages: heritage, craftsmanship, design, distribution, cultural influence and relationships with wealthy customers. The current slowdown does not erase those strengths.

    It does make the quality of their execution more important.

    First, brands must make their prices mean something. A premium must be supported by product quality, distinctive design, materials, service and a credible story. Price alone cannot create enduring desire.

    Second, customer relationships must extend beyond the wealthiest buyers. High-spending clients remain essential, but younger and aspirational consumers represent a potential future audience. Brands must find ways to remain relevant without abandoning the exclusivity that defines them.

    Third, creativity must do more than generate attention. Campaigns, celebrity partnerships and cultural visibility can make a brand famous, but fame does not automatically create loyalty. Products must still be desirable when the campaign ends.

    Fourth, companies must understand the new shopping journey. Consumers increasingly compare products, explore resale platforms and use digital tools before making decisions. A brand’s proposition must remain convincing beyond its own advertising and retail environment.

    Finally, luxury businesses must understand what customers are actually buying. Sometimes it is craftsmanship. Sometimes it is status, rarity, personal expression or access to a particular world. The strongest brands understand these motivations and deliver them consistently.

    The winners will not necessarily be the brands that become the most expensive. They may be the brands that give consumers the clearest reason to believe their products are exceptional.

    THE LAST WORD

    Luxury is not dead. But the old assumption that prestige can sustain growth indefinitely is being tested.

    The global market remains vast, and the latest industry forecasts point towards modest growth in personal luxury goods during 2026. Yet the recovery is uneven. LVMH’s fashion and leather goods division is under pressure, while Richemont’s jewellery maisons have reported strong growth. Experiences and the secondary market are reshaping how consumers think about luxury, and brands are being forced to compete for attention in a more informed and selective marketplace.

    Together, these developments point towards a more demanding luxury economy — one in which recognition alone may not be enough, price increases require stronger justification, and loyalty must be earned rather than assumed.

    For decades, luxury sold the promise of something beyond the ordinary. The next era will depend on whether that promise still feels extraordinary.

    Because the greatest threat to a luxury empire is not simply a weaker quarter or a slower market.

    It is the moment a customer looks at something once considered irresistible — and decides they can live without it.


    INSYDE MAGAZINE

    Luxury. Culture. The People Shaping What Comes Next.
    No.1 Luxury Magazine In Bengaluru
    www.insydemag.com

  • BEAUTY. BILLIONS. & INFLUENCE.

    BEAUTY. BILLIONS. & INFLUENCE.

    How celebrity founders turned beauty, fame and influence into commercial power.

    BY INSYDE | BEAUTY & BUSINESS

    There was a time when a celebrity’s relationship with beauty was simple. A famous face appeared in a campaign, a name went on a bottle, and a brand paid for the privilege of borrowing a little of that person’s desirability.

    Today, some celebrities are doing something considerably more ambitious.

    They are building the brands themselves.

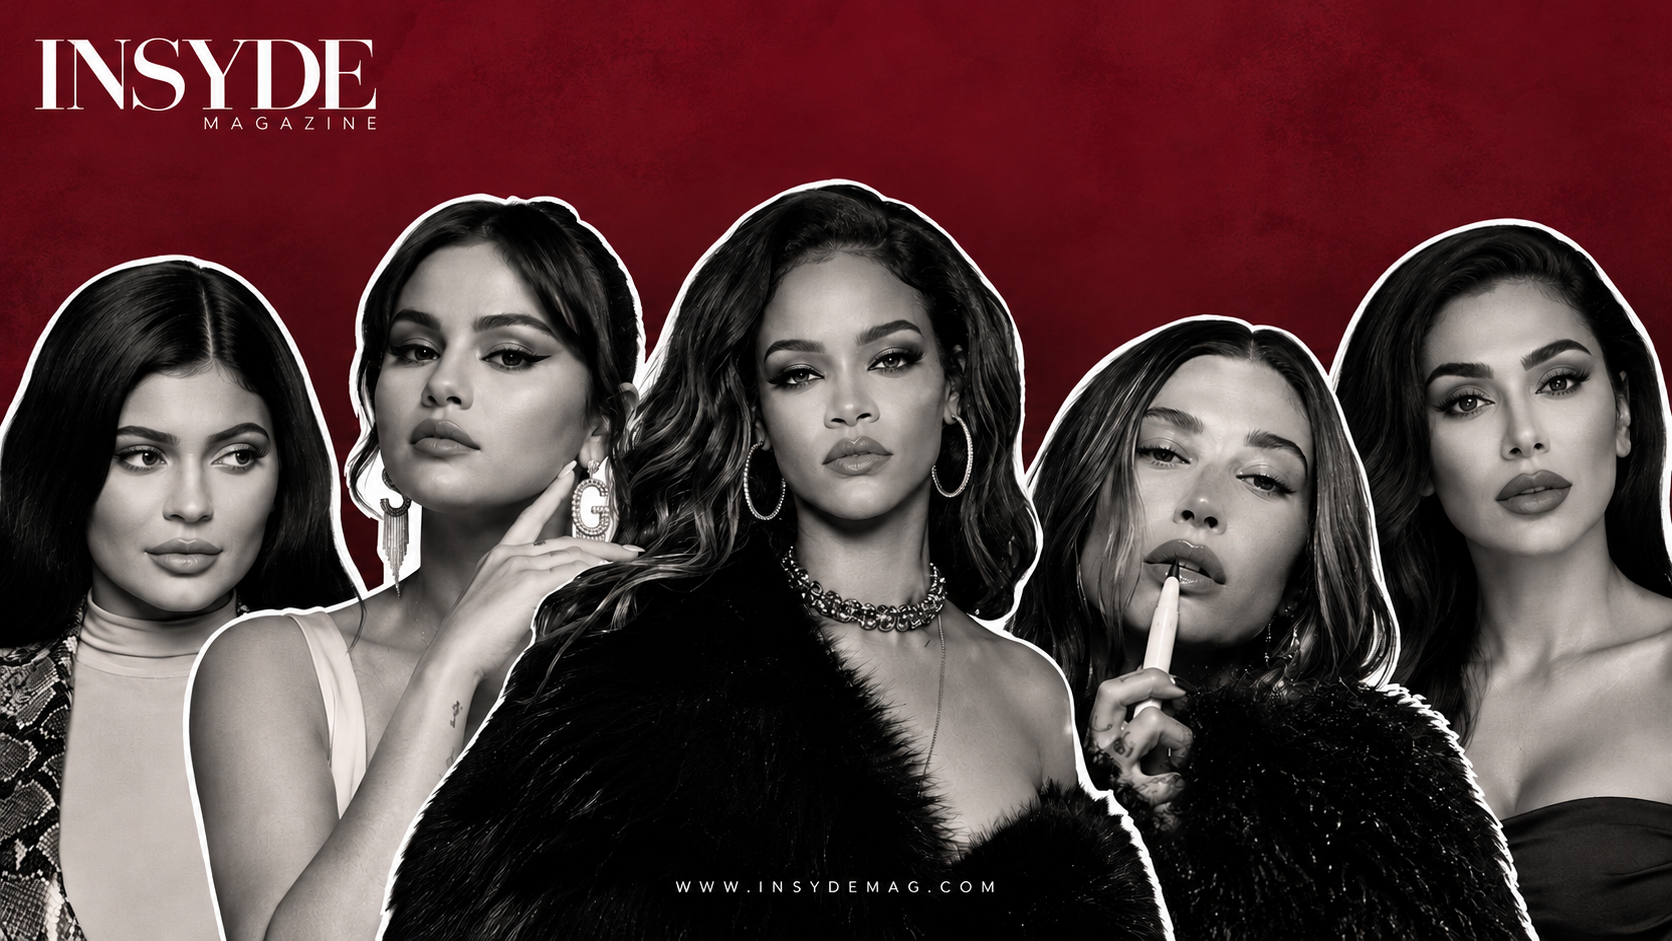
    Rihanna helped turn Fenty Beauty into a global cosmetics business. Selena Gomez built Rare Beauty around a distinctive philosophy of self-expression. Kylie Jenner transformed social-media attention into a cosmetics company. Hailey Bieber developed Rhode into an acquisition target for one of the beauty industry’s major players. Huda Kattan turned beauty expertise and an online audience into an international brand.

    These are not simply celebrity endorsements. They are businesses with products, distribution networks, commercial strategies and, in some cases, billion-dollar valuations or acquisition deals.

    The distinction matters.

    In October 2026, Fortune, reporting on Traackr’s Creator Advantage 2026 research, highlighted how celebrity-founded companies had become powerful participants in the beauty economy. Five of the ten leading US beauty brands ranked by creator-marketing performance in 2025 were celebrity-founded, including Kylie Cosmetics, Rare Beauty, Rhode, R.E.M. Beauty and Huda Beauty.

    That is a measure of marketing performance, not a ranking of revenue or profitability. But it reveals something important about the modern consumer market: influence is no longer merely an advertising tool. In the right hands, it can become a competitive advantage.

    The financial results make the story even more interesting.

    According to Reuters’ reporting on Fenty Beauty, the brand generated approximately $450 million in net sales in 2024. Rhode recorded $212 million in net sales during the twelve months ended March 31, 2025, before its acquisition by e.l.f. Beauty. Rare Beauty has also been associated with a reported valuation estimate of approximately $2.7 billion in 2026.

    These figures measure different things. Sales are not valuations, acquisition prices are not guaranteed cash payouts, and the value of a company is not the same as its founder’s personal fortune.

    But together, they point towards a larger shift.

    Celebrity beauty is no longer simply about putting a famous face on a product. It is about turning identity, cultural relevance, product development and direct access to consumers into businesses with lasting value.

    The question is no longer whether a celebrity can sell a lipstick.

    It is whether that celebrity can build a beauty company that people continue to buy from long after the initial fascination fades.

    01 — FENTY BEAUTY: WHEN INCLUSIVITY BECAME A BUSINESS STRATEGY

    When Rihanna launched Fenty Beauty in September 2017, its initial foundation range of 40 shades made inclusivity a defining part of its identity.

    The significance was not that no beauty brand had previously offered a wide shade range. It was that Fenty brought the conversation into the centre of a highly visible global launch, making the experiences of consumers who struggled to find suitable foundation difficult for the wider industry to ignore.

    Its proposition was clear: more consumers should be able to find products that work for them.

    Rihanna’s cultural reach gave the launch extraordinary visibility, while the brand’s partnership with LVMH’s Kendo division provided the infrastructure of an established beauty business.

    The financial figures demonstrate the scale that followed.

    Reuters reported in October 2025 that Fenty Beauty generated approximately $450 million in net sales in 2024. Sources cited in the same report estimated its valuation at between $1 billion and $2 billion. That valuation was an estimate, not a publicly disclosed transaction price.

    The distinction matters. Sales describe the revenue generated by a business over a period; valuation estimates what that business might be worth.

    Fenty’s wider influence is perhaps more revealing than either number. Its positioning helped make inclusive shade ranges a much more prominent part of the beauty industry’s commercial conversation.

    The business lesson is straightforward. Rihanna’s fame helped Fenty attract attention, but the company needed a product proposition that consumers could understand and purchase.

    THE INSYDE OBSERVATION: Influence becomes more powerful when it is attached to a proposition the market has a reason to believe in.

    02 — RARE BEAUTY: THE POWER OF A POINT OF VIEW

    Selena Gomez launched Rare Beauty in 2020 with an identity that extended beyond the products themselves.

    The brand’s messaging around self-expression and a less perfection-driven understanding of beauty gave it a recognisable position in a crowded market. Its products, communications and social-impact commitments helped establish an identity that consumers could connect with beyond the founder’s celebrity.

    That distinction matters in beauty, where packaging, product formats and trends can be replicated quickly.

    A clear point of view gives a brand something more durable to build around.

    Rare Beauty has become a significant participant in creator-led beauty. Its position among the leading brands in Traackr’s 2026 creator-marketing analysis demonstrates the scale of its digital and cultural relevance.

    Financially, the company has also attracted substantial private-market estimates. Fortune’s October 2026 analysis reported an estimated valuation of approximately $2.7 billion. This should be understood as a reported estimate, not a confirmed transaction price or an independently disclosed current valuation.

    It would be misleading to equate that figure with Gomez’s personal wealth. A company’s value belongs to the business and its shareholders; the founder’s financial position depends on ownership and other assets.

    Rare Beauty’s challenge is to maintain its identity while growing distribution, introducing new products and sustaining customer loyalty.

    The brand’s success suggests that a celebrity-led company can offer more than a famous face. It can create a coherent perspective on beauty that helps consumers understand what makes it different.

    THE INSYDE OBSERVATION: A recognisable philosophy can become a commercial asset when it is supported by products consumers want to use.

    03 — KYLIE COSMETICS: FROM SOCIAL-MEDIA ATTENTION TO CORPORATE SCALE

    Kylie Jenner’s cosmetics business began with one of the most recognisable categories in beauty: lip products.

    Kylie Lip Kits launched in 2015, drawing on Jenner’s public image and the attention surrounding her makeup looks. The products gave an existing audience something tangible to purchase.

    The model was powerful because the launch did not have to build awareness from zero. Jenner already had an audience, a recognisable aesthetic and a direct channel through which to communicate with potential customers.

    The business subsequently expanded beyond lip kits. In 2019, Coty acquired a 51% stake in the company for $600 million, implying an approximate $1.2 billion valuation at the time. This was a historical transaction, not a verified current valuation.

    Coty’s subsequent reporting offers a more recent view of the brand. In March 2025, the company said Kylie Cosmetics had grown 1.5 times over the preceding two years. The brand has continued to operate within Coty’s prestige beauty portfolio.

    Coty does not disclose a comparable standalone current valuation for Kylie Cosmetics in the reporting used for this article. Nor can the company’s valuation or sales be used as a direct measure of Jenner’s personal wealth.

    The corporate partnership changed the nature of the business. Kylie Cosmetics became part of a larger beauty portfolio with access to established distribution, marketing and operational capabilities.

    That brings advantages, but it also means the founder’s role and ownership must be distinguished from the company’s overall performance.

    Kylie Cosmetics demonstrates how a celebrity’s audience can accelerate a product launch. Its longer-term commercial value depends on whether the brand can keep its products relevant after the initial excitement.

    THE INSYDE OBSERVATION: An audience can give a business its first customers. It cannot guarantee its next decade of growth.

    04 — RHODE: THE VALUE OF A CLEAR AESTHETIC

    Hailey Bieber’s Rhode entered the beauty market with a focused skincare proposition, restrained packaging and an immediately recognisable visual identity.

    Rather than launching with an enormous assortment, Rhode concentrated on skin-focused products and an aesthetic that translated naturally into social content. Its presentation made products recognisable in photographs and routines easy to communicate.

    The brand’s commercial trajectory culminated in a major transaction.

    In May 2025, e.l.f. Beauty announced an agreement to acquire Rhode for $800 million at closing, plus up to $200 million in potential earn-out payments. The acquisition closed on August 5, 2025.

    Rhode had generated $212 million in net sales in the twelve months ended March 31, 2025, according to e.l.f. Beauty’s acquisition announcement.

    The maximum announced deal value was therefore $1 billion, not a guaranteed $1 billion cash payment to Bieber. The transaction involved cash, shares and potential performance-linked consideration.

    In its fiscal 2026 annual filing, e.l.f. Beauty recorded total acquisition consideration of approximately $897.5 million, including the estimated value of potential earn-out consideration at that time. The filing also reported that Rhode contributed $293.5 million in net sales to e.l.f.’s consolidated results between the acquisition date and March 31, 2026. This latter figure covers a different reporting period and should not be confused with Rhode’s standalone sales before the acquisition.

    The details can be verified in e.l.f. Beauty’s fiscal 2026 SEC filing.

    The transaction demonstrates why established beauty companies pay attention to fast-growing independent brands. An acquirer can bring distribution, retail relationships and international scale to a company that has already demonstrated consumer demand.

    After an acquisition, the challenge changes. A brand must preserve the qualities that made it distinctive while expanding its reach and operating within a larger corporate structure.

    Rhode’s story is not simply about a celebrity creating a successful skincare line. It is about a relatively young company developing enough commercial value to attract a major strategic buyer.

    THE INSYDE OBSERVATION: A focused product range and coherent aesthetic can be commercially powerful when they are supported by genuine demand and operational execution.

    05 — HUDA BEAUTY: WHEN BEAUTY EXPERTISE BECOMES AN EMPIRE

    Huda Kattan’s path into beauty began with expertise and content rather than a traditional entertainment career.

    Through beauty tutorials and product knowledge, she built an audience interested in makeup itself. Huda Beauty emerged from that relationship, launching with false eyelashes in 2013 before expanding into a wider cosmetics business.

    The distinction is important. Kattan was not simply placing her name on a product. Her existing connection with beauty consumers helped establish the company’s initial credibility.

    But turning an audience into a global brand required more than content. It required product development, manufacturing, distribution, inventory management and the ability to sell consistently across markets.

    Huda Beauty became a significant name in the international cosmetics market. It also appeared among the leading brands in Traackr’s creator-marketing analysis reported by Fortune in October 2026.

    Its financial history, however, requires careful treatment. Historical reports have associated the company with a valuation of around $1 billion in 2017, but that figure should not be presented as a verified current valuation. A sufficiently reliable, comparable standalone 2026 revenue or valuation figure has not been established for this article.

    That limitation should not be filled with an unsupported estimate.

    Huda Beauty remains an important case study because it shows how a founder can move from content creation into a product business with an identity that extends beyond the content that first attracted consumers.

    It also highlights a broader feature of celebrity beauty: not every successful founder begins as a film star or musician. In some cases, beauty expertise and an audience built around a specific category can be the starting point.

    THE INSYDE OBSERVATION: Fame is one route into beauty. Credibility built around the category itself can be another.

    06 — THE NUMBERS BEHIND THE GLOW

    The financial evidence behind these five brands is significant, but the figures describe different things.

    Fenty Beauty — Rihanna

    Approximately $450 million in reported net sales in 2024, alongside a $1–2 billion valuation estimate reported in 2025.

    Rare Beauty — Selena Gomez

    An estimated valuation of approximately $2.7 billion reported in October 2026.

    Kylie Cosmetics — Kylie Jenner

    An implied valuation of approximately $1.2 billion when Coty acquired its 51% stake in 2019.

    Rhode — Hailey Bieber

    $212 million in net sales for the twelve months ended March 31, 2025, followed by acquisition consideration recorded at approximately $897.5 million in e.l.f. Beauty’s fiscal 2026 filing.

    Huda Beauty — Huda Kattan

    Historical valuation reports around $1 billion in 2017, with no comparable verified current standalone valuation established for this article.

    The sources for these figures include Reuters’ Fenty Beauty reporting, Fortune’s 2026 creator-economy analysis, Coty’s corporate reporting and e.l.f. Beauty’s SEC filing.

    These figures come from different dates and sources. They are not a definitive ranking of the five largest celebrity beauty companies. Fenty’s figure is annual sales; Rare Beauty’s is an estimate; Kylie Cosmetics’ figure is historical; Rhode’s is an acquisition consideration figure; and Huda Beauty’s is historical.

    A company’s valuation is not the same as its revenue. Revenue is not profit. And neither is equivalent to the founder’s personal fortune.

    Those distinctions are essential to understanding how celebrity beauty businesses create and retain wealth.

    07 — FAME IS AN ADVANTAGE. IT IS NOT A BUSINESS MODEL.

    Celebrity-founded beauty companies begin with something many new businesses spend years trying to build: attention.

    A famous founder can introduce a product to an established audience. Their personal style can help establish a visual identity, while social platforms provide channels through which customers can discover, discuss and recommend products.

    But the competitive advantage has limits.

    Products can be copied. Trends can move on. Social-media algorithms change. Consumers can lose interest. And a successful launch does not guarantee that customers will purchase again.

    The October 2026 creator-marketing analysis offers a useful perspective. Five celebrity-founded brands appeared in the top ten US beauty brands ranked by creator-marketing performance for 2025. Yet the same market contains companies that have struggled despite high-profile founders.

    Fortune reported that Gwen Stefani’s GXVE Beauty shut down in early 2026, while Drew Barrymore’s Flower Beauty ceased operations in September 2025.

    These cases demonstrate why fame and commercial durability should not be confused. A celebrity can attract attention, but a company still needs products that consumers want, an effective route to market and a reason for customers to return.

    The strongest model combines the founder’s visibility with a recognisable proposition and an organisation capable of operating beyond constant personal promotion.

    Celebrity may open the door. The business must still earn its place.

    08 — WHO REALLY OWNS THE BILLIONS?

    The phrase celebrity beauty billionaire can blur several different ideas.

    A founder may own a majority stake in a private company, a minority stake in a brand operated by a larger group, or an ownership interest that has changed through investment and acquisition. A transaction can involve cash, shares and future payments rather than a single guaranteed payout.

    Rihanna’s personal wealth, for example, cannot be calculated by treating Fenty Beauty’s reported sales as money she personally receives. Coty’s stake in Kylie Cosmetics means the brand’s historical valuation cannot simply be assigned to Jenner. Rhode’s transaction similarly included closing consideration and potential earn-outs.

    The distinction does not diminish what these founders have built. It makes the business story more meaningful.

    The important questions are how much economic value a company creates, how its ownership is structured, how much of that value the founder retains and whether the business can continue to grow.

    For a serious business editorial, those questions matter far more than a celebrity net-worth headline.

    THE INSYDE TAKE

    Beauty has always sold more than cosmetics. It sells identity, aspiration, ritual and the possibility of becoming a slightly different version of oneself.

    Celebrity-founded brands have learned to turn those ideas into businesses.

    Fenty Beauty helped bring inclusivity into the centre of the beauty conversation. Rare Beauty built a recognisable identity around self-expression. Kylie Cosmetics turned social-media attention into a business that entered a major corporate partnership. Rhode attracted an acquisition with consideration approaching the billion-dollar mark. Huda Beauty demonstrated how beauty expertise and an audience could develop into an international product company.

    Their financial stories are different. Some figures are disclosed sales; others are historical valuations, estimates or acquisition values. None should be mistaken for the founder’s personal fortune.

    But the larger lesson is consistent.

    Fame creates visibility. Influence can create demand. A recognisable identity can help a brand stand apart.

    What turns those advantages into a business is the harder work: product development, distribution, customer loyalty, operational execution and the ability to remain relevant after the first wave of attention fades.

    The next generation of celebrity beauty brands will not succeed simply because their founders are famous.

    They will succeed if consumers keep coming back.

    Because in the beauty business, the first sale may come from influence.

    The next one has to be earned.

    BEAUTY. BILLIONS. & INFLUENCE.

    INSYDE — BEAUTY, BUSINESS & CULTURE

    NO.1 LUXURY MAGAZINE IN BENGALURU

  • SAKS’ $2.7 BILLION GAMBLE

    SAKS’ $2.7 BILLION GAMBLE

    How a landmark acquisition, mounting debt and a breakdown in supplier confidence pushed an American luxury retail institution into bankruptcy — and what its restructuring reveals about the future of luxury shopping.

    Luxury has always sold more than a product. It sells access, identity and the feeling that something ordinary has been transformed into something exceptional.

    For generations, Saks Fifth Avenue understood that proposition. Its celebrated New York flagship became a symbol of American luxury shopping, connecting international fashion houses with customers who expected exceptional merchandise, personal service and an experience that extended beyond the transaction.

    Alongside Neiman Marcus and Bergdorf Goodman, Saks occupied a distinctive position in the American retail landscape. These were not simply stores selling expensive clothes. They were institutions built around the idea that how luxury is discovered and purchased matters almost as much as what is purchased.

    In 2024, the company behind Saks made a bet on that legacy.

    A $2.65 billion acquisition of Neiman Marcus Group, widely reported as a $2.7 billion deal, brought Neiman Marcus and Bergdorf Goodman under the same corporate umbrella as Saks Fifth Avenue. The ambition was to create a more powerful luxury retail group — one with greater purchasing scale, broader customer reach and the technology to compete in a rapidly changing market.

    Instead, barely thirteen months after completing the transaction, the enlarged group filed for Chapter 11 bankruptcy protection.

    The company entered bankruptcy on 13 January 2026 with approximately $3.4 billion in funded debt obligations. Supplier-payment problems and inventory shortages had become serious operational concerns. The crisis threatened the commercial relationships on which a luxury department store depends.

    Yet the story did not end with bankruptcy. On 26 June 2026, the restructured company emerged under a new corporate name: Exemplar Luxury Group, with debt reduced by nearly 75%, according to its announcement. Saks Fifth Avenue, Neiman Marcus and Bergdorf Goodman remained part of the portfolio.

    The brands survived. The financial structure that brought them together did not.

    This is the story of a luxury acquisition that promised scale but exposed financial fragility — and of an industry in which heritage, desirable merchandise and wealthy customers cannot compensate indefinitely for a business that struggles to pay its suppliers.

    THE AMBITION: BUILDING A LUXURY POWERHOUSE

    The logic behind the Neiman Marcus acquisition was easy to understand.

    Saks Fifth Avenue brought national recognition and a celebrated flagship. Neiman Marcus had a strong presence in affluent American markets, while Bergdorf Goodman occupied a particularly rarefied position in New York luxury retail. Each brand had its own identity, customer base and place in the market.

    Bringing them together promised a larger platform for selling luxury goods.

    The acquisition was announced at an enterprise value of approximately $2.65 billion in July 2024 and completed in December of that year. The resulting Saks Global combined Saks Fifth Avenue, Neiman Marcus, Bergdorf Goodman and the Saks OFF 5TH off-price business.

    The strategy centred on several potential advantages.

    A larger retailer could negotiate more effectively with suppliers, improve distribution, consolidate back-office operations and invest in technology across a broader customer base. It could also use customer data more effectively, connect online and in-store shopping, and create more opportunities for product discovery.

    The deal attracted high-profile technology partners. Amazon and Salesforce were expected to contribute expertise in areas including fulfilment, supply-chain operations and customer data.

    The ambition was not merely to own more stores. It was to create a more technologically capable luxury retailer.

    But there was a critical distinction between the strategic promise and the financial reality.

    A merger can create opportunities for efficiency. It does not guarantee that those efficiencies will arrive quickly enough, generate enough cash or outweigh the financial obligations incurred to complete the transaction.

    Luxury retail is particularly demanding in this respect. A department store must finance inventory, maintain expensive locations, employ specialist staff, invest in digital operations and settle supplier invoices. It must do all of this while keeping merchandise fresh and the customer experience compelling.

    The acquisition expanded the group’s reach. It also left the combined business needing to demonstrate that its new scale could support its financial commitments.

    That was the gamble at the heart of the deal.

    THE DEBT BEHIND THE DEAL

    The acquisition’s significance becomes clearer when viewed through the company’s balance sheet.

    Saks Global filed for bankruptcy protection in January 2026 with approximately $3.4 billion in funded debt obligations, according to reporting based on its bankruptcy filings.

    The figure matters because debt changes how a retailer can respond to pressure.

    Borrowing is not inherently a mistake. Companies use debt to acquire businesses, invest in infrastructure and finance growth. The risk arises when the cost of servicing that debt leaves insufficient flexibility to manage the operating business.

    For a department store, cash is constantly moving through a demanding cycle. Merchandise must be ordered and paid for; stores and employees must be funded; products must be sold; and the resulting cash must support both future inventory and other financial obligations.

    If too much cash is committed to debt service, the business has less room to absorb weak sales, delays in customer spending, unexpected expenses or slower-than-anticipated integration benefits.

    The problem can become self-reinforcing.

    A retailer under liquidity pressure may struggle to pay suppliers. Reduced supplier confidence can restrict merchandise availability. Less inventory can weaken sales, leaving the business with even less cash to stabilise operations.

    The result is a dangerous mismatch between the capital required to run the business and the cash available to support it.

    This is why the distinction between the acquisition price and the company’s subsequent debt burden matters. The $2.65 billion enterprise value was the reported value of the transaction; the approximately $3.4 billion in funded debt at the bankruptcy filing was a separate measure of the group’s financial obligations.

    They should not be treated as interchangeable figures.

    The broader lesson is that an acquisition’s success cannot be judged by the prestige of the assets acquired or the size of the combined organisation. It must be judged by whether the business can generate enough cash to support the structure created around it.

    In Saks’ case, that structure proved unsustainable in its existing form.

    WHEN A FINANCIAL CRISIS REACHED THE SHELVES

    A luxury department store has a problem when it cannot reliably secure the products that made it desirable in the first place.

    During the period leading up to bankruptcy, Saks Global struggled with supplier payments and merchandise availability. The consequences extended beyond its finance department. They threatened the retailer’s ability to offer customers the assortment they expected.

    For luxury houses, distribution is carefully managed. Brands choose where their products appear, how they are presented and which retail partners represent them. The relationship with a department store involves not only sales, but also positioning, service and the protection of a brand’s image.

    Payment reliability is part of that relationship.

    When a retailer falls behind on invoices, suppliers must decide how much commercial risk they are prepared to accept. They may seek stronger payment terms, limit exposure or pause shipments until outstanding concerns are resolved.

    That creates a particular problem for a multi-brand retailer.

    Its value depends on bringing desirable products together in one place. Customers may visit for a specific designer, collection or new-season item. If that merchandise is unavailable, the customer has alternatives: another department store, a competing retailer or the brand’s own boutique or website.

    The retailer loses more than a potential transaction. It risks losing the customer’s reason to return.

    Court filings reported by Reuters showed the scale of Saks Global’s exposure to luxury suppliers. Chanel was listed among its major unsecured creditors with a claim of approximately $136 million, while Kering, the owner of Gucci, was listed at around $60 million. The top 30 unsecured creditors collectively represented approximately $712 million in claims.

    These figures illustrate the scale of the commercial relationships involved. They do not establish that every listed supplier withdrew merchandise or stopped shipping.

    The broader problem was confidence.

    By March 2026, Reuters reported that more than 500 brands had resumed shipping products to Saks Global and that the company had released nearly $1.3 billion in retail receipts — a measure of merchandise value, not revenue earned. The development suggested that supplier relationships and inventory flows were beginning to recover during the bankruptcy process.

    It also revealed how far the crisis had reached.

    The retailer’s financial difficulties had become an inventory problem, and its inventory problem had become a customer-experience problem.

    For a business built around access to desirable goods, that is a fundamental threat.

    THE DEPARTMENT STORE’S CHANGING PLACE IN LUXURY

    Saks was not operating in the same retail environment that had shaped its historic success.

    Luxury brands have spent years investing in their own boutiques, websites, clienteling systems and direct relationships with customers. These channels allow brands to control presentation, service, customer data and the way their products reach the market.

    Department stores still offer something valuable: curation across multiple designers, the convenience of shopping several brands in one place and the possibility of discovering products a customer might not otherwise encounter.

    But the department-store proposition must justify its role.

    A luxury house may increasingly ask whether a wholesale partner provides enough incremental reach, sales and customer value to justify the commercial terms. A shopper may ask whether visiting a department store offers a better experience than purchasing directly from the brand.

    The department store sits between these two questions.

    It needs brands to provide desirable merchandise, and it needs customers to believe that shopping through the retailer is worthwhile. Its commercial value depends on delivering a strong experience to both sides.

    That model becomes more difficult when financial pressure compromises the very things that make the store attractive.

    A retailer cannot consistently promise exceptional curation without access to the right products. It cannot provide outstanding service indefinitely without investing in staff, technology and physical spaces. And it cannot rebuild its reputation if customers repeatedly encounter gaps in availability.

    The challenge is not that department stores have become irrelevant. It is that their relevance can no longer be assumed.

    They must offer a compelling reason to exist in a market where luxury brands have greater control over distribution and customers have more ways to shop.

    Saks’ difficulties exposed what happens when the financial capacity to deliver that proposition begins to weaken.

    THE WIDER LUXURY MARKET ADDED PRESSURE

    The luxury market has also become more challenging.

    On 6 October 2026, Reuters reported that US luxury spending had declined year over year for a third consecutive month, based on Citi credit-card data. Spending was down 6% in September, following declines of 4% in July and August.

    The data suggested that even affluent consumers were approaching some luxury purchases more cautiously amid economic uncertainty.

    A separate Reuters report on 9 October described additional pressure from China’s tax crackdown on wealthy individuals, alongside weaker US spending and wider market concerns. Chinese consumers have historically been important to global luxury demand, so developments affecting their spending can influence the industry’s outlook well beyond China.

    These figures provide relevant context for Saks’ restructuring. They do not prove that a luxury slowdown caused its bankruptcy.

    The company’s difficulties were rooted in a combination of financial obligations, liquidity pressure and supplier-payment problems. A weaker consumer environment made recovery more challenging, but it was not a sufficient explanation for the crisis on its own.

    This distinction matters.

    Luxury businesses do not all respond to market weakness in the same way. Their performance depends on customer mix, pricing, product categories, distribution strategy, operating costs and financial resilience.

    A retailer already struggling to pay suppliers has less flexibility when sales disappoint. It has fewer resources to replenish inventory, invest in its stores or absorb the cost of rebuilding confidence.

    The market slowdown therefore acted as an additional pressure on an already vulnerable business.

    The mistake would be to interpret Saks’ bankruptcy as evidence that luxury demand had simply disappeared. The more useful conclusion is that difficult market conditions can expose weaknesses that a stronger balance sheet might otherwise have helped a retailer withstand.

    WHY SCALE WAS NOT ENOUGH

    The promise of a merger is usually expressed in future benefits.

    A combined organisation may expect to reduce duplicated costs, improve purchasing power, streamline logistics and make better use of technology. But these benefits must be realised through execution.

    Integration takes time. Systems must be connected, supplier agreements managed, store portfolios reviewed and operating decisions coordinated. Management must also determine which parts of the business should be combined and which should remain distinct.

    Meanwhile, financial obligations continue.

    If debt and operating costs rise faster than the expected benefits of consolidation, a larger organisation can become more fragile rather than more resilient.

    The Saks transaction illustrates this risk.

    The group brought together three recognised luxury retail names and a substantial portfolio of stores. Yet the combined business still had to prove that its scale could translate into reliable cash generation.

    The bankruptcy filing showed that the original structure could not sustain its obligations and operating needs.

    It would be wrong to conclude that the acquisition alone explains every weakness in the business. Saks Global inherited an industry facing structural changes, and its individual retail brands had different histories and operating challenges.

    But the transaction intensified the importance of financial execution. Once the combined group struggled to maintain supplier payments and merchandise availability, the intended benefits of scale became harder to realise.

    The central lesson is not that consolidation never works. It is that consolidation cannot substitute for financial resilience.

    A larger business may have more opportunities. It also has more obligations to manage.

    JANUARY 2026: BANKRUPTCY AS A RESET

    On 13 January 2026, Saks Global filed for Chapter 11 bankruptcy protection in the United States.

    Chapter 11 allows an eligible company to reorganise its finances under court supervision while seeking to continue operating. It does not automatically mean that every store will close or that every brand will disappear.

    For Saks Global, the process created a route to restructure debt, secure new funding, close underperforming locations and work towards restoring supplier confidence.

    The restructuring plan involved significant sacrifices.

    Reuters reported in June that the court-approved plan would eliminate the company’s existing equity and transfer control to its senior lenders. The plan included $1 billion in new funding from senior lenders and a further $500 million commitment after the company emerged from bankruptcy.

    These were not cosmetic changes. They represented a substantial shift in ownership and financial structure.

    The group also reduced its store footprint. The plan approved in June called for a portfolio of 49 luxury retail locations: 33 Neiman Marcus stores, 15 Saks Fifth Avenue stores and the two-store Bergdorf Goodman operation in New York.

    The reduction in Saks Fifth Avenue’s footprint was especially significant, from approximately 33 stores before bankruptcy to 15 under the approved plan.

    A smaller network can reduce fixed costs and concentrate resources on locations with stronger commercial potential. But it also reduces geographic reach and changes the role of the retailer in markets where it no longer has a physical presence.

    The strategy is a trade-off: operate fewer stores, invest more selectively and attempt to improve the performance of the remaining business.

    Whether that strategy succeeds depends on execution, not simply on the number of stores closed.

    JUNE 2026: A NEW NAME, A DIFFERENT BALANCE SHEET

    On 26 June 2026, the company announced that it had completed its restructuring and emerged from Chapter 11 under the name Exemplar Luxury Group.

    The group said its debt had been reduced by nearly 75% and that it had sufficient liquidity to support its operations and invest in its future. It continued to include Saks Fifth Avenue, Neiman Marcus and Bergdorf Goodman.

    The debt reduction was substantial. It gave the restructured business a materially different financial starting point.

    But lower debt should not be confused with a completed recovery.

    A stronger balance sheet can reduce financial pressure and create room for investment. It does not automatically restore every supplier relationship, guarantee profitable trading or persuade customers to return.

    Nor does the completion of bankruptcy prove that the acquisition strategy has been vindicated. The restructuring involved a major reduction in debt, a transfer of control to senior lenders and a smaller store network. Those are significant changes to the original proposition.

    The new group now faces a different test.

    Can it operate the three retail brands with greater financial discipline? Can it maintain reliable merchandise flows? Can it deliver a distinctive experience while controlling costs? And can it generate sustainable profits without recreating the pressures that led to bankruptcy?

    Those questions will determine whether the restructuring becomes a genuine turnaround or simply a temporary reprieve.

    The corporate name has changed. The operating challenge has not disappeared.

    WHAT SAKS REVEALS ABOUT THE FUTURE OF LUXURY RETAIL

    The Saks story offers three important lessons for the wider luxury industry.

    First, prestige cannot replace liquidity.

    A recognised name, a celebrated flagship and access to desirable designers are valuable assets. But a retailer must still pay for inventory, fund its stores, meet its financial obligations and maintain supplier confidence. Brand equity cannot permanently compensate for a business that lacks the cash to operate.

    Second, supplier relationships are strategic assets.

    For a multi-brand retailer, merchandise availability is central to its appeal. A breakdown in supplier confidence can affect the assortment, weaken customer experience and undermine the retailer’s credibility. Restoring those relationships may be as important as reducing debt.

    Third, scale is valuable only when it produces better economics.

    A merger can create opportunities for efficiency and customer growth. It can also increase complexity and financial obligations. If the benefits arrive too slowly, the larger organisation may become less flexible precisely when it needs to be most resilient.

    There is a fourth lesson, too: the future of the department store depends on differentiation.

    A retailer must give customers a reason to choose its environment over a brand’s own boutique or website. That reason might be exceptional curation, personalised service, access to multiple designers, exclusive merchandise or a physical experience that feels genuinely distinctive.

    It must also give brands a reason to maintain the relationship.

    For luxury department stores, success depends on making both sides believe that the intermediary adds value. That is a demanding proposition, but it remains possible.

    The industry does not need fewer places to discover luxury simply because direct-to-consumer retail has grown. It needs multi-brand retailers that are financially disciplined, commercially reliable and relevant to the way customers shop today.

    Saks’ restructuring is a test of whether that model can be rebuilt on a more sustainable foundation.

    THE REAL PRICE OF THE GAMBLE

    The $2.65 billion Neiman Marcus acquisition was designed to create a more powerful force in American luxury retail. It brought together three established names and promised greater scale, technological capability and access to affluent customers.

    Instead, the combined group entered bankruptcy protection barely thirteen months after the deal closed, with approximately $3.4 billion in funded debt obligations and serious problems involving supplier payments and inventory availability.

    The acquisition was a central part of the story, but it was not the only factor. The broader retail environment was changing, luxury brands were strengthening their direct channels, and the business faced operational pressures that the merger’s promised benefits did not resolve quickly enough.

    By June 2026, the company had emerged with a new corporate identity, substantially reduced debt and a smaller store network. The retail names at the heart of the original ambition remained.

    What remains unproven is whether the new structure can deliver durable, profitable growth.

    That will depend on the fundamentals: cash generation, merchandise availability, supplier confidence, customer experience and disciplined investment. It will depend on whether the group can preserve the distinctiveness of its brands while operating them more efficiently.

    Saks’ story is not proof that luxury is finished, or that department stores no longer have a place in the market. It is a warning that prestige and scale cannot protect a retailer indefinitely when its financial structure undermines its ability to deliver what customers and suppliers expect.

    In luxury, a name can open the door.

    It cannot pay the bills.

    And no matter how desirable the merchandise, a retail empire cannot survive for long if it cannot reliably get that merchandise onto the shelves.

    INSYDE Magazine — Where luxury, culture and influence meet.
    NO.1 LUXURY MAGAZINE IN BENGALORE

  • DECODING THE ANTHONY VACCARELLO EXIT

    DECODING THE ANTHONY VACCARELLO EXIT

    Inside the end of his decade at Saint Laurent, the financial pressures reshaping luxury fashion, and the unanswered questions surrounding one of the industry’s most consequential creative departures.

    By INSYDE Magazine | Luxury & Fashion

    There is something almost cinematic about leaving Saint Laurent in gold.

    For Anthony Vaccarello, the final chapter at the French fashion house arrived in a blaze of metallic glamour. Gold dresses, sculptural trench coats and shimmering stilettos transformed the runway into a vision of opulence, staged beneath the Eiffel Tower and recalling the grandeur of Saint Laurent’s own history.

    It was a fitting image for a designer whose decade at the house had been defined by controlled sensuality, sharp silhouettes and a distinctly nocturnal vision of luxury.

    Then came the announcement.

    On 9 October 2026, Kering officially confirmed that Vaccarello was leaving Saint Laurent after ten years as creative director. The group praised his contribution to strengthening the house’s identity and cultural influence, while confirming that new creative leadership would be announced soon. The statement did not disclose a specific reason for his departure.

    Read Kering’s official announcement.

    The timing is significant. Vaccarello is not leaving an obscure label struggling to establish an identity. He is departing one of fashion’s most recognisable houses after helping take its annual sales beyond €3 billion in 2023.

    Yet the years that followed brought a commercial slowdown, against the backdrop of a wider luxury-market correction and a restructuring at Saint Laurent’s parent company.

    So what does his exit actually tell us?

    Is this the natural conclusion of a decade-long creative partnership? A response to the changing economics of luxury? Or a sign that even a successful creative vision must eventually adapt to a new set of commercial expectations?

    The public record does not establish one definitive explanation. But Vaccarello’s legacy, Saint Laurent’s financial trajectory and Kering’s broader strategic reset offer a revealing picture of the pressures facing luxury fashion today.

    A DECADE OF DESIRE

    When Vaccarello took over Saint Laurent in 2016, succeeding Hedi Slimane, he inherited a house whose recent identity had been shaped by a powerful, highly distinctive creative vision. His challenge was to establish his own language without diluting the attitude that made Saint Laurent instantly recognisable.

    He approached the task through consistency rather than reinvention for its own sake.

    Black became a near-constant. Shoulders were sharpened. Legs were elongated. Leather, sheer fabrics, short hemlines and precise tailoring created a wardrobe that moved between eroticism and authority. The result was sensual without being soft, glamorous without being traditionally romantic.

    His Saint Laurent woman did not need to announce her presence. The clothes did it for her.

    But reducing Vaccarello’s tenure to provocative dresses would overlook the scale of his achievement. He built a coherent visual world across runway collections, campaigns, celebrity dressing and monumental Parisian shows. The Eiffel Tower became a recurring backdrop, transforming the city itself into part of the brand’s imagery.

    Saint Laurent was selling more than clothing. It was selling an atmosphere: Paris after dark, unapologetic sexuality, rock-and-roll attitude and a particular form of modern power.

    He also helped extend the house’s cultural reach beyond fashion through Saint Laurent Productions, launched in 2023. Its involvement in cinema, including Emilia Pérez, brought the brand into a broader cultural conversation and demonstrated how a fashion house could use film as an extension of its identity.

    Explore Vogue’s coverage of Vaccarello’s departure and creative legacy.

    Commercially, the results were substantial. According to Reuters, Saint Laurent generated well over €3 billion in annual sales in 2023. Vaccarello had helped establish a strong identity at a scale that few creative directors achieve.

    That is what makes his departure consequential. He was not simply designing the next collection. He had become central to how the house presented itself to the world.

    THE NUMBERS BEHIND THE EXIT

    Luxury is built on desire. But desire must eventually translate into sales.

    Saint Laurent’s financial trajectory provides essential context for understanding why this transition matters. The brand reached more than €3 billion in annual sales in 2023 before losing momentum as the luxury sector faced weaker demand and brands reassessed their growth strategies.

    Reuters reported that Saint Laurent’s gross revenue declined by 9% in 2024 and a further 6% in 2025. Performance had largely stabilised during 2026, according to the same report, although full-year 2026 results were not yet available as of 11 October.

    Saint Laurent: the recent financial picture

    PeriodReported performance
    2023Annual sales exceeded €3 billion
    2024Gross revenue declined 9%
    2025Gross revenue declined a further 6%
    2026Performance described as largely stabilised; full-year results pending

    Source: Reuters, 9 October 2026. Figures refer to reported annual sales and gross-revenue movements; the 2026 assessment is qualitative, not a full-year result.

    The numbers matter, but they require careful interpretation.

    The decline does not prove that Vaccarello’s designs caused the slowdown, nor does it establish that falling sales triggered his departure. Luxury brands have faced a more challenging environment as consumers have become selective, price increases have tested perceptions of value, and demand has weakened across parts of the market.

    Saint Laurent’s parent company, Kering, has also been under pressure. The group reported 2025 revenue of approximately €14.7 billion, reflecting the wider challenges facing its portfolio of luxury houses.

    Read Kering’s official announcement and corporate information and Reuters’ reporting on the departure and financial context.

    This is the broader context in which Vaccarello’s exit should be understood. Kering is working to restore growth and improve performance across a portfolio that includes Saint Laurent, Gucci, Bottega Veneta and Balenciaga.

    The strategic question is no longer simply whether a collection generates attention. It is whether a house can translate creative distinction into sustainable demand, profitable growth and stronger customer relationships.

    That is a much harder equation to solve.

    WHEN THE RUNWAY MEETS THE BALANCE SHEET

    A spectacular runway show can dominate fashion coverage. A celebrity appearance can put a collection in front of millions. A campaign can make a handbag instantly desirable.

    But none of those moments, on its own, guarantees sustained growth.

    Luxury houses also depend on products that customers return to: daywear that works beyond special occasions, leather goods that justify their prices, menswear with a clear identity, and collections that encourage repeat purchases without making the brand feel overexposed.

    Reuters, citing Barclays analysts, identified women’s daywear, menswear and high-end leather goods, alongside less-penetrated markets in China and Asia, as potential areas of focus for Saint Laurent’s next creative chapter.

    These are potential growth opportunities identified by analysts, not a confirmed brief issued by Kering.

    Read Reuters’ full report on Saint Laurent’s leadership change.

    This points to a strategic challenge rather than a simple aesthetic verdict.

    Vaccarello’s vision was disciplined and commercially powerful. Yet the next phase of growth may require Saint Laurent to broaden the ways customers engage with the brand while protecting the desirability that made it successful.

    Expand too aggressively and the house risks diluting the sense of scarcity and attitude that gives its products their appeal. Rely too heavily on a narrow visual signature and it may struggle to create enough new reasons for customers to return.

    The strongest luxury houses make commercial expansion feel like a natural extension of their creative identity. For Saint Laurent, that is the challenge ahead.

    WAS IT A CONTROVERSIAL EXIT?

    The word controversy travels quickly in fashion. A departure becomes a rumour. A rumour becomes a supposed falling-out. A final collection is reinterpreted as a coded message.

    But the evidence available publicly is more limited than the speculation might suggest.

    Kering confirmed Vaccarello’s departure and praised his contribution to the house. It did not publicly identify a dispute, misconduct allegation or specific personal conflict as the reason. Reuters reported that a successor would be announced soon, but did not establish a definitive explanation for the decision.

    There is, therefore, no verified basis for presenting this as a personal scandal or claiming that Vaccarello was fired over a particular disagreement.

    That does not make the departure unimportant. A creative-director transition after ten years can be significant without being scandalous. It can reflect strategic priorities, changing commercial expectations, personal decisions or the natural conclusion of a long creative partnership. Without evidence, assigning one of these explanations to Vaccarello would be speculation.

    The more substantive story is the environment in which the exit occurred.

    Kering has been reshaping creative leadership across its portfolio as it attempts to reverse a prolonged downturn. Saint Laurent’s transition belongs to a larger conversation about how luxury groups balance creative autonomy with commercial accountability.

    The question is not whether a designer can create a memorable collection. It is how long a creative leader remains the right person for a house as its business enters a different phase.

    In an industry where creative directors increasingly become the public face of a brand, the distinction between the designer’s identity and the house’s identity can become complicated. When the designer leaves, the business must prove that the desirability they helped create belongs to the brand itself—not exclusively to the person behind it.

    THE GOLDEN FINALE

    Vaccarello’s final runway provided an arresting image for the end of his tenure.

    Gold dresses, gold outerwear and gold stilettos appeared beneath monumental chandeliers in a presentation that referenced the Salon Impérial at Paris’s Hôtel Inter-Continental, associated with Yves Saint Laurent’s historic couture presentations.

    It was a visual return to the house’s mythology: grandeur, theatricality and the idea of fashion as a carefully controlled spectacle.

    The collection has inevitably invited interpretation. Was the gold a farewell? A statement of triumph? A deliberate message about the designer’s relationship with the house?

    There is no confirmed evidence that it was intended as a coded message about his departure. Treating the collection as proof of a hidden conflict would confuse fashion criticism with reporting.

    Its significance is more compelling when considered on its own terms. Vaccarello spent a decade making Saint Laurent’s codes feel contemporary without making them unrecognisable. His final collection concentrated those codes—sensuality, Parisian grandeur, sharp tailoring and theatrical glamour—into a single visual statement.

    Gold was more than decoration. It was a fitting language for a house that has long sold aspiration through clothing and imagery.

    But a spectacular finale cannot answer the question that follows every creative-director departure: what happens when the person who defined the look is no longer there?

    WHO COMES NEXT?

    At the time of writing, Kering has confirmed that new creative leadership will be announced, but no successor has been officially named.

    Industry speculation has included Chemena Kamali, currently creative director at Chloé and previously associated with Saint Laurent’s design team. That possibility remains unconfirmed and should not be mistaken for an appointment.

    Reuters’ report on the departure and successor speculation.

    Whoever takes the role will inherit a house with considerable advantages: a recognisable identity, global visibility, a strong cultural presence and a decade of consistent creative direction. They will also inherit a commercial challenge.

    The next chapter must preserve what makes Saint Laurent distinctive while giving the business fresh momentum. Developing daywear and menswear, strengthening leather goods and pursuing opportunities in Asian markets are among the areas analysts have identified as potential avenues for growth.

    The creative challenge will be delicate. Too much continuity could make the next era feel derivative. Too sharp a break could alienate customers who associate Saint Laurent with Vaccarello’s particular combination of sensuality and control.

    The successor will not simply be asked to design a successful collection. They will be asked to define what Saint Laurent looks and feels like next—and to make that vision commercially compelling.

    THE NEXT CHAPTER OF LUXURY

    Vaccarello’s departure arrives at a moment when luxury fashion is reconsidering the relationship between creative identity and financial performance.

    For years, the industry benefited from powerful brand equity, global expansion and customers willing to pay increasingly high prices for desirable products. The current environment demands more. Brands must give customers compelling reasons to buy, justify their prices and build identities that can withstand changes in consumer behaviour.

    Saint Laurent’s recent revenue decline is part of that context, but it should not be mistaken for a verdict on one designer. Vaccarello helped take the house beyond €3 billion in annual sales and established a visual language that reached well beyond the runway. The subsequent slowdown occurred amid broader industry pressure, while the precise reason for his departure remains undisclosed.

    The next phase will reveal whether Saint Laurent can turn that legacy into renewed growth without diluting the qualities that made it desirable.

    That is the real story behind the exit: not a proven scandal or a confirmed boardroom battle, but a consequential change at the intersection of fashion, business and cultural influence.

    Anthony Vaccarello leaves behind a decade of sharp silhouettes, exposed skin, precise tailoring and cinematic spectacle. Saint Laurent now faces a different kind of design challenge—one that cannot be solved on a runway alone.

    It must decide what comes after desire.

    And in luxury, the answer is rarely as simple as changing the name on the invitation.

    INSYDE Magazine — Where luxury, culture and influence meet.


    SOURCES & FURTHER READING

    1. Kering — Official announcement of Anthony Vaccarello’s departure, 9 October 2026
    2. Reuters — Saint Laurent ends Vaccarello’s decade-long tenure amid wider Kering revamp, 9 October 2026
    3. Reuters via Investing.com — Financial performance, industry context and successor speculation, 9 October 2026
    4. Vogue — Anthony Vaccarello Bows Out at Saint Laurent, 9 October 2026

    Editorial note: This article reflects publicly available information as of 11 October 2026. Saint Laurent had not publicly disclosed a specific reason for Vaccarello’s departure, and no successor had been officially announced at the time of writing.

  • THE INDIAN ROYAL WHO REWROTE BOUCHERON’S STORY

    THE INDIAN ROYAL WHO REWROTE BOUCHERON’S STORY

    How Maharaja Bhupinder Singh of Patiala brought a treasure of gemstones to Paris—and inspired one of French high jewellery’s most extraordinary chapters.

    By INSYDE

    There are jewels that announce wealth.

    And then there are jewels that become history.

    On 2 August 1928, an Indian Maharaja arrived at one of Paris’s most prestigious jewellery houses carrying a treasure of diamonds, emeralds, rubies and pearls. He had not come to browse a boutique or select a finished necklace. He had brought his own gemstones, and he wanted them transformed into something extraordinary.

    His name was Maharaja Bhupinder Singh of Patiala.

    The jeweller was Boucheron.

    What followed was an exceptional commission: 7,571 diamonds, 1,432 emeralds and 149 original jewellery designs, according to Boucheron’s historical account and contemporary coverage.

    It was a meeting between Indian royal patronage and French high jewellery, between a ruler with an extraordinary collection of gemstones and a maison with the craftsmanship to give them new form.

    Nearly a century later, those original designs would inspire a contemporary collection, bringing the story back into the spotlight.

    The Maharaja’s jewels had become more than an expression of royal extravagance. They had entered the creative history of one of France’s most enduring jewellery houses.

    And the most remarkable part?

    The story was still being written long after the original commission.

    BEFORE THE MAHARAJA, THERE WAS BOUCHERON

    Founded in Paris in 1858 by Frédéric Boucheron, the maison established its reputation through fine craftsmanship, precious gemstones and an approach to jewellery that challenged convention.

    In 1893, Frédéric Boucheron became the first of the great contemporary jewellers to open a boutique on Place Vendôme, the Parisian address that would become synonymous with high jewellery.

    The location was a statement in itself. Place Vendôme represented a world where exceptional materials, technical mastery and individual commissions came together to serve an international clientele.

    By the early twentieth century, Indian princely rulers were among the wealthy patrons commissioning jewellery from European maisons. Their collections contained gemstones inherited across generations, and their commissions could demand a level of customisation far beyond conventional retail.

    But the relationship was not simply about Indian wealth purchasing European craftsmanship.

    Indian royal jewellery had its own visual language and cultural significance. Precious stones, elaborate necklaces, ceremonial ornaments and turban jewels could communicate rank, authority and identity. Their forms were shaped by regional traditions, courtly customs and the preferences of individual rulers.

    For European jewellers, commissions of this kind presented an opportunity to work with extraordinary materials while interpreting them through their own design traditions.

    Boucheron’s encounter with Bhupinder Singh would become one of the most remarkable examples of that relationship.

    ENTER THE MAHARAJA OF PATIALA

    Bhupinder Singh was born in 1891 and became Maharaja of Patiala in 1900. The ruler of the princely state in present-day Punjab was known for his extravagant lifestyle, interest in sport and passion for luxury.

    His world encompassed grand travel, automobiles, fine clothing and exceptional jewellery. He understood the public language of royal presentation: the way a carefully chosen object could communicate authority, taste and status.

    Yet the significance of his relationship with Boucheron lies in something more specific than his reputation for extravagance.

    He brought the maison a commission built around his own gemstones.

    On 2 August 1928, the Maharaja arrived at Boucheron’s boutique at 26 Place Vendôme in Paris. Accounts of the visit describe an extensive royal entourage and guards carrying secure containers filled with precious stones.

    The jewellery house was led by the legacy of its founder, Frédéric Boucheron. The commission was handled by his son, Louis Boucheron, who received the Maharaja’s treasure and undertook the task of translating it into jewellery designs.

    The scene has all the ingredients of a cinematic encounter: a royal patron arriving in the heart of Paris with a private treasure, a historic jewellery house opening its doors, and gemstones whose potential would be realised through an extraordinary bespoke commission.

    Inside were diamonds, emeralds, rubies, pearls and other precious stones.

    The question was what Boucheron could make of them.

    7,571 DIAMONDS. 1,432 EMERALDS. 149 DESIGNS.

    The numbers remain extraordinary.

    According to Boucheron’s historical account, the 1928 commission involved 7,571 diamonds and 1,432 emeralds, alongside other gemstones, which were selected for an exceptional collection of jewellery.

    Louis Boucheron created 149 original designs for the commission.

    The proposed creations included elaborate diamond-and-emerald collars, multi-strand pearl necklaces, gemstone-set belts and other pieces intended for the Maharaja and his family.

    These were not ordinary retail purchases. The gemstones came from the Maharaja’s own collection, while Boucheron’s role was to interpret those materials through design and jewellery-making expertise.

    That distinction matters.

    In contemporary luxury, the value of a jewel is often communicated through its brand, rarity, materials or retail price. In this commission, the story began with a royal collection of gemstones and the decision to entrust them to a particular maison.

    Boucheron had to do more than produce expensive objects. It had to create jewellery capable of carrying the Maharaja’s identity and the visual grandeur expected of a royal commission.

    The designs brought together elements of Indian jewellery traditions and the design sensibilities of the period, including Art Deco influences. The resulting aesthetic was not simply a reproduction of European fashion or Indian court jewellery. It emerged from the meeting of the patron’s requirements, the gemstones themselves and Boucheron’s creative interpretation.

    The scale of the commission was exceptional. Boucheron describes it as the largest order ever placed at Place Vendôme.

    One royal commission had given the maison a remarkable chapter in its history.

    WHEN WEALTH BECOMES A CREATIVE BRIEF

    There is a difference between commissioning jewellery and giving a jeweller the freedom to create something extraordinary.

    Bhupinder Singh’s commission began with an exceptional resource: his own collection of precious stones. Rather than selecting finished pieces from a display, he brought the materials and entrusted Boucheron with the task of transforming them.

    The gemstones were not simply materials to be acquired. They were part of the creative brief.

    Their colours, sizes and individual characteristics helped determine what could be made. The jeweller’s challenge was to bring them into a coherent collection while respecting their qualities and the intended forms of the jewellery.

    The result was a collaboration between a royal patron and a jewellery house, each contributing something essential.

    The Maharaja brought the treasure and the commission.

    Boucheron brought the design expertise, craftsmanship and creative interpretation.

    This is an enduring principle of high jewellery: exceptional creations often emerge when rare materials meet a clear vision and the technical ability to realise it.

    In this case, the outcome was not simply one celebrated necklace, but a body of 149 original designs.

    It was a reminder that the most interesting luxury commissions are not always defined by the amount spent. They are defined by what a patron and a creative house can make possible together.

    THE ARCHIVE THAT KEPT THE STORY ALIVE

    Time is not always kind to extraordinary objects.

    Jewellery can be inherited, dismantled, reset, sold or dispersed across private collections. A piece that once defined a royal occasion may eventually become difficult to trace.

    The Boucheron commission illustrates an important distinction: the history of a jewel is not necessarily the same as the history of its design.

    Boucheron retained the original designs in its archives. These drawings recorded the creative response to the Maharaja’s commission and preserved a connection to the work undertaken in 1928.

    The subsequent whereabouts of the entire original collection are not clearly established in the public record. It would therefore be inaccurate to claim that all 149 finished pieces remain together, or that the entire collection was definitively lost.

    What survives is significant in its own right: the original designs and the documented history of the commission.

    Those records eventually became a bridge between the royal patron of 1928 and a new generation of designers.

    Nearly a century later, the archive would lead to another collection.

    NEW MAHARAJAHS: A ROYAL VISION REIMAGINED

    In January 2022, Boucheron unveiled Histoire de Style: New Maharajahs, a high-jewellery collection inspired by the historic Patiala commission.

    Conceived by the maison’s creative director, Claire Choisne, the collection revisited the original designs and explored how their spirit could be translated into contemporary jewellery.

    The objective was not to reproduce the past piece by piece.

    Instead, Choisne used the archive as a starting point for a new creative interpretation. The collection retained references to Indian royal adornment while exploring contemporary proportions, materials and ways of wearing jewellery.

    The resulting collection comprised 14 pieces across five sets.

    Diamonds, emeralds, pearls, rock crystal, mother-of-pearl, platinum and white gold contributed to its visual language. The designs also drew on references associated with Indian adornment, including the lotus flower and the traditional sarpech, a jewelled ornament worn on a turban.

    One of the collection’s defining creations was the New Maharajah necklace, featuring nine cushion-cut Colombian emeralds weighing nearly 40 carats in total. Its central motif could be detached and worn as a brooch, allowing the piece to be transformed rather than confined to a single form.

    That transformability reflected a broader approach within the collection: jewellery was not treated solely as ceremonial display, but as something that could adapt to the wearer.

    Choisne also made a striking aesthetic decision. Rather than recreating the original commission’s full visual intensity, the contemporary collection explored a palette of white and transparency, using materials such as rock crystal and diamonds to create a different sense of lightness.

    The result was a conversation between historical inspiration and modern design.

    The Maharaja’s commission supplied the creative foundation. Boucheron’s contemporary studio supplied a new interpretation.

    The past was not simply reproduced. It was reimagined.

    WHY BOUCHERON RETURNED TO THE MAHARAJA

    Luxury houses frequently speak of heritage. But heritage becomes meaningful when it can do more than decorate a campaign.

    It must give the present something to work with.

    The Patiala commission offered Boucheron several layers of meaning: an extraordinary historical client, a remarkable collection of gemstones, a documented body of designs and a connection between Indian royal culture and French high jewellery.

    The New Maharajahs collection brought these elements together again, demonstrating how an archive can inform contemporary creation.

    A historic design is not automatically relevant to a modern audience. Its relevance emerges when a creative house finds something in it that can be reconsidered, adapted or challenged.

    In Boucheron’s case, the original drawings offered more than a record of what had once been commissioned. They provided a foundation for new work.

    That is the difference between heritage as nostalgia and heritage as a creative resource.

    The 2022 collection did not need the original jewels to be presented as a complete surviving set. The designs themselves offered a way to reconnect with the commission and reinterpret its ideas for a new generation.

    The Maharaja’s legacy continued through the creative possibilities his commission had left behind.

    THE INDIAN CONNECTION TO FRENCH LUXURY

    There is a tendency to tell the history of European luxury houses as a story of European creativity expanding outwards into the world.

    The relationship between Boucheron and Bhupinder Singh offers another perspective.

    The Maharaja was not simply a consumer of French luxury. He was a patron whose gemstones and commission helped shape a significant body of work within the maison’s history.

    The original commission emerged from a specific encounter between Indian royal wealth, traditions of Indian adornment and the capabilities of a Parisian jewellery house.

    Its later revival made that encounter relevant to a contemporary audience.

    This does not mean that one commission alone transformed Boucheron into the maison it is today. Its history stretches back to 1858 and includes many clients, designers and creative chapters.

    But the Patiala commission demonstrates that the history of a luxury house is often shaped by the people who commission its work as much as by the people who create it.

    The relationship was not simply transactional. It became part of the maison’s cultural and creative heritage.

    For Indian readers, that connection is especially compelling. It places an Indian royal at the centre of a major chapter in the history of a French jewellery house—not as a passing reference, but as the patron behind an exceptional commission whose designs later inspired a contemporary collection.

    It is a reminder that the history of global luxury has never belonged to one country alone.

    THE OTHER PATIALA JEWELLERY STORY

    The Maharaja’s name is also associated with another celebrated creation: the Patiala Necklace by Cartier.

    The two stories are connected by the same royal patron, but they are separate commissions.

    Boucheron’s 1928 order involved 149 original jewellery designs using gemstones from Bhupinder Singh’s collection. Cartier’s Patiala Necklace was a different creation, renowned for its extraordinary diamonds and its central 234.65-carat yellow De Beers diamond.

    The Cartier necklace later became the subject of a separate story involving the disappearance of much of the original piece and the eventual recovery and restoration of some components by Cartier using replacement stones.

    That history should not be confused with the uncertain whereabouts of the complete Boucheron commission.

    Both stories reveal the scale of Indian royal patronage during the period and the relationships between princely wealth and the leading jewellery houses of Europe.

    But Boucheron’s story deserves to be understood on its own terms: a vast bespoke commission, 149 archival designs and a modern high-jewellery collection inspired by the original work.

    WHAT THE MAHARAJA’S LEGACY REVEALS ABOUT LUXURY

    Today, luxury is frequently discussed in terms of scarcity, status, price and brand recognition. These elements matter, but they do not fully explain why certain objects endure in cultural memory.

    The Boucheron–Patiala story offers another perspective.

    The original commission possessed scale and material extravagance. Yet its continuing significance comes from more than the number of gemstones involved.

    It has a protagonist, a documented creative relationship, an archive and a contemporary reinterpretation.

    It connects a specific historical moment to a modern collection, allowing the past to inform the present without requiring the original pieces to remain together.

    That is the power of meaningful luxury heritage.

    A jewel can be valuable because of its materials. It can be desirable because of its craftsmanship. But a documented story can give it another dimension: a place within a wider history of people, taste and creative exchange.

    For Boucheron, the Maharaja’s commission remains a striking example of that principle.

    The stones were extraordinary. The order was exceptional. But the legacy endured because the creative work was preserved—and because a later generation found something worth creating from it.

    THE VERDICT

    The Indian royal who rewrote Boucheron’s story did not build the maison, and he did not define its entire future.

    What he did was leave behind an extraordinary chapter.

    In 1928, Bhupinder Singh of Patiala brought his collection of precious stones to Paris and commissioned Boucheron to create 149 jewellery designs. The maison describes the order as the largest ever placed at Place Vendôme.

    The original designs remained in the archives. In 2022, Claire Choisne returned to them with Histoire de Style: New Maharajahs, translating a historic royal commission into a contemporary high-jewellery collection.

    The distance between those two moments is what makes the story remarkable.

    A treasure arrived in Paris. A jewellery house gave it form. An archive preserved the creative record. And a new generation found inspiration in the designs.

    Nearly a century later, the Maharaja’s story still has something to say about luxury—not simply as the possession of rare things, but as the meeting of material, imagination, patronage and memory.

    Because the most enduring luxury stories are rarely about the price of an object alone.

    They are about the people who make it possible, the ideas that shape it and the legacy it leaves behind.

    One Indian Maharaja. One extraordinary commission. And a French jewellery house whose archives ensured the story would not end in 1928.

    INSYDE — Culture, people and the stories shaping luxury.

  • THE LUXURY BRANDS THE RICH DON’T TELL YOU ABOUT

    THE LUXURY BRANDS THE RICH DON’T TELL YOU ABOUT

    Beyond Gucci, Hermès and Chanel: the discreet names shaping the world of insider luxury.

    By INSYDE


    Everyone knows the names.

    Gucci. Louis Vuitton. Chanel. Hermès. Dior. Prada.

    Their logos are everywhere — on red carpets, in airports, on social media, in music videos and across the wardrobes of celebrities.

    But there is another side to luxury.

    A quieter one.

    One where the logo matters less, the history matters more and recognising the name can sometimes be less important than understanding why the name matters.

    This is the world of Kiton, Delvaux, Moynat, Charvet and Stefano Ricci.

    They aren’t secret brands in the literal sense. Serious fashion collectors, luxury insiders, menswear enthusiasts and wealthy clients know them well. But compared with the global visibility of the industry’s biggest houses, these names occupy a more specialised corner of luxury.

    And that difference is precisely what makes them fascinating.

    Because once you’ve seen every logo, visited every flagship and bought every obvious symbol of status, a different question begins to emerge:

    What comes next?


    WHEN LUXURY STOPS SHOUTING

    For years, luxury was built around recognition.

    The monogram was the message.

    A handbag could tell a story before its owner said a word. A belt buckle could announce a price bracket. A watch could communicate status across a room.

    But the luxury conversation has become more complicated.

    Today’s most sophisticated luxury consumer doesn’t necessarily want less luxury.

    They may simply want more meaning behind it.

    Craftsmanship.

    Provenance.

    Fabric.

    Construction.

    Heritage.

    Personalisation.

    Scarcity.

    And perhaps most importantly — knowledge.

    There is a difference between recognising luxury and understanding luxury.

    Almost everyone recognises a Louis Vuitton monogram.

    Far fewer people can explain why a hand-built Neapolitan jacket from Kiton commands its price.

    Everyone knows Hermès.

    Far fewer have encountered Delvaux’s nearly two-century-old leather-goods history.

    And while many people have heard of bespoke tailoring, considerably fewer know why a house like Charvet has maintained such an unusual position at Paris’s Place Vendôme for almost two centuries.

    This is where the deeper luxury market becomes interesting.


    01

    KITON

    When the suit becomes a craft.

    Naples has always had a particular relationship with tailoring.

    It is relaxed rather than rigid. Soft rather than architectural. Personal rather than formulaic.

    Kiton was founded in 1968 by Ciro Paone in Arzano, near Naples, with a mission centred on handcrafted clothing and Neapolitan sartorial tradition. The house still describes its philosophy through the fundamental tools of tailoring: needle, thread and scissors.

    That philosophy remains visible in Kiton’s current 2026–27 offering.

    The house’s Fall/Winter 2026–27 collection includes highly priced cashmere tailoring, with a medium-grey checked pure-cashmere jacket listed at €10,930 on its current website. Kiton also continues to operate a School of Haute Couture aimed at passing tailoring knowledge to future generations.

    Its fabric programme is equally central to the proposition, with the house highlighting fibres including vicuña, cashmere, silk and fine micron wool, alongside its emphasis on limited production and artisanal processing.

    But the real attraction isn’t simply the price.

    It is the construction.

    A Kiton jacket isn’t intended to scream that it cost thousands.

    Its appeal is supposed to be discovered through the way it sits, moves and feels.

    That is an entirely different approach to status.

    The garment doesn’t introduce itself.

    You have to know what you’re looking at.

    And perhaps that is the point.

    Kiton has continued to expand globally — including a new Hangzhou boutique announced in September 2026 — while maintaining the craftsmanship narrative that made its name.

    In a world obsessed with speed, Kiton is selling something increasingly rare:

    time.


    02

    DELVAUX

    The handbag you don’t need everyone to recognise.

    If you’re talking about luxury handbags, the usual conversation begins with Hermès, Chanel and Louis Vuitton.

    But go deeper and you’ll eventually encounter Delvaux.

    Founded in Brussels in 1829, Delvaux describes itself as the world’s oldest fine leather-goods house. The maison’s archives contain more than 3,000 designs catalogued since 1908, and the house has served as an official purveyor to the Belgian Royal Court since 1883.

    That’s not a recent luxury story.

    That’s nearly two centuries of one.

    Today, Delvaux continues to build around its distinctive leather-goods universe, with collections including the Brillant, Tempête, Pin, Léonce, Cool and Lingot families. The brand also operates more than 50 boutiques globally.

    The important distinction is visibility.

    A Delvaux bag doesn’t necessarily announce its price from across a room.

    Its identity is more subtle.

    The person carrying it may know exactly what it is.

    The person standing beside them may not.

    And that creates an intriguing kind of luxury.

    Recognition becomes optional.

    The object can exist as something personal rather than performative.

    Delvaux’s continued investment in craftsmanship and its historical archives gives it another advantage: it isn’t trying to manufacture heritage after the fact.

    It has almost two centuries of it.


    03

    MOYNAT

    Before the handbag, there was the trunk.

    There was a time when luxury was not primarily about handbags.

    It was about travel.

    Trunks were status objects. They carried wardrobes, possessions and entire lifestyles across oceans and continents.

    Moynat entered that world in 1849, founded by Pauline Moynat as a specialist trunk-making house. In 1873, Moynat introduced its English Trunk, incorporating waterproofing technology using gutta-percha-coated canvas.

    That history still informs the house today.

    Moynat continues to make leather goods, travel pieces and contemporary trunks while maintaining techniques such as leather marquetry, hand-painted personalisation and specialised trunk construction. The house says a Gabrielle handbag can require around 20 hours of work in the atelier.

    Its leather marquetry is particularly remarkable.

    Individual pieces of leather are cut and assembled by hand so precisely that the finished composition can appear to be one continuous piece.

    And Moynat isn’t simply living in its archive.

    In 2026, the maison continued its collaboration with artist Kasing Lung, launching a second capsule collection in selected boutiques from February 6. The project brought Lung’s characters onto Moynat’s signature M Canvas.

    The house currently has a presence in 12 countries with 28 boutiques, according to Moynat, while continuing to offer personalised and special-order services.

    That combination is what makes Moynat interesting in 2026:

    heritage without becoming a museum.

    The past is being used as material for the future.


    04

    CHARVET

    The shirtmaker that luxury’s biggest names eventually came looking for.

    There is something almost cinematic about Charvet.

    A historic Parisian shirtmaker.

    A Place Vendôme address.

    Bespoke shirts.

    Thousands of fabrics.

    And a reputation built largely without shouting about itself.

    Founded in 1838, Charvet has operated from 28 Place Vendôme and has long been associated with bespoke craftsmanship and highly personalised service. A 2026 Vanity Fair profile described it as a rare bastion of discreet luxury, noting its resistance to mass expansion and conventional luxury marketing.

    But 2026 brought a major twist to the Charvet story.

    Chanel acquired the house.

    The acquisition ended 188 years of independent ownership and gave Chanel control of Charvet’s Place Vendôme headquarters and store. The deal followed collaboration between Charvet and Chanel creative director Matthieu Blazy and was presented as part of Chanel’s effort to deepen its connection with menswear and specialist craftsmanship.

    Yet the fascinating part is what isn’t supposed to change.

    Charvet’s identity is built around discretion, craftsmanship and personalised service — the exact qualities that made it interesting in the first place.

    The acquisition therefore raises a much larger question:

    What happens when the world’s biggest luxury houses start acquiring the small houses that already understand exclusivity?

    Because the future of luxury may not simply belong to the biggest brands.

    It may belong to the brands that know how to make luxury feel personal again.


    05

    STEFANO RICCI

    Where luxury becomes almost impossibly specific.

    Florence has always understood luxury.

    Art.

    Architecture.

    Leather.

    Tailoring.

    Stefano Ricci emerged from that tradition in 1972, building an Italian menswear house focused on tailoring, exceptional materials and an unmistakably Florentine identity.

    Today, the brand’s current collections demonstrate just how far into the high end that proposition goes.

    Its current menswear offering includes a cashmere two-button deconstructed suit at $10,650, an Alpha Yarn cashmere suit at $13,350, and an Alpha Yarn cashmere-and-mink blouson at $44,750 on its US website.

    Its Fall/Winter 2026 collection also includes pieces such as vicuña, silk and crocodile leather outerwear listed at £17,850, alongside an Alpha Yarn cashmere-and-mink blouson at £27,900.

    These numbers are eye-catching.

    But price alone isn’t the story.

    Stefano Ricci positions its menswear around luxurious fabrics and 100% Made in Italy craftsmanship, spanning formal tailoring, leisurewear and specialist materials.

    The brand’s Alpha Yarn collection, for example, is built around particularly fine cashmere, while its tailoring includes high-grade wool and cashmere constructions.

    This is luxury operating at a level where the difference between two seemingly similar jackets can become a conversation about fibre, weave, construction, finishing and provenance.

    The consumer isn’t simply buying the jacket.

    They’re buying the knowledge embedded inside it.


    THE REAL LUXURY FLEX IS KNOWING WHY

    This is where the conversation around these brands becomes more interesting than a simple list of expensive names.

    Because wealth and luxury are not the same thing.

    You can buy an expensive product without understanding it.

    And you can understand a remarkable product without needing everyone else to recognise it.

    That distinction is increasingly important in a luxury market saturated with visibility.

    The biggest brands have enormous cultural power.

    But cultural power comes with familiarity.

    The more people recognise something, the less exclusive recognition itself becomes.

    That doesn’t make famous luxury brands less valuable.

    It simply creates another market around them.

    A market where the selling point is not:

    “Everyone knows this.”

    It is:

    “You know what this is.”


    FROM LOGO TO LITERACY

    For a younger generation discovering luxury through Instagram, TikTok, celebrities and street style, the first stage of luxury is often recognition.

    You learn the logos.

    Then the silhouettes.

    Then the iconic bags.

    Then the watches.

    But eventually, if your interest goes deeper, you start asking different questions.

    Who made it?

    Where?

    How?

    From what?

    How long did it take?

    Why is this fabric different?

    Why does this jacket cost more than another one that looks almost identical?

    Why does one handbag have a waiting list?

    Why would someone choose a brand that fewer people recognise?

    That is where luxury literacy begins.

    And it may be the most interesting form of status in fashion today.

    Not simply possessing the object.

    Understanding the object.


    THE NEW STATUS SYMBOL

    The luxury industry has spent decades teaching consumers to look.

    Look at the logo.

    Look at the bag.

    Look at the car.

    Look at the watch.

    Look at the celebrity wearing it.

    But the deeper luxury market asks you to look closer.

    At the stitching.

    The fabric.

    The leather.

    The construction.

    The history.

    The atelier.

    The person who made it.

    And that creates an entirely different form of desire.

    It is quieter.

    More intimate.

    More difficult to manufacture.

    And much harder to fake.

    Because you can’t create decades of heritage overnight.

    You can’t manufacture a tailoring tradition with a marketing campaign.

    You can’t invent 180 years of leather craftsmanship.

    And you can’t simply print a logo and call it savoir-faire.


    SO, ARE THESE REALLY “THE BRANDS ONLY THE RICH KNOW”?

    Not literally.

    That would be too easy — and not quite true.

    These houses are known to fashion editors, collectors, menswear specialists, luxury professionals and dedicated enthusiasts around the world.

    But compared with the global recognition of Gucci, Chanel, Louis Vuitton, Dior or Hermès, their visibility is much more specialised.

    And that is the real story.

    The luxury world has layers.

    There is the luxury everyone recognises.

    Then there is the luxury people who are deeply interested in the subject recognise.

    And beneath that sits a world where the product itself becomes the credential.

    That’s where these names become interesting.


    THE LUXURY AFTER LUXURY

    Perhaps the biggest misconception about wealth is that once someone has enough money, they simply buy more expensive versions of the same things.

    The reality of specialist luxury is more nuanced.

    At the highest end, scarcity can matter.

    Craft can matter.

    Personalisation can matter.

    Heritage can matter.

    And sometimes, anonymity itself can become desirable.

    That is why a person might choose a jacket that very few people can identify.

    A handbag without an obvious monogram.

    A shirt made specifically for them.

    A trunk built around a personal request.

    A suit constructed from an extraordinary fabric that only another menswear obsessive would recognise.

    The flex isn’t always:

    “Look what I can afford.”

    Sometimes it is:

    “I know what this is.”


    THE LAST WORD

    Luxury doesn’t disappear when the logo does.

    It becomes harder to read.

    And perhaps that’s what makes it fascinating.

    Kiton turns tailoring into an almost obsessive pursuit of craft.

    Delvaux turns nearly two centuries of leather history into objects that don’t need to announce themselves.

    Moynat transforms the heritage of the travelling trunk into contemporary leather, travel and art.

    Charvet has made the humble shirt an exercise in personalisation — and in 2026, even Chanel came looking for that expertise.

    Stefano Ricci pushes Italian menswear into a realm where extraordinary materials and craftsmanship can command extraordinary prices.

    None of these houses needs to be completely unknown.

    They simply need to remain less obvious.

    Because once you’ve seen every logo, the real luxury may be discovering what lies behind them.

    The deeper you go into luxury, the less it needs to prove.


    INSYDE

    Luxury isn’t just about what you own.

    It’s about what you know.


  • THE ART OF INTIMACY

    THE ART OF INTIMACY

    8 Luxury Lingerie Houses Defining Modern Intimacy in 2026

    From historic Italian ateliers to experimental London studios and fashion-first New York labels, luxury lingerie is becoming less about what is hidden beneath clothing and more about craftsmanship, identity, design and the art of dressing.

    For decades, lingerie occupied a strange position in fashion.

    It was essential, but rarely treated as the main event. It shaped the silhouette, supported the body and completed the wardrobe — yet remained deliberately hidden beneath it.

    That relationship is changing.

    In 2026, lingerie has become increasingly visible in fashion, increasingly sophisticated in construction and increasingly connected to the wider luxury conversation. Lace, corsetry, structured bras, bodysuits and lingerie-inspired silhouettes are moving between the bedroom, the wardrobe and the runway.

    At Paris Fashion Week in September 2026, Chloé’s Spring/Summer 2027 collection incorporated lingerie-inspired harnesses and metallic bust straps alongside lace, tailoring and romantic silhouettes. Dior’s Spring 2027 presentation also played with exposed bras and intimate-wear references. (AP News)

    The message is difficult to miss.

    Lingerie is no longer simply underneath fashion. It is becoming part of fashion’s language.

    And behind that shift is a luxury industry with serious commercial momentum.

    One 2026 industry estimate values the global luxury lingerie market at approximately US$16.2 billion, forecasting it to reach US$34.1 billion by 2035. Another research firm estimates the 2026 market at approximately US$15.1 billion. Because these reports use different definitions and methodologies, the individual figures should not be treated as a single definitive market size. What they consistently indicate, however, is a category growing at roughly high-single-digit rates. (Business Research Insights)

    The wider lingerie market is considerably larger. IMARC estimates the global lingerie market at US$95.2 billion in 2025, with Asia-Pacific accounting for more than 40% of the market, and projects the global market to reach US$154.1 billion by 2034. (IMARC Group)

    India is part of that story.

    The country’s premium lingerie market was estimated at US$1.9 billion in 2025, according to IMARC, with a projected value of US$4.3 billion by 2034 and a forecast CAGR of 9.5% between 2026 and 2034. The report points to rising disposable incomes, increasing fashion consciousness, e-commerce, DTC brands, premium materials, customization and changing consumer preferences as important growth drivers. (IMARC Group)

    For a new generation of luxury consumers, therefore, lingerie is becoming much more than a functional purchase.

    It is becoming a fashion decision.

    And these eight houses demonstrate the different ways luxury can be built around the body.


    01 — LA PERLA

    The Italian Legacy

    Few names carry the historical weight of luxury lingerie quite like La Perla.

    The story began in 1954, when Ada Masotti established a corsetry atelier in Bologna, a city with a long tradition of textile and silk production. Her early work treated corsetry as an Italian craft rather than simply an item of underwear. (La Perla Atelier)

    That distinction became important.

    Over the decades, La Perla helped push lingerie beyond functionality and toward fashion, introducing colour, silk, more relaxed silhouettes and increasingly sophisticated forms of presentation.

    By the 1990s, the house was explicitly exploring the relationship between lingerie and outerwear, styling intimate pieces alongside shoes, jewellery and jackets. La Perla’s own historical account describes this period as one in which the boundary between public and private began to blur. (La Perla Atelier)

    That evolution is particularly relevant today.

    Luxury lingerie is no longer defined simply by whether a garment is expensive. Its value is increasingly connected to heritage, construction, material and the cultural history behind it.

    La Perla represents one of the earliest versions of that equation.

    INSYDE VIEW:
    Luxury lingerie begins with craftsmanship — and La Perla helped make that craftsmanship visible.


    02 — AGENT PROVOCATEUR

    Luxury With an Attitude

    La Perla built luxury around Italian craftsmanship.

    Agent Provocateur built it around attitude.

    Founded in London’s Soho in 1994, the house deliberately challenged the restrained conventions surrounding lingerie. The brand describes its origins as a moment when it sought to subvert established ideas around intimate apparel through provocative design, colourful collections and irreverent storytelling. (Agent Provocateur)

    That philosophy remains central to the house.

    Agent Provocateur combines elaborate construction with exclusive fabrics, embellishment and distinctive motifs, while its boutiques and storytelling position lingerie somewhere between fashion, fantasy and performance. (Agent Provocateur)

    British Vogue’s 2026 lingerie guide continues to place the house firmly within the luxury end of the category, highlighting its corsetry, garters, balconette bras and elaborate lace designs. (British Vogue)

    The important part is not simply that Agent Provocateur is provocative.

    It is that the brand made provocation itself part of the luxury proposition.

    In a market where many brands compete on minimalism, comfort or technical innovation, Agent Provocateur continues to operate through personality.

    INSYDE VIEW:
    Some luxury brands sell discretion. Agent Provocateur sells presence.


    03 — BORDELLE

    When Lingerie Becomes Architecture

    Bordelle takes a very different approach.

    Founded in London in 2009, the brand developed an aesthetic built around structure, geometry and adjustable construction. Its signature pieces combine customized satin elastic, luxury fabrics and 24-karat-gold-plated hardware. (Bordelle)

    The result is instantly recognizable.

    Rather than simply decorating the body, Bordelle creates a framework around it.

    The brand’s designs are developed in London and handmade by teams in London and at its production facility in Cluj, Romania. It works with European suppliers for specialist materials including embroidered tulle, bespoke elastics and gold-plated hardware. (Bordelle)

    Bordelle also occupies an unusual position within retail.

    The brand says it is stocked alongside ready-to-wear labels at selected department stores, concept stores and specialist boutiques in more than 25 countries. (Bordelle)

    That matters because it reflects one of the biggest developments in contemporary lingerie:

    the category is increasingly being treated as fashion.

    A Bordelle piece doesn’t necessarily need to disappear beneath a dress.

    It can become the dress.

    It can become the silhouette.

    It can become the statement.

    INSYDE VIEW:
    Bordelle turns the architecture of the body into the architecture of the garment.


    04 — FLEUR DU MAL

    New York’s Fashion-First Revolution

    Luxury lingerie doesn’t have to come from a century-old European atelier.

    Fleur du Mal represents the new generation.

    Founded by Jennifer Zuccarini in 2012, the New York label was built around the idea that lingerie should operate as fashion rather than remain confined to the bedroom. The brand describes its philosophy through three ideas: fashion first, designed to be seen, and delicate with edge. (Fleur du Mal)

    That positioning is important.

    Fleur du Mal works across lingerie, bodysuits, slip dresses, ready-to-wear and lingerie-inspired pieces. Its materials include silk, organic cotton and Leavers lace, while its designs are deliberately intended to move between private and public dressing. (Fleur du Mal)

    British Vogue’s 2026 lingerie guide similarly highlights Fleur du Mal for its contemporary luxury bras and use of French Leavers lace. (British Vogue)

    The brand represents a broader shift in consumer behaviour.

    Today’s luxury customer does not necessarily divide a wardrobe into rigid categories.

    A bodysuit can be lingerie.

    A bodysuit can also be eveningwear.

    A slip can be sleepwear.

    A lace bra can sit beneath a tailored jacket.

    The boundaries are becoming deliberately blurred.

    INSYDE VIEW:
    The modern luxury wardrobe doesn’t always distinguish between what is worn underneath and what is meant to be seen.


    05 — CARINE GILSON

    Where Lingerie Meets Couture

    Some houses make lingerie.

    Carine Gilson makes couture lingerie.

    The designer’s story began in the 1990s after she discovered a Brussels atelier specializing in fine underslips. She subsequently established her own couture lingerie line, building the house around craftsmanship and handwork. (Carine Gilson)

    The atelier is the heart of the brand.

    Carine Gilson states that processes including cutting, pleating, bias work and the inlaying of Chantilly lace are performed by hand. The house deliberately manufactures limited quantities because of the specialist nature of the work. (Carine Gilson)

    This is where the word luxury becomes meaningful.

    Luxury is not simply a higher price.

    It can be the time required to produce something.

    The skill required to produce it.

    The rarity of the technique.

    The quality of the material.

    And the number of hands involved before a finished garment reaches its owner.

    Carine Gilson embodies that philosophy almost literally.

    The result is lingerie that sits closer to the world of couture than conventional intimate apparel.

    INSYDE VIEW:
    When the hand of the artisan becomes visible in the garment, lingerie enters the territory of couture.


    06 — I.D. SARRIERI

    The Couture Lingerie Proposition

    Romania has developed a distinctive place within Europe’s luxury lingerie landscape, and I.D. Sarrieri represents one of its most recognizable luxury propositions.

    Established at the beginning of the 21st century, the house built its identity around glamour, craftsmanship and a deliberate return to highly feminine design. (I.D. Sarrieri)

    Chantilly lace is central to its aesthetic, while collections incorporate details such as embroidery, crystals and elaborate bustier construction. (I.D. Sarrieri)

    But the most interesting aspect of I.D. Sarrieri is its approach to visibility.

    The house explicitly designs pieces intended to be seen — lace under a crisp white shirt, a chemise styled for evening or a corset-inspired bodice paired with tailoring. (I.D. Sarrieri)

    Its current collections also demonstrate the price architecture of the luxury category. Selected bustiers on the brand’s US site are listed at roughly US$400–US$1,000, illustrating how couture-inspired construction can move intimate apparel firmly into luxury-fashion pricing. (I.D. Sarrieri)

    The proposition is straightforward:

    Lingerie does not have to wait for the clothes to come off.

    It can be part of the clothes.

    INSYDE VIEW:
    The future of lingerie may not be about hiding it better — but styling it better.


    07 — FLEUR OF ENGLAND

    The Luxury of Materials

    Fleur of England represents a quieter interpretation of luxury.

    There is less emphasis on shock.

    More emphasis on touch.

    The British house uses French lace, silk and gold-plated hardware across its collections, with production carried out in Europe. Current pieces include French lace paired with silk satin and 24-karat-gold-plated hardware. (Fleur of England)

    The distinction is subtle but important.

    Two garments can both be called lace lingerie.

    They can still be completely different objects.

    The provenance of the lace, the weave, the softness, the finishing, the way it is cut and how it interacts with the body all affect the final garment.

    Fleur of England places those details at the centre of its proposition.

    It is luxury designed to be felt before it is noticed.

    INSYDE VIEW:
    Sometimes the most luxurious detail is the one you feel before you see it.


    08 — KIKI DE MONTPARNASSE

    When Intimacy Becomes Luxury

    Kiki de Montparnasse approaches luxury lingerie from a different direction altogether.

    Rather than treating lingerie purely as fashion, the brand has built a broader world around intimacy, sensuality and personal experience.

    Its proposition extends beyond lingerie into ready-to-wear, accessories and sexual wellness, turning the brand into a lifestyle universe rather than simply an intimate-apparel label.

    That matters because luxury is increasingly becoming experiential.

    A handbag can represent status.

    A watch can represent heritage.

    A private club can represent access.

    Lingerie can represent something more personal:

    the experience of oneself.

    That creates an unusual luxury proposition.

    Most luxury products are designed to be seen.

    Lingerie can be valuable precisely because it does not have to be.

    It can exist entirely for the person wearing it.

    In a culture where almost everything is photographed, posted and displayed, that privacy becomes increasingly interesting.

    INSYDE VIEW:
    The ultimate luxury may be the thing nobody else knows you’re wearing.


    THE NEW LUXURY OF INTIMACY

    Why the Category Is Growing

    The rise of luxury lingerie is part of a larger transformation in the luxury consumer.

    For years, luxury was heavily associated with visible symbols of wealth: handbags, watches, automobiles, jewellery and logos.

    That definition is expanding.

    Luxury today can mean craftsmanship.

    It can mean personalization.

    It can mean scarcity.

    It can mean sustainability.

    It can mean an exceptional experience.

    And sometimes, it can mean buying something beautiful that nobody else will ever see.

    That is particularly relevant to younger consumers.

    British Vogue’s 2026 lingerie coverage reflects a market that now spans functional underwear, everyday essentials, sustainable labels and luxury houses — demonstrating how fragmented the modern lingerie landscape has become. (British Vogue)

    The premium customer is no longer necessarily buying lingerie for one reason.

    Comfort matters.

    Fit matters.

    Design matters.

    Materials matter.

    Identity matters.

    And increasingly, the distinction between lingerie and fashion matters less.


    THE BUSINESS OF THE PRIVATE WARDROBE

    The numbers suggest that this is not merely a fashion moment.

    It is a business opportunity.

    Global estimates for the luxury lingerie market vary by research methodology, but current 2026 studies consistently place the category in the mid-teens of billions of US dollars, with projected growth toward roughly US$27–34 billion by the early-to-mid 2030s. (Business Research Insights)

    The wider lingerie industry is substantially larger, with IMARC estimating the global market at US$95.2 billion in 2025 and projecting US$154.1 billion by 2034. Asia-Pacific represented more than 40% of the global market in 2025. (IMARC Group)

    That Asian concentration matters for brands looking beyond Europe and North America.

    India is particularly interesting.

    The country’s overall lingerie market was estimated at US$6.4 billion in 2026, according to IMARC, with a forecast of US$12 billion by 2034. The economy segment remains dominant, accounting for 69% of the market in 2025, but IMARC identifies premiumization as an important emerging trend as consumers increasingly seek better materials, branded products, comfort and design differentiation. (IMARC Group)

    That creates an important distinction.

    The future of Indian luxury lingerie is unlikely to be about replacing the mass market.

    It is about creating a premium layer above it.

    As India’s urban consumer becomes more exposed to international fashion, global luxury and DTC commerce, the intimate wardrobe is becoming another space in which consumers can express taste.

    For global lingerie houses, that makes India more than simply another emerging retail market.

    It is a developing luxury audience.


    WHAT ACTUALLY MAKES LINGERIE LUXURY?

    A high price does not automatically make a garment luxurious.

    The strongest luxury lingerie houses tend to build their proposition around several elements.

    MATERIAL

    Fine silk, specialist lace, embroidered tulle and high-quality technical fabrics can dramatically change the experience of a garment.

    CRAFTSMANSHIP

    Hand-cut lace, hand finishing, specialist construction and atelier production introduce skills and time that cannot easily be replicated through mass manufacturing.

    FIT

    Lingerie sits directly against the body.

    That makes precision particularly important.

    A beautiful garment that doesn’t fit properly is not a successful luxury product.

    DESIGN LANGUAGE

    The strongest houses are recognizable without necessarily relying on logos.

    La Perla has its Italian heritage.

    Agent Provocateur has provocation.

    Bordelle has architecture.

    Fleur du Mal has fashion crossover.

    Carine Gilson has couture craftsmanship.

    I.D. Sarrieri has glamour and elaborate lacework.

    The identity becomes part of the product.

    SCARCITY

    Limited production can make craftsmanship economically viable while also creating exclusivity.

    EXPERIENCE

    Packaging, boutiques, private appointments, fitting services and storytelling all contribute to the modern luxury proposition.

    CULTURAL RELEVANCE

    Perhaps the most important element is meaning.

    A garment can be expensive.

    But without a point of view, it is simply expensive underwear.


    FROM BEDROOM TO RUNWAY

    The most significant change may ultimately be cultural rather than commercial.

    Lingerie is escaping the private wardrobe.

    It is being layered beneath tailoring.

    Worn beneath sheer fabrics.

    Built into bodysuits.

    Transformed into corsetry.

    Reinterpreted through metallic structures.

    And increasingly incorporated directly into ready-to-wear.

    Chloé’s Spring/Summer 2027 collection is one recent example. Designer Chemena Kamali incorporated romantic harnesses and metallic bust straps into a collection that otherwise balanced lace, tailoring and substantial outerwear. (AP News)

    Dior’s Spring 2027 show similarly brought exposed bras and intimate-wear references into its runway vocabulary. (AP News)

    This is not necessarily the death of traditional lingerie.

    It is something more interesting.

    The category is expanding.

    The garment that was once hidden can now be styled.

    The garment that was once private can become fashion.

    And the garment that was once purely functional can become an object of design.


    THE NEXT ERA OF LUXURY LINGERIE

    The future of luxury lingerie will probably not belong to one aesthetic.

    There will be heritage houses protecting traditional techniques.

    Independent ateliers producing extremely limited quantities.

    Fashion-led labels turning intimate pieces into ready-to-wear.

    Experimental designers building new forms around the body.

    Digitally native brands creating communities around fit and identity.

    And established luxury houses continuing to borrow lingerie codes for the runway.

    The category is becoming more diverse because the meaning of luxury itself is becoming more diverse.

    For one consumer, luxury may mean an Italian silk corset.

    For another, it may be an architectural Bordelle harness.

    For another, a hand-finished Carine Gilson slip.

    For someone else, it may simply be a perfectly fitted garment made from exceptional fabric.

    There is no single definition.

    And perhaps that is exactly the point.


    THE INSYDE TAKE

    Luxury lingerie is entering a new era.

    The old definition was straightforward:

    Beautiful underwear for private moments.

    The new definition is considerably broader.

    It is craftsmanship against the skin.

    It is fashion that can be hidden or revealed.

    It is heritage, material, design and identity compressed into a garment that may occupy only a fraction of the wardrobe.

    And as luxury moves beyond visible status toward more personal forms of expression, lingerie has the potential to become one of fashion’s most intimate luxury categories.

    Because the most interesting luxury isn’t always the loudest.

    Sometimes it isn’t displayed.

    Sometimes it isn’t photographed.

    Sometimes nobody else even knows it exists.

    Sometimes luxury is simply knowing what you’re wearing.


    INSYDE EDITORIAL NOTE

    This editorial is intentionally not a ranking. The eight houses represent different interpretations of luxury lingerie — heritage, provocation, architecture, fashion crossover, couture craftsmanship, glamour, material excellence and intimacy.

    Research and market data reviewed: 1 October 2026.

  • The New Heirloom: The Luxury of Legacy

    The New Heirloom: The Luxury of Legacy

    Why exceptional jewellery is becoming one of luxury’s most personal forms of wealth.

    There is a difference between owning something valuable and owning something that matters.

    The distinction becomes clearer at the highest levels of luxury.

    When access is no longer the challenge, another question begins to matter: what is actually worth keeping?

    A remarkable piece of jewellery can answer that question rather elegantly.

    It does not need to occupy a room.

    It does not need a chauffeur.

    It does not need a marina or a private hangar.

    It can sit quietly in a private collection, emerge for one evening, and carry more meaning than an object ten times its size.

    That is the peculiar power of exceptional jewellery.

    It is wealth made intimate.

    Not necessarily wealth designed to be seen by everyone, but wealth expressed through rarity, provenance, craftsmanship and personal significance.

    And increasingly, that is where luxury is heading.

    When Price Stops Being the Point

    For a certain kind of buyer, price is an important consideration.

    For the truly affluent, it is often a secondary one.

    The question is no longer whether something is expensive enough to justify its place in a collection.

    It is whether it is exceptional enough to deserve one.

    That distinction changes the entire conversation.

    A rare Colombian emerald.

    An extraordinary Burmese ruby with compelling provenance.

    A historic diamond.

    A one-of-one commission.

    A piece created by an exceptional atelier.

    A jewel whose craftsmanship reveals itself only when examined closely.

    These are not interchangeable luxury goods.

    They are objects with characteristics that cannot simply be reproduced by increasing a budget.

    That is where jewellery becomes particularly interesting.

    Money can secure access. It cannot manufacture rarity.

    The Value of Knowing What You Are Looking At

    There is a sophistication to jewellery that rewards knowledge.

    Two stones can appear similar to an untrained eye and possess radically different histories, qualities and desirability.

    Two pieces can carry similar materials and have completely different levels of craftsmanship.

    The difference may be in the cut.

    The setting.

    The proportions.

    The origin.

    The stone selection.

    The construction.

    The hand behind it.

    Or simply the judgement of the person who commissioned it.

    This is why the most sophisticated jewellery culture is not necessarily loud.

    It is informed.

    A collector does not need a room to recognise a remarkable stone.

    Sometimes a glance across a dinner table is enough.

    That is a very different kind of status.

    Recognition becomes selective.

    Jewellery Is Wealth You Can Wear

    A residence remains at its address.

    A yacht remains at sea.

    A private aircraft moves according to a flight plan.

    Jewellery has a different kind of freedom.

    It travels with its owner.

    A necklace can move between continents.

    A ring can pass from a boardroom to a private dinner.

    A pair of earrings can become part of an evening’s entire visual language.

    The object is not simply stored wealth.

    It becomes portable identity.

    And because it is worn directly against the body, jewellery occupies an unusually intimate position within a luxury collection.

    You don’t simply own it.

    You live with it.

    The Quiet Power of Exceptional Craftsmanship

    At the top end of jewellery, craftsmanship is rarely there for spectacle.

    It is there for perfection.

    The setting has to hold the stone without overpowering it.

    The proportions have to feel inevitable.

    The metal has to respond to light correctly.

    The construction has to survive years of wear without losing its character.

    The smallest detail can determine whether a piece feels merely expensive or genuinely exceptional.

    This is where the great ateliers distinguish themselves.

    The finished piece may appear effortless.

    That is precisely the point.

    Exceptional craftsmanship hides its own difficulty.

    The more refined the object, the less it needs to explain itself.

    The Stone Is Only the Beginning

    A remarkable gemstone carries its own identity.

    Its colour.

    Its character.

    Its origin.

    Its rarity.

    Its history.

    Its imperfections can sometimes become part of what makes it desirable.

    The sophisticated collector therefore isn’t necessarily searching for the largest stone.

    They may be searching for the stone that cannot easily be replaced.

    That distinction matters.

    Size can be measured.

    Rarity has to be understood.

    And in the highest echelons of collecting, uniqueness tends to outlast spectacle.

    India’s Jewellery Legacy Is an Extraordinary Advantage

    India enters this conversation with something many emerging luxury markets would struggle to create from scratch:

    centuries of jewellery culture.

    Kundan.

    Jadau.

    Polki.

    Meenakari.

    Temple jewellery.

    Goldsmithing traditions.

    Gem-setting techniques.

    Regional craftsmanship passed between generations.

    These aren’t simply decorative traditions.

    They are sophisticated systems of making.

    The opportunity for contemporary Indian luxury is therefore not to reproduce the European model of jewellery.

    It is to take India’s enormous craft heritage and give it a new vocabulary.

    The most compelling future Indian jewellery may not look traditionally Indian at first glance.

    It may be architectural.

    Minimal.

    Sculptural.

    Unexpected.

    But the intelligence of the craft can remain underneath.

    That is where heritage becomes contemporary.

    The Indian Jewel of Tomorrow

    Imagine a contemporary necklace constructed using a centuries-old technique.

    A sculptural ring inspired by Indian architecture.

    A modern interpretation of Jadau without ceremonial excess.

    A rare gemstone framed with the restraint of contemporary design.

    A private commission that combines an inherited stone with a completely new setting.

    That is far more interesting than simply placing an Indian motif on a luxury product.

    The real opportunity is reinvention without losing provenance.

    If Indian jewellery houses can achieve that balance, the result could become globally significant.

    Not because it is Indian.

    But because it is exceptional.

    When Jewellery Becomes a Private Language

    There is a particular pleasure in owning something that does not need to announce itself.

    A necklace without a visible logo.

    A ring whose significance is understood only by a handful of collectors.

    A stone selected because of its provenance rather than its recognisability.

    A private commission that exists nowhere else.

    This is where jewellery enters the territory of discreet luxury.

    The object does not ask for attention.

    It rewards attention.

    And that distinction is increasingly important.

    The old luxury language often said:

    Look at what I own.

    The newer language can say:

    Look closely.

    The Heirloom Is Changing

    Historically, an heirloom was something that survived long enough to be inherited.

    Today, the most thoughtful collectors can design for inheritance from the beginning.

    A piece commissioned for a milestone.

    A gemstone selected with a future daughter or son in mind.

    An existing family jewel redesigned without losing its original stone.

    A new piece created specifically to become part of a family’s visual history.

    The object becomes more than an acquisition.

    It becomes a decision about the future.

    And that may be one of the most sophisticated reasons to buy exceptional jewellery.

    You are not necessarily buying for yourself alone.

    You are deciding what deserves to survive you.

    From Jewellery to Family Archive

    This is where jewellery becomes almost impossible to price.

    A necklace can carry the memory of a wedding.

    A ring can carry the history of a marriage.

    A stone can be reset across generations.

    A brooch can return decades later at another family celebration.

    The financial value may remain measurable.

    The emotional value does not.

    And over time, the two can become inseparable.

    A remarkable jewel is therefore capable of becoming something unusual:

    a physical archive of a family.

    That is a form of wealth no balance sheet can properly capture.

    The Collector’s Eye

    Serious collecting is rarely about accumulation for its own sake.

    The most interesting private collections tend to have a point of view.

    They may focus on exceptional stones.

    A particular period.

    A house.

    A designer.

    A technique.

    A geographical tradition.

    Or simply pieces that tell compelling stories.

    The collector begins to develop an eye.

    They notice things.

    The quality of a setting.

    The way a stone is cut.

    The originality of a design.

    The difference between an important piece and merely an expensive one.

    At that point, buying becomes less about consumption and more about curation.

    And curation is one of the defining characteristics of sophisticated luxury.

    When a Jewel Becomes Art

    There is a moment when jewellery stops functioning as an accessory.

    It becomes an artwork.

    A one-of-one commission.

    An extraordinary stone.

    An experimental setting.

    A collaboration between an artist and a master jeweller.

    A piece whose proportions are so deliberate that it could belong in a gallery as naturally as it belongs on the body.

    At that level, the question is no longer whether the piece matches an outfit.

    It is whether the object itself deserves to exist.

    That is a much higher standard.

    And it is where jewellery enters the world of collecting.

    The Investment Question Is Almost the Wrong Question

    Luxury jewellery is frequently discussed as an investment.

    That conversation has its place.

    Certain exceptional pieces can command significant prices in the secondary market, particularly when rarity, provenance, craftsmanship and collector demand converge.

    But reducing exceptional jewellery to financial performance misses its more enduring value.

    The serious collector isn’t necessarily asking whether a jewel will outperform an investment portfolio.

    They are asking whether it possesses lasting desirability.

    Will the stone still be remarkable?

    Will the craftsmanship still be respected?

    Will the design still feel relevant?

    Will the provenance still matter?

    Will someone want it decades from now?

    That is a different definition of value.

    Financial value can fluctuate. Cultural value can compound.

    The New Luxury Is Personal

    The next generation of high jewellery is unlikely to be defined simply by larger stones or heavier pieces.

    It will be defined by individuality.

    Private commissions.

    Unusual gemstones.

    Exceptional provenance.

    Artist collaborations.

    Heritage techniques.

    Contemporary Indian craftsmanship.

    One-of-one designs.

    And pieces that could never have been created for anyone else.

    This is where luxury becomes most interesting.

    The object is no longer simply selected.

    It is authored.

    The collector becomes part of the creative process.

    The final piece carries something of both sides: the skill of the maker and the identity of the person who commissioned it.

    That is difficult to mass-produce.

    And therefore, increasingly valuable.

    Beyond the Logo

    The future of jewellery may belong to pieces that do not immediately reveal their price, their house or even their significance.

    A rare stone.

    An exceptional setting.

    A technique recognised by a specialist.

    A piece with a story known only to the owner and a small circle of people who understand its importance.

    This is not the disappearance of the luxury brand.

    It is the evolution of luxury beyond the brand.

    The logo tells you who made something.

    The craftsmanship tells you why it matters.

    The provenance tells you where it has been.

    But the story tells you why it should be kept.

    The Things We Choose to Keep

    Perhaps that is why jewellery has survived every change in fashion.

    Trends disappear.

    Designers change.

    Houses rise and fall.

    But a remarkable jewel can remain.

    It can cross generations.

    It can carry a story long after its original owner is gone.

    It can be worn again decades later and somehow feel completely right.

    Because the most valuable thing about jewellery has never been simply what it is made from.

    It is what it remembers.

    And perhaps that is the ultimate luxury.

    Not owning the largest stone.

    Not wearing the most recognisable name.

    Not proving how much something cost.

    But possessing something rare enough, beautiful enough and meaningful enough to become part of someone else’s future.

    The finest jewellery doesn’t simply belong to a person.

    For a while, a person becomes part of its story.

    INSYDE — Beyond the Spotlight.

  • GUCCI goes MADE IN CHINA?

    GUCCI goes MADE IN CHINA?

    Inside the sneaker challenging what “Made in Italy” means in modern luxury.

    By INSYDE

    There are few phrases in fashion more powerful than Made in Italy.

    Two words can evoke Florence workshops, generations of artisans, hand-finished leather and the kind of craftsmanship luxury houses have spent decades turning into mythology.

    So when a Gucci sneaker arrives with “Made in China” printed on its product information, it creates an uncomfortable question.

    Not because China cannot manufacture luxury products.

    But because, for a brand like Gucci, where something is made has always been part of the story.

    Gucci has now introduced specific sneaker models manufactured in China, including the Drip, the first sneaker designed under Demna’s creative direction at Gucci. The product is officially listed by Gucci as “Made in China.” A second slip-on sneaker from the same Primavera collection also carries the designation.

    The internet can reduce that story to three words:

    Gucci. Made in China.

    The reality is considerably more interesting.

    Because this isn’t really a story about China replacing Italy.

    It is a story about what luxury means when the world that makes it becomes increasingly global.


    THE SNEAKER THAT STARTED THE CONVERSATION

    The Drip is not designed to look like a traditional Italian luxury sneaker.

    Gucci describes it as a streamlined silhouette that combines the visual language of a basketball shoe with the ease of a loafer. It is available across materials and colourways including nylon, suede and GG canvas. Gucci identifies it as Demna’s first sneaker for the house.

    Its positioning is also distinctly contemporary.

    This is not a product attempting to recreate the romance of an old Gucci atelier.

    It is a product designed for a fashion landscape where sneakers can carry the cultural weight once reserved for handbags, watches and couture.

    And then comes the detail that changes the conversation:

    Made in China.

    The sneaker is still sold through Gucci.

    It still carries the Gucci name.

    It still sits within Gucci’s luxury ecosystem.

    And depending on the market and version, it carries a price approaching the €800–$1,000 range.

    That is where the question becomes unavoidable.

    If the product is luxury, what exactly makes it luxury?


    NO, GUCCI ISN’T MOVING TO CHINA

    Before the headlines get ahead of the facts, there is an important distinction to make.

    Gucci has not announced a broad relocation of its manufacturing from Italy to China.

    According to Gucci’s statement reported by Reuters, Italy remains at the heart of its manufacturing model and identity, and the company has no broader plan to move production outside Italy. Gucci said the Chinese manufacturer was selected for the technical expertise and capabilities needed for the particular sneaker.

    Gucci’s wider manufacturing structure tells the same story.

    The house says that most Gucci products are made in Italy, while different categories are manufactured in other specialist markets. Gucci states that its watches are mainly produced in Switzerland, fragrances in France and the UK, cosmetics in the EU and some eyewear in Japan.

    Its responsible supply-chain documentation states that 95% of Gucci’s manufacturers are based in Italy.

    So the accurate story is not:

    Gucci is abandoning Italy.

    It is:

    Gucci has chosen China for the manufacturing of specific sneakers.

    That distinction matters.


    WHY CHINA?

    For years, “Made in China” was often used in luxury conversations as shorthand for mass production.

    That perception is increasingly outdated.

    China has become one of the world’s major manufacturing centres, including in footwear, technical materials and highly specialised production.

    And Gucci’s public explanation for the Drip is not that China was chosen simply because it is cheaper.

    The company has specifically pointed to the manufacturer’s technical know-how and capabilities as the reason for the decision.

    That doesn’t mean cost is irrelevant to the economics of global luxury.

    Gucci’s parent company Kering reported that Gucci’s first-half 2026 revenue declined 5% on a comparable basis to €2.757 billion, while the group also reported sequential improvement during the period. Mainland China remained a challenging market, although trends were improving.

    The broader luxury industry is navigating a more demanding consumer environment, with brands looking for new ways to create relevance, excitement and value.

    But there is not enough public evidence to say that Gucci selected China specifically to reduce manufacturing costs.

    And that is precisely why the story is more interesting without that assumption.


    THE MYTH OF “MADE IN ITALY”

    Luxury has always understood the power of geography.

    Paris.

    Milan.

    Florence.

    Geneva.

    Tokyo.

    Certain places have become synonymous with particular forms of expertise.

    For Gucci, Italy isn’t simply a manufacturing location.

    It is part of the brand’s cultural identity.

    But modern luxury supply chains are rarely as simple as a single country.

    A product can involve materials, components, specialist techniques and manufacturing processes spanning several countries before it reaches a customer.

    European Union rules on non-preferential origin recognise this complexity, generally determining origin for goods involving multiple countries through the concept of last substantial transformation, subject to the applicable rules.

    That doesn’t make “Made in Italy” meaningless.

    Quite the opposite.

    It demonstrates why provenance is a sophisticated concept rather than simply a postcode.

    The real question is no longer only:

    Where was it made?

    It is:

    What expertise was required to make it?


    FROM COUNTRY OF ORIGIN TO COUNTRY OF EXPERTISE

    This may be where luxury is heading.

    A watch can be Swiss.

    An eyewear collection can involve Japanese manufacturing.

    A fragrance can be produced in France.

    A sneaker can be manufactured in China.

    And the same global luxury house can still maintain a distinctly European identity.

    Gucci’s own manufacturing footprint already reflects this reality.

    The old luxury equation was relatively simple:

    Italy = craftsmanship.

    The new equation is considerably more complicated:

    Design + expertise + materials + technology + craftsmanship + scarcity + brand identity + cultural relevance.

    Geography remains part of that equation.

    But it is no longer necessarily the entire equation.


    THE PRICE OF THE NAME

    Then there is the uncomfortable part.

    What exactly is the customer paying for?

    A sneaker doesn’t cost hundreds of dollars because of the rubber sole alone.

    The price incorporates an entire ecosystem:

    Design.

    Creative direction.

    Materials.

    Manufacturing.

    Distribution.

    Brand heritage.

    Marketing.

    Retail experience.

    Cultural relevance.

    And, inevitably, the name printed on the box.

    That last element is enormous.

    Luxury has always sold objects, but it has also sold meaning.

    A Gucci handbag is not simply leather.

    A Rolex is not simply steel.

    A Ferrari is not simply an engine.

    The object becomes valuable partly because of the story surrounding it.

    Which brings us back to the label.

    If a Gucci sneaker is manufactured in China but designed under Demna, developed within Gucci’s creative and commercial system, sold through Gucci boutiques and presented as a Gucci product, does its country of manufacture change its luxury status?

    There is no universal answer.

    For some consumers, provenance will remain fundamental.

    For others, design and cultural relevance may matter more.

    And that tension is exactly what makes this moment worth watching.


    DEMNA AND THE NEW GUCCI

    The timing makes the story even more significant.

    The Drip isn’t simply another Gucci sneaker.

    It is part of the beginning of Demna’s Gucci era.

    The designer’s arrival represents a new creative chapter for one of fashion’s most recognisable houses, and the Drip is one of the first products through which that direction becomes visible. Gucci itself identifies it as Demna’s first sneaker for the brand.

    Its design feels deliberately contemporary.

    Less about preserving an image of luxury.

    More about asking what luxury can look like now.

    That distinction matters.

    The modern luxury consumer doesn’t necessarily want a product that looks expensive.

    They want something that means something.

    Something recognisable without being obvious.

    Something culturally relevant.

    Something that can move between fashion, street culture, social media and everyday life.

    The Drip belongs to that world.

    Its manufacturing origin simply adds another layer to the conversation.


    WHEN THE LABEL BECOMES THE STORY

    There is a strange irony here.

    Luxury brands spend enormous amounts of money creating narratives around their products.

    With the Drip, the manufacturing label has become part of the narrative itself.

    That can be complicated.

    Reuters reported that some luxury-industry analysts see potential tension between China-made products and Gucci’s long-standing association with Italian craftsmanship. Those are industry interpretations, however, rather than evidence that the product has already damaged Gucci’s positioning or consumer demand.

    The eventual answer will come from consumers.

    Not headlines.

    Not social-media arguments.

    Not assumptions about where a product should be made.

    But whether customers believe the object delivers enough design, quality, desirability and cultural value to justify its price.

    Because luxury has always been, at its core, an agreement between a brand and its customer.

    The brand says:

    This is special.

    The customer decides whether to believe it.


    THE NEW LUXURY MAP

    Perhaps the most important consequence of Gucci’s China-made sneaker isn’t what it says about China.

    It is what it says about Italy.

    And, more broadly, about the future of luxury.

    For decades, country of origin functioned almost like a guarantee.

    Made in Italy.

    Made in Switzerland.

    Made in France.

    The location itself communicated expertise.

    But as technology improves and manufacturing capabilities become increasingly distributed around the world, luxury houses have more choices than ever.

    The next generation of luxury may therefore be less interested in a single manufacturing postcode and more interested in why a particular place was chosen.

    Where is the best leather?

    Where is the strongest technical expertise?

    Where is the most appropriate craftsmanship?

    Where can a particular construction be executed at the required standard?

    Where does the product make the most sense?

    Those questions are far more complicated than simply asking whether something was made in Italy or China.

    And they may become increasingly important as luxury brands rethink how they manufacture, price and position products.


    SO, DOES “MADE IN CHINA” CHANGE GUCCI?

    It changes the conversation.

    It doesn’t erase Gucci’s Italian manufacturing heritage.

    It doesn’t mean Gucci has moved its entire production operation to China.

    It doesn’t make the sneaker counterfeit.

    And it doesn’t, by itself, tell us whether the product is better or worse.

    What it does do is challenge one of luxury’s oldest assumptions:

    that geography and value are inseparable.

    Gucci continues to have the overwhelming majority of its manufacturers in Italy, while also using specialist manufacturing capabilities across different countries and, now, China for specific sneaker models.

    That may be less dramatic than the internet’s version of the story.

    But it is far more revealing.

    Because the future of luxury may not be about choosing between Italy and China.

    It may be about understanding that modern luxury can be simultaneously local in identity and global in production.

    The atelier still matters.

    The designer still matters.

    The material still matters.

    The craftsmanship still matters.

    But so does technology. So does cultural relevance. So does the ability to manufacture something precisely for the way people want to live now.

    The Gucci Drip has simply made that evolution visible.

    And perhaps that is the real story behind the label.

    Luxury isn’t losing its borders.

    It’s learning how to exist beyond them.


    INSYDE

    The world of luxury is changing. We’re watching what comes next.

    Sources: Gucci product listings and FAQ; Gucci Responsible Supply Chain documentation; Kering H1 2026 results; Reuters reporting, September 2026; European Commission rules on non-preferential origin.

    Inside the sneaker challenging what “Made in Italy” means in modern luxury.

    By INSYDE

    There are few phrases in fashion more powerful than Made in Italy.

    Two words can evoke Florence workshops, generations of artisans, hand-finished leather and the kind of craftsmanship luxury houses have spent decades turning into mythology.

    So when a Gucci sneaker arrives with “Made in China” printed on its product information, it creates an uncomfortable question.

    Not because China cannot manufacture luxury products.

    But because, for a brand like Gucci, where something is made has always been part of the story.

    Gucci has now introduced specific sneaker models manufactured in China, including the Drip, the first sneaker designed under Demna’s creative direction at Gucci. The product is officially listed by Gucci as “Made in China.” A second slip-on sneaker from the same Primavera collection also carries the designation.

    The internet can reduce that story to three words:

    Gucci. Made in China.

    The reality is considerably more interesting.

    Because this isn’t really a story about China replacing Italy.

    It is a story about what luxury means when the world that makes it becomes increasingly global.


    THE SNEAKER THAT STARTED THE CONVERSATION

    The Drip is not designed to look like a traditional Italian luxury sneaker.

    Gucci describes it as a streamlined silhouette that combines the visual language of a basketball shoe with the ease of a loafer. It is available across materials and colourways including nylon, suede and GG canvas. Gucci identifies it as Demna’s first sneaker for the house.

    Its positioning is also distinctly contemporary.

    This is not a product attempting to recreate the romance of an old Gucci atelier.

    It is a product designed for a fashion landscape where sneakers can carry the cultural weight once reserved for handbags, watches and couture.

    And then comes the detail that changes the conversation:

    Made in China.

    The sneaker is still sold through Gucci.

    It still carries the Gucci name.

    It still sits within Gucci’s luxury ecosystem.

    And depending on the market and version, it carries a price approaching the €800–$1,000 range.

    That is where the question becomes unavoidable.

    If the product is luxury, what exactly makes it luxury?


    NO, GUCCI ISN’T MOVING TO CHINA

    Before the headlines get ahead of the facts, there is an important distinction to make.

    Gucci has not announced a broad relocation of its manufacturing from Italy to China.

    According to Gucci’s statement reported by Reuters, Italy remains at the heart of its manufacturing model and identity, and the company has no broader plan to move production outside Italy. Gucci said the Chinese manufacturer was selected for the technical expertise and capabilities needed for the particular sneaker.

    Gucci’s wider manufacturing structure tells the same story.

    The house says that most Gucci products are made in Italy, while different categories are manufactured in other specialist markets. Gucci states that its watches are mainly produced in Switzerland, fragrances in France and the UK, cosmetics in the EU and some eyewear in Japan.

    Its responsible supply-chain documentation states that 95% of Gucci’s manufacturers are based in Italy.

    So the accurate story is not:

    Gucci is abandoning Italy.

    It is:

    Gucci has chosen China for the manufacturing of specific sneakers.

    That distinction matters.


    WHY CHINA?

    For years, “Made in China” was often used in luxury conversations as shorthand for mass production.

    That perception is increasingly outdated.

    China has become one of the world’s major manufacturing centres, including in footwear, technical materials and highly specialised production.

    And Gucci’s public explanation for the Drip is not that China was chosen simply because it is cheaper.

    The company has specifically pointed to the manufacturer’s technical know-how and capabilities as the reason for the decision.

    That doesn’t mean cost is irrelevant to the economics of global luxury.

    Gucci’s parent company Kering reported that Gucci’s first-half 2026 revenue declined 5% on a comparable basis to €2.757 billion, while the group also reported sequential improvement during the period. Mainland China remained a challenging market, although trends were improving.

    The broader luxury industry is navigating a more demanding consumer environment, with brands looking for new ways to create relevance, excitement and value.

    But there is not enough public evidence to say that Gucci selected China specifically to reduce manufacturing costs.

    And that is precisely why the story is more interesting without that assumption.


    THE MYTH OF “MADE IN ITALY”

    Luxury has always understood the power of geography.

    Paris.

    Milan.

    Florence.

    Geneva.

    Tokyo.

    Certain places have become synonymous with particular forms of expertise.

    For Gucci, Italy isn’t simply a manufacturing location.

    It is part of the brand’s cultural identity.

    But modern luxury supply chains are rarely as simple as a single country.

    A product can involve materials, components, specialist techniques and manufacturing processes spanning several countries before it reaches a customer.

    European Union rules on non-preferential origin recognise this complexity, generally determining origin for goods involving multiple countries through the concept of last substantial transformation, subject to the applicable rules.

    That doesn’t make “Made in Italy” meaningless.

    Quite the opposite.

    It demonstrates why provenance is a sophisticated concept rather than simply a postcode.

    The real question is no longer only:

    Where was it made?

    It is:

    What expertise was required to make it?


    FROM COUNTRY OF ORIGIN TO COUNTRY OF EXPERTISE

    This may be where luxury is heading.

    A watch can be Swiss.

    An eyewear collection can involve Japanese manufacturing.

    A fragrance can be produced in France.

    A sneaker can be manufactured in China.

    And the same global luxury house can still maintain a distinctly European identity.

    Gucci’s own manufacturing footprint already reflects this reality.

    The old luxury equation was relatively simple:

    Italy = craftsmanship.

    The new equation is considerably more complicated:

    Design + expertise + materials + technology + craftsmanship + scarcity + brand identity + cultural relevance.

    Geography remains part of that equation.

    But it is no longer necessarily the entire equation.


    THE PRICE OF THE NAME

    Then there is the uncomfortable part.

    What exactly is the customer paying for?

    A sneaker doesn’t cost hundreds of dollars because of the rubber sole alone.

    The price incorporates an entire ecosystem:

    Design.

    Creative direction.

    Materials.

    Manufacturing.

    Distribution.

    Brand heritage.

    Marketing.

    Retail experience.

    Cultural relevance.

    And, inevitably, the name printed on the box.

    That last element is enormous.

    Luxury has always sold objects, but it has also sold meaning.

    A Gucci handbag is not simply leather.

    A Rolex is not simply steel.

    A Ferrari is not simply an engine.

    The object becomes valuable partly because of the story surrounding it.

    Which brings us back to the label.

    If a Gucci sneaker is manufactured in China but designed under Demna, developed within Gucci’s creative and commercial system, sold through Gucci boutiques and presented as a Gucci product, does its country of manufacture change its luxury status?

    There is no universal answer.

    For some consumers, provenance will remain fundamental.

    For others, design and cultural relevance may matter more.

    And that tension is exactly what makes this moment worth watching.


    DEMNA AND THE NEW GUCCI

    The timing makes the story even more significant.

    The Drip isn’t simply another Gucci sneaker.

    It is part of the beginning of Demna’s Gucci era.

    The designer’s arrival represents a new creative chapter for one of fashion’s most recognisable houses, and the Drip is one of the first products through which that direction becomes visible. Gucci itself identifies it as Demna’s first sneaker for the brand.

    Its design feels deliberately contemporary.

    Less about preserving an image of luxury.

    More about asking what luxury can look like now.

    That distinction matters.

    The modern luxury consumer doesn’t necessarily want a product that looks expensive.

    They want something that means something.

    Something recognisable without being obvious.

    Something culturally relevant.

    Something that can move between fashion, street culture, social media and everyday life.

    The Drip belongs to that world.

    Its manufacturing origin simply adds another layer to the conversation.


    WHEN THE LABEL BECOMES THE STORY

    There is a strange irony here.

    Luxury brands spend enormous amounts of money creating narratives around their products.

    With the Drip, the manufacturing label has become part of the narrative itself.

    That can be complicated.

    Reuters reported that some luxury-industry analysts see potential tension between China-made products and Gucci’s long-standing association with Italian craftsmanship. Those are industry interpretations, however, rather than evidence that the product has already damaged Gucci’s positioning or consumer demand.

    The eventual answer will come from consumers.

    Not headlines.

    Not social-media arguments.

    Not assumptions about where a product should be made.

    But whether customers believe the object delivers enough design, quality, desirability and cultural value to justify its price.

    Because luxury has always been, at its core, an agreement between a brand and its customer.

    The brand says:

    This is special.

    The customer decides whether to believe it.


    THE NEW LUXURY MAP

    Perhaps the most important consequence of Gucci’s China-made sneaker isn’t what it says about China.

    It is what it says about Italy.

    And, more broadly, about the future of luxury.

    For decades, country of origin functioned almost like a guarantee.

    Made in Italy.

    Made in Switzerland.

    Made in France.

    The location itself communicated expertise.

    But as technology improves and manufacturing capabilities become increasingly distributed around the world, luxury houses have more choices than ever.

    The next generation of luxury may therefore be less interested in a single manufacturing postcode and more interested in why a particular place was chosen.

    Where is the best leather?

    Where is the strongest technical expertise?

    Where is the most appropriate craftsmanship?

    Where can a particular construction be executed at the required standard?

    Where does the product make the most sense?

    Those questions are far more complicated than simply asking whether something was made in Italy or China.

    And they may become increasingly important as luxury brands rethink how they manufacture, price and position products.


    SO, DOES “MADE IN CHINA” CHANGE GUCCI?

    It changes the conversation.

    It doesn’t erase Gucci’s Italian manufacturing heritage.

    It doesn’t mean Gucci has moved its entire production operation to China.

    It doesn’t make the sneaker counterfeit.

    And it doesn’t, by itself, tell us whether the product is better or worse.

    What it does do is challenge one of luxury’s oldest assumptions:

    that geography and value are inseparable.

    Gucci continues to have the overwhelming majority of its manufacturers in Italy, while also using specialist manufacturing capabilities across different countries and, now, China for specific sneaker models.

    That may be less dramatic than the internet’s version of the story.

    But it is far more revealing.

    Because the future of luxury may not be about choosing between Italy and China.

    It may be about understanding that modern luxury can be simultaneously local in identity and global in production.

    The atelier still matters.

    The designer still matters.

    The material still matters.

    The craftsmanship still matters.

    But so does technology. So does cultural relevance. So does the ability to manufacture something precisely for the way people want to live now.

    The Gucci Drip has simply made that evolution visible.

    And perhaps that is the real story behind the label.

    Luxury isn’t losing its borders.

    It’s learning how to exist beyond them.


    INSYDE

    The world of luxury is changing. We’re watching what comes next.

    Sources

    European Commission — Non-Preferential Rules of Origin

    Gucci — Men’s Drip Sneaker

    Gucci — Where Gucci Products Are Made

    Gucci Responsible Supply Chain

    Reuters — Gucci’s New “Made in China” Sneaker Models

    Kering — 2026 First-Half Results